
Interface Stock And Its First Natural Rubber Social Assessment
- Interface completed and published an ISO compliant Social Life Cycle Assessment of natural rubber used in its nora rubber flooring, providing a structured view of social conditions across its supply chain.
- This first-of-its-kind S LCA in the flooring sector gives Interface a measurable social performance baseline that can inform sourcing, product positioning and sustainability-led project bids.
- We will look at how Interface's investment narrative interacts with this first-of-its-kind natural rubber social assessment disclosure.
Scan how Interface's approach to supply chain transparency compares with other potential holdings by reviewing a curated set of 31 resilient stocks with low risk scores that lean into resilience and disciplined fundamentals.
Interface Investment Narrative Recap
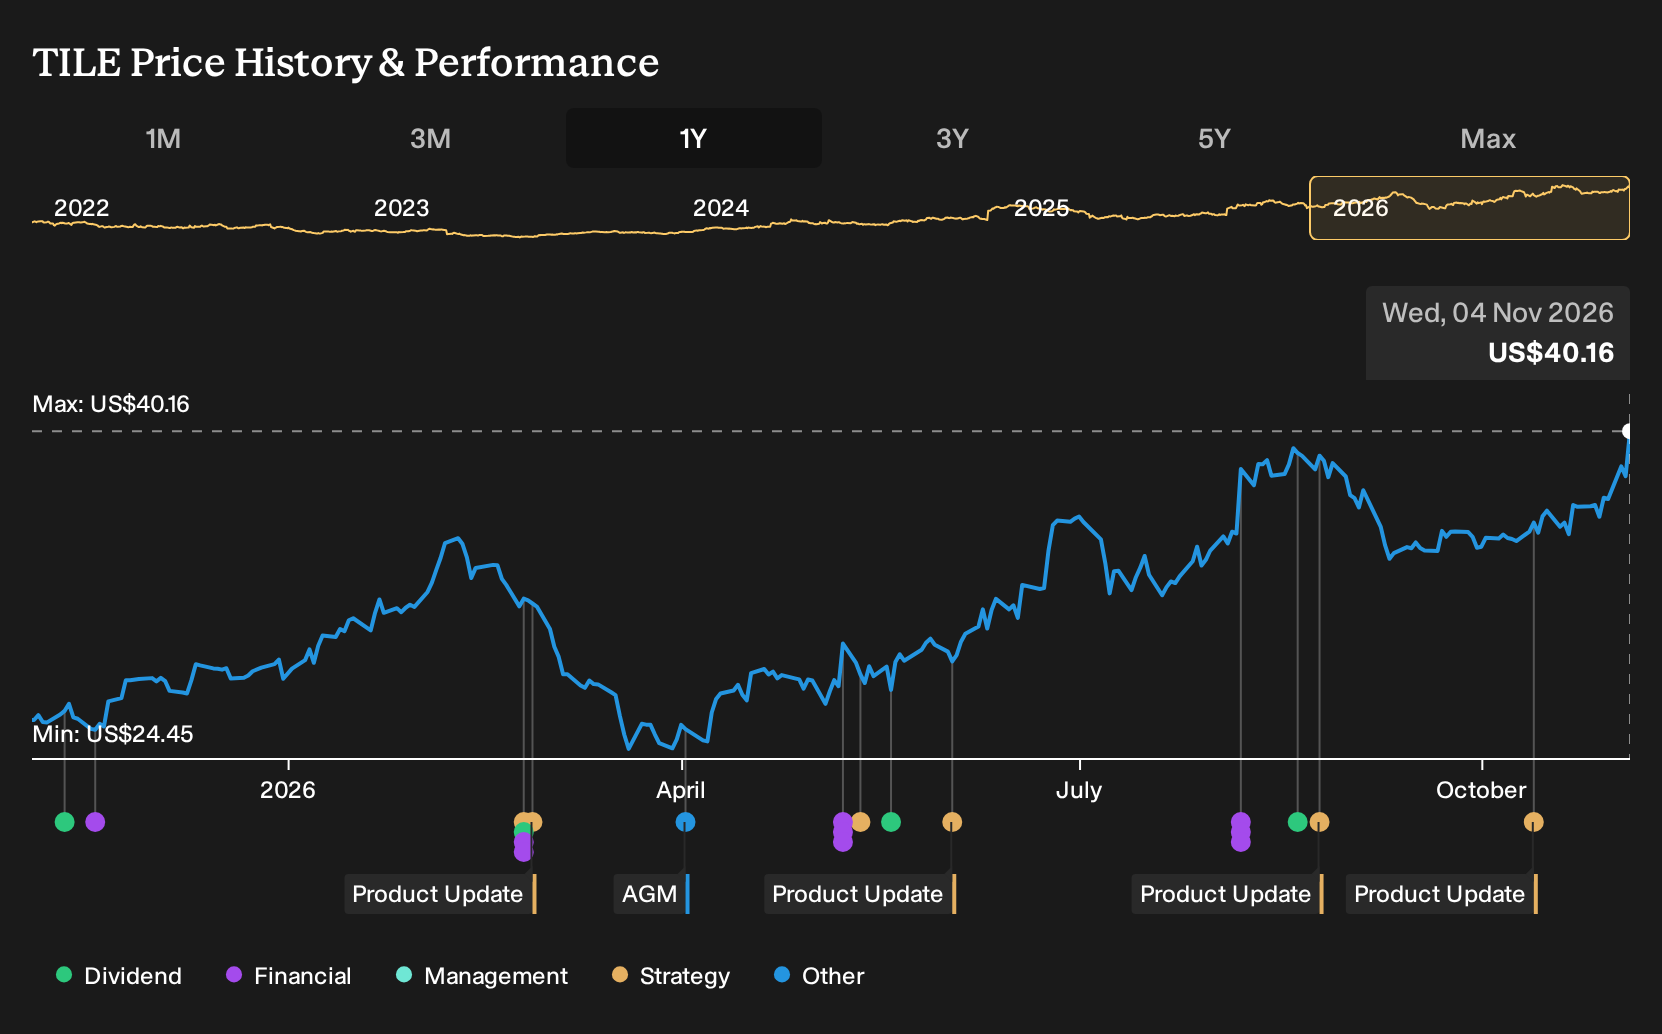
To own Interface, you need to believe the One Interface model, margin work from automation and demand across corporate, healthcare and education can support steady earnings over time. The near term swing factor is execution on this margin story while keeping volumes healthy at a time when expectations and the share price have already moved up.
The biggest risk is that tariff exposure and cost inflation pressure profits faster than pricing, productivity and product mix can offset. The new Social Life Cycle Assessment strengthens Interface's sustainability credentials, but it does not look like a material near term financial catalyst on its own.
The recent ISO compliant Social Life Cycle Assessment on natural rubber sits alongside Interface's broader sustainability focus, including low carbon and recycled materials and a cradle to gate carbon negative rubber prototype. Together, these disclosures build a clearer operational story that can matter when large projects screen suppliers on product impact and traceability.
For catalysts, that matters most where Interface is bidding into sustainability led projects that value verified data as much as price and design. If the firm combines this rubber assessment with ongoing automation gains and expansion of Open Air carpet tiles, thinner gauge LVT and new nora platforms, investors can track whether backlog and margins reflect that execution or not.
Interface's current analyst storyline points to revenues of $1.7b and earnings of $157.1 million by 2029. That path assumes 5.9% yearly revenue growth and an earnings increase of $11.5 million from $145.6 million today.
Uncover why Interface's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame Interface’s big swing factor as faster margin lift from automation rather than tariff or cost risk. Before this rubber S LCA news, the bullish camp was already pencilling in roughly 6.8% annual revenue growth and about US$163.0 million in earnings by 2029. Those views could shift as this disclosure lands.
Explore 2 other Interface fair value estimates, including one that suggests as much as 24% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Interface research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Interface. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interface's overall financial health at a glance.
Looking For More Ideas Beyond Interface?
If Interface has sharpened your thinking on quality, risk and long term execution, it can be useful to line it up against other potential holdings with different strengths.
- Focus on financial resilience and balance sheet strength by reviewing a curated list of solid balance sheet and fundamentals (24 results) that keeps debt and liquidity in clear view.
- Hunt for potential mispricings by scanning a hand picked 35 high quality undervalued stocks where fundamentals and market expectations do not fully match.
- Add some less crowded ideas to your watchlist by checking a targeted 19 high quality undiscovered gems that pairs solid business quality with lower profile coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com