
Should Quarterly Earnings Growth Require Action From Pursuit Attractions and Hospitality (PRSU) Investors?
- Pursuit Attractions and Hospitality reported third quarter 2026 revenue of US$251.53 million and net income of US$82.81 million, with basic earnings per share from continuing operations of US$2.99.
- Across the first nine months of 2026, Pursuit Attractions and Hospitality generated US$436.67 million of revenue and US$73.04 million of net income. This highlights how seasonality and high margin peak periods shape reported earnings.
- We will now look at how Pursuit Attractions and Hospitality's investment narrative is influenced by this third quarter earnings strength.
Scan how Pursuit Attractions and Hospitality’s earnings profile compares with peers by lining it up against 19 high quality undiscovered gems that could be flying under most investors radar.
Pursuit Attractions and Hospitality Investment Narrative Recap
To own Pursuit Attractions and Hospitality, you need to believe that its collection of high demand destinations can keep filling beds and gondola cabins while management executes on a project pipeline of more than US$300 million. The third quarter print, with US$251.53 million of revenue and US$82.81 million of net income, supports that thesis but does not rewrite it.
The key near term catalyst is still how efficiently new and refreshed attractions such as Jasper SkyTram and Banff Gondola are brought online and monetised. The biggest risk remains disruption at a concentrated set of marquee locations, from climate related events to demand softness that could pressure pricing and compress margins.
The latest third quarter and year to date earnings announcement is the most relevant development here. Revenue of US$251.53 million and basic earnings per share from continuing operations of US$2.99 for the quarter, together with nine month revenue of US$436.67 million, provides an updated read on how Pursuit Attractions and Hospitality is converting experiential travel demand into profit.
This disclosure also matters for your view on execution and funding capacity. Higher year to date net income of US$73.04 million compared with the prior year period, together with a sizeable project pipeline, acquisition appetite and share repurchase authorisation, helps frame how much operational misstep, weather disruption or pricing pressure the business can absorb while still supporting its key catalysts.
Pursuit Attractions and Hospitality's current earnings of $41.9 million are set against analyst projections for $64.8 million of earnings on $540.2 million of revenue by 2029, which assumes revenue growth of 3.8% per year and an earnings increase of about $22.9 million from today.
Uncover how Pursuit Attractions and Hospitality's fair value indicates a 10% potential upside to its current price before the market closes that gap.
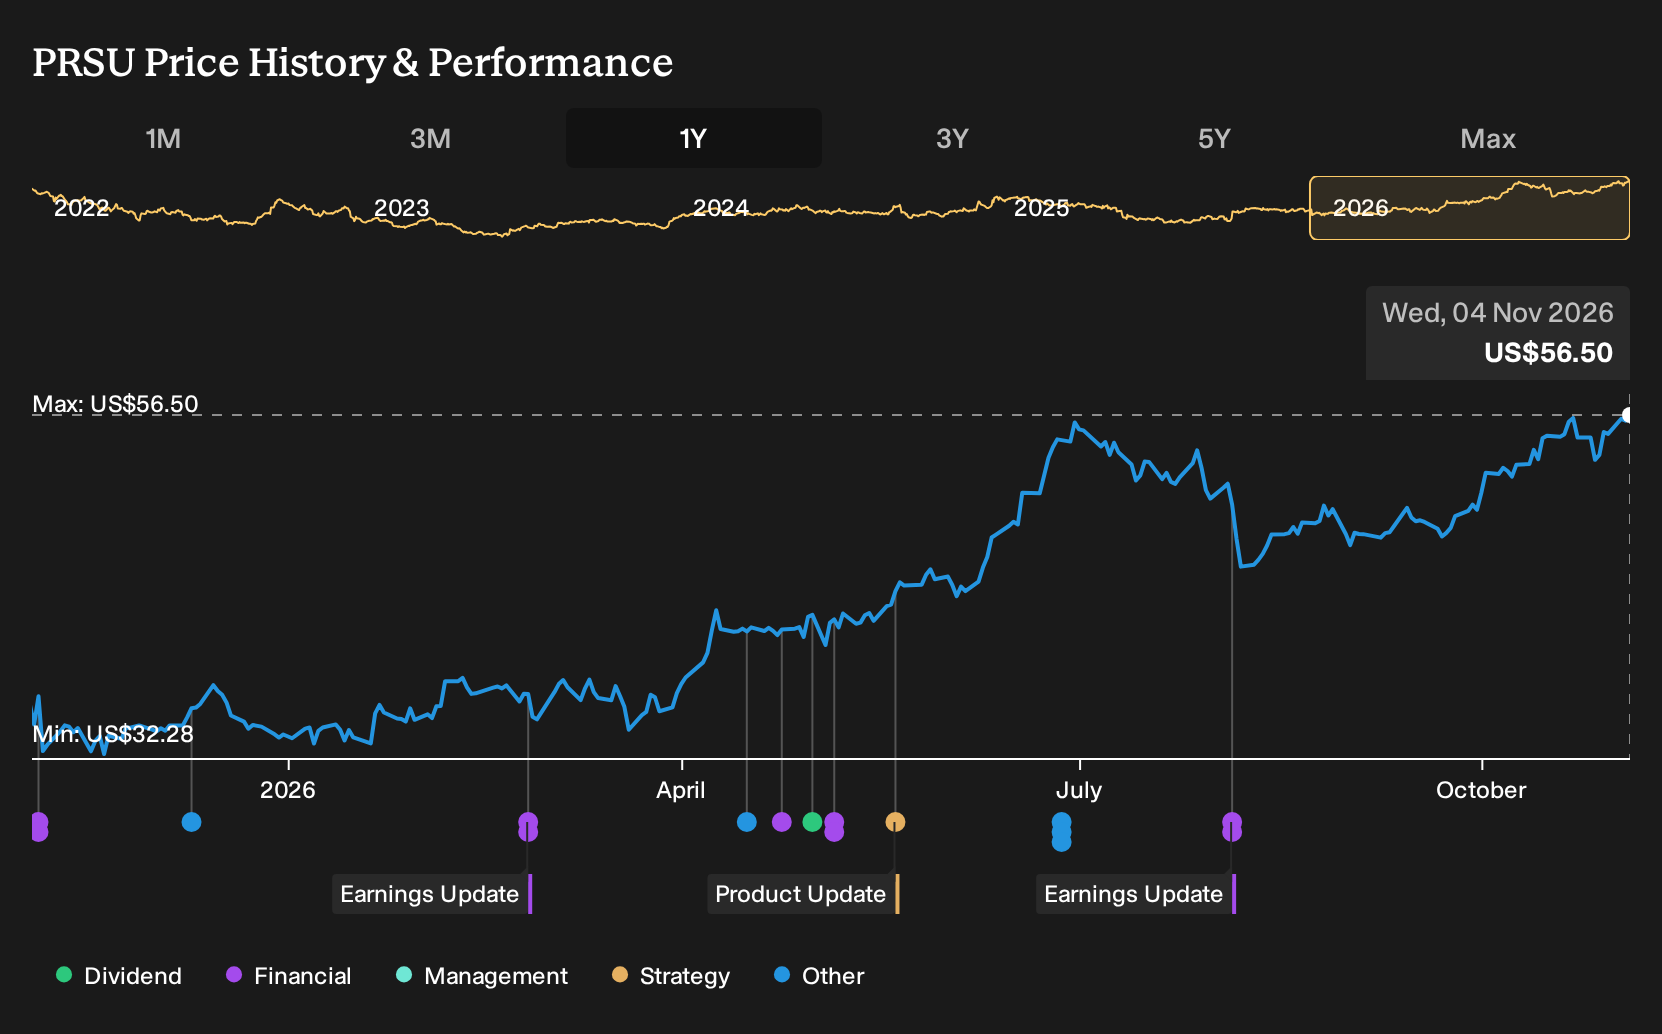
Exploring Other Perspectives
For Pursuit Attractions and Hospitality, the most optimistic analysts lean hard into the power of integrated guest journeys as the real earnings engine. They were already pencilling in 3.9% annual revenue growth to about US$523.9 million and earnings of US$65.4 million by 2029. After this earnings release, those upbeat assumptions may look either more achievable or in need of a reset. You will want to compare this fresh set of quarterly numbers with both the bullish and the more cautious forecasts to see which story makes more sense to you.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pursuit Attractions and Hospitality research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Pursuit Attractions and Hospitality. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pursuit Attractions and Hospitality's overall financial health at a glance.
Looking for more investment ideas beyond Pursuit Attractions and Hospitality?
Once you have a clear view on Pursuit Attractions and Hospitality, it can help to widen the lens and compare it with other businesses that fit different risk, income and balance sheet profiles using the Simply Wall St Screener.
- For investors who care most about financial resilience, start with companies that show consistently strong balance sheets and fundamentals by scanning the list of solid balance sheet and fundamentals (24 results).
- If your focus leans toward quality at a potentially attractive entry point, line up Pursuit Attractions and Hospitality against a 35 high quality undervalued stocks and see how its valuation compares on the same framework.
- For readers who put reliable income first, broaden your watchlist to businesses offering robust cash distributions by reviewing a curated 5 dividend fortresses that can complement a total return approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com