
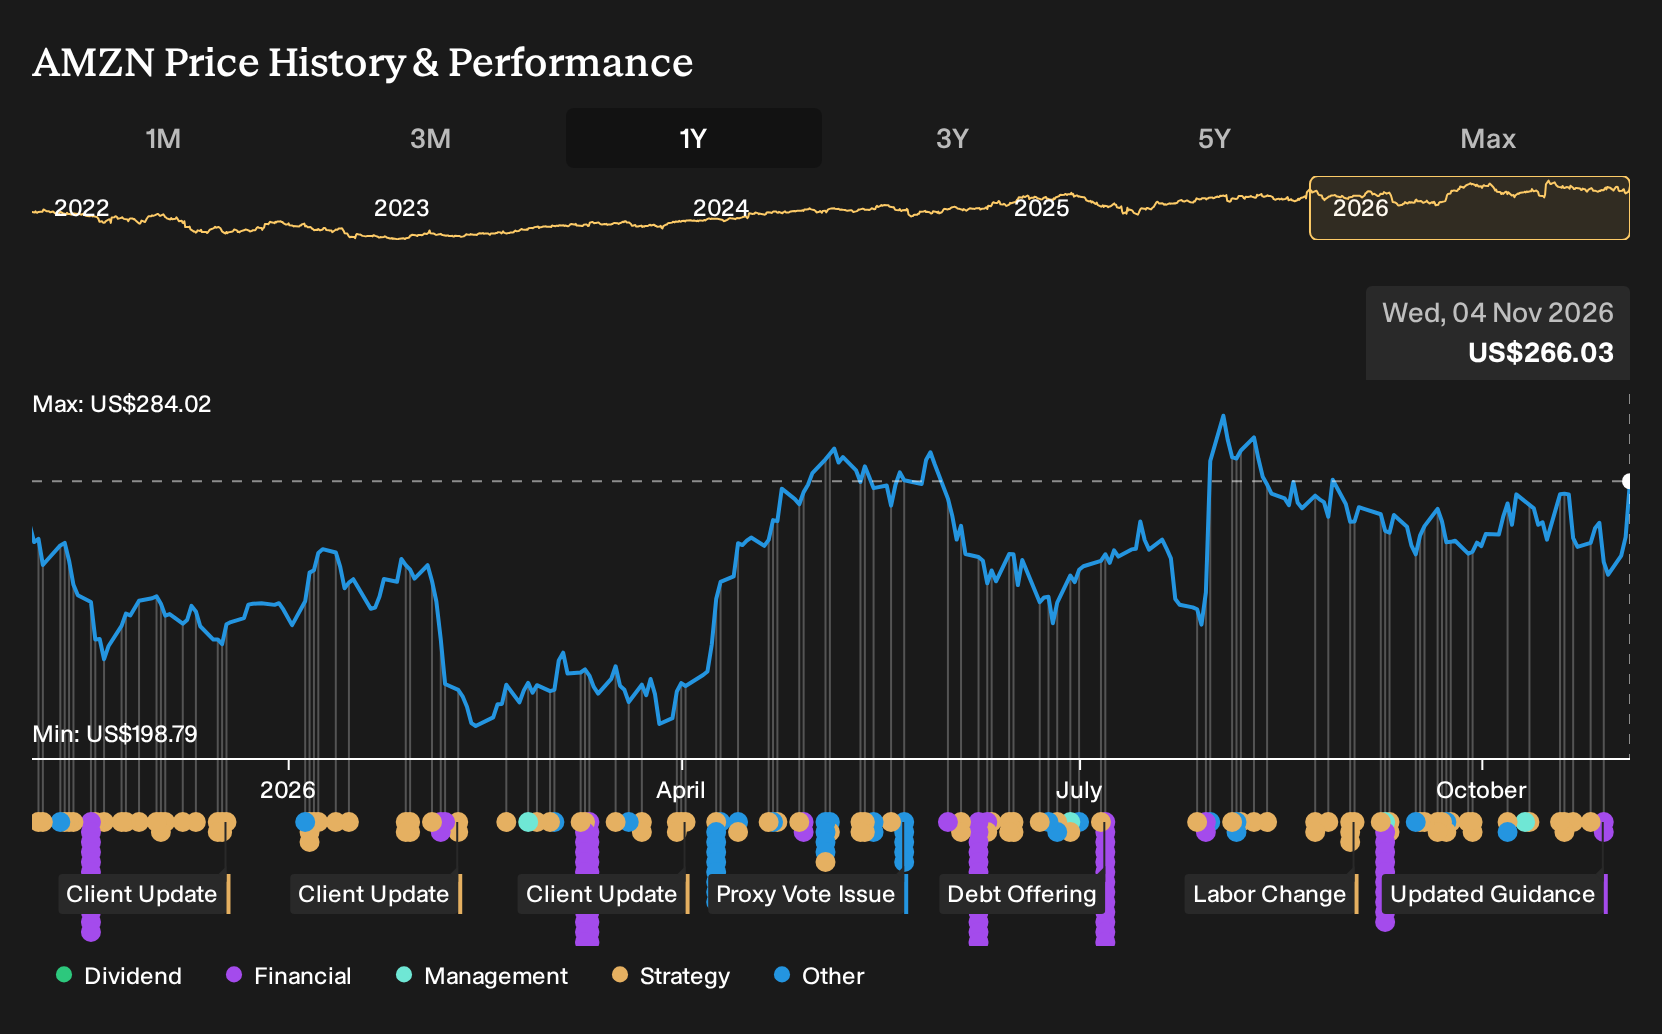
Why Amazon Stock Is Up 6.1% And What's Next
- After the early November 2026 U.S. midterm elections, Amazon.com moved into a new regulatory backdrop as Democrats gained control of Congress and several key governorships. This signaled tougher scrutiny of AI data centers and related infrastructure spending.
- The political shift directly targets the AI buildout that underpins Amazon’s heavy data center and chip investment program. This raises the prospect of lower capital intensity that could reshape how the business balances growth ambitions with free cash flow discipline.
- We will look at how Amazon.com’s AI heavy investment narrative intersects with new Democratic scrutiny of data center expansion.
Compare how Amazon.com’s AI buildout story stacks up against other heavy spenders by scanning our hand picked 53 AI infrastructure stocks before the next policy headline hits.
Amazon.com Investment Narrative Recap
To own Amazon.com, you need to believe its heavy AI and infrastructure spending eventually turns into long lived cloud, chips and advertising income that supports strong cash generation. In the short term, the key question is whether that AI driven AWS and ads story holds up while regulators lean on data center expansion and tax incentives.
Recent guidance points to fourth quarter 2026 net sales of US$240.0b to US$247.0b and operating income of US$28.5b to US$33.5b. That keeps attention squarely on execution, not just politics. The key risk right now is that very large annual CapEx near US$220b, combined with new regulatory scrutiny, compresses free cash flow longer than investors are comfortable with.
The most directly relevant update is Amazon.com’s October 29 guidance and third quarter 2026 results. Management flagged expected fourth quarter net sales growth of 12% to 16% versus 2025 and operating income above the prior year. Advertising revenue, excluding currency effects, grew 12% in the third quarter, with management expecting high teens growth in the fourth quarter.
That outlook matters for the current regulatory backdrop. It indicates the core engine is still producing higher sales and operating profit while AI infrastructure spending and political pressure on data centers rise. If AWS and high margin ad revenue continue to scale within this range, those segments help buffer the risk that new rules or slower approvals stretch the payback on Amazon.com’s AI buildout.
What The Analyst Forecasts Assume For Amazon.com
Amazon.com's AI heavy investment story sits on top of some very specific analyst assumptions about revenue and profit. Consensus modeling points to revenue growing by 14.4% each year over the next three years, even as analysts factor in profit margins easing from 17.4% today to 14.0% by 2029.
On earnings, the group view is that the business could reach US$163.0b by 2029, compared with US$135.3b today. That is an increase of about US$27.7b in earnings, which gives you a sense of how much extra profit the current AI and data center spending is expected to support over the next few years. Forecasts are far from uniform though, with estimates ranging from US$116.5b to US$196.1b, so the spread of outcomes analysts are considering is wide.
Behind those profit expectations sits a valuation bridge that matters for anyone thinking about how policy risk feeds into Amazon.com's market narrative. The consensus price target of US$330.59 is built on the idea that by 2029, revenue reaches US$1,161.3b and earnings total US$163.0b, with the shares trading on a P/E of 29.2x compared with 20.1x today. That implies investors would be paying a higher multiple for the stock at the same time that margins are modeled to be lower, so the quality and durability of AI driven cash flows become even more central to the story.
Amazon.com's narrative projects US$1,161.3b revenue and US$163.0b earnings by 2029. This framework assumes 14.4% yearly revenue growth and an earnings increase of about US$27.7b from US$135.3b today.
Uncover why Amazon.com's fair value indicates a 24% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community offers 32 fair value views on Amazon.com, stretching from about US$274 to more than US$646 per share, so retail opinions already span deep discount to rich premium territory. When you set that against heavy AI data center CapEx near US$220b in 2026 and rising political scrutiny, you get a debate on whether future free cash flow or regulatory risk deserves more of your attention. Use these contrasting angles to stress test your own assumptions rather than rely on any single narrative.
Explore 31 other Amazon.com fair value estimates, including one that suggests as much as 143% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Amazon.com research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amazon.com. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amazon.com's overall financial health at a glance.
Looking For More Investment Ideas Beyond Amazon.com?
Once you have formed a view on Amazon.com, it can help to compare that thesis with other opportunities that line up with your risk tolerance, income needs, or focus on balance sheet strength. The Simply Wall St Screener lets you filter the market quickly so you spend more time weighing the numbers and less time hunting for tickers.
- If you want steadier candidates that aim to limit downside, start by scanning a set of 31 resilient stocks with low risk scores that may better match a more cautious approach.
- For investors who care most about financial resilience and funding capacity, review a list of solid balance sheet and fundamentals (24 results) to see which businesses pair cleaner balance sheets with solid fundamentals.
- If you are hunting for mispriced potential rather than headline giants, consider a curated 19 high quality undiscovered gems that could offer very different risk and reward profiles to Amazon.com.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com