
Learn Why The Bull Case For Middleby Stock Could Change Following Weaker Earnings Forecasts
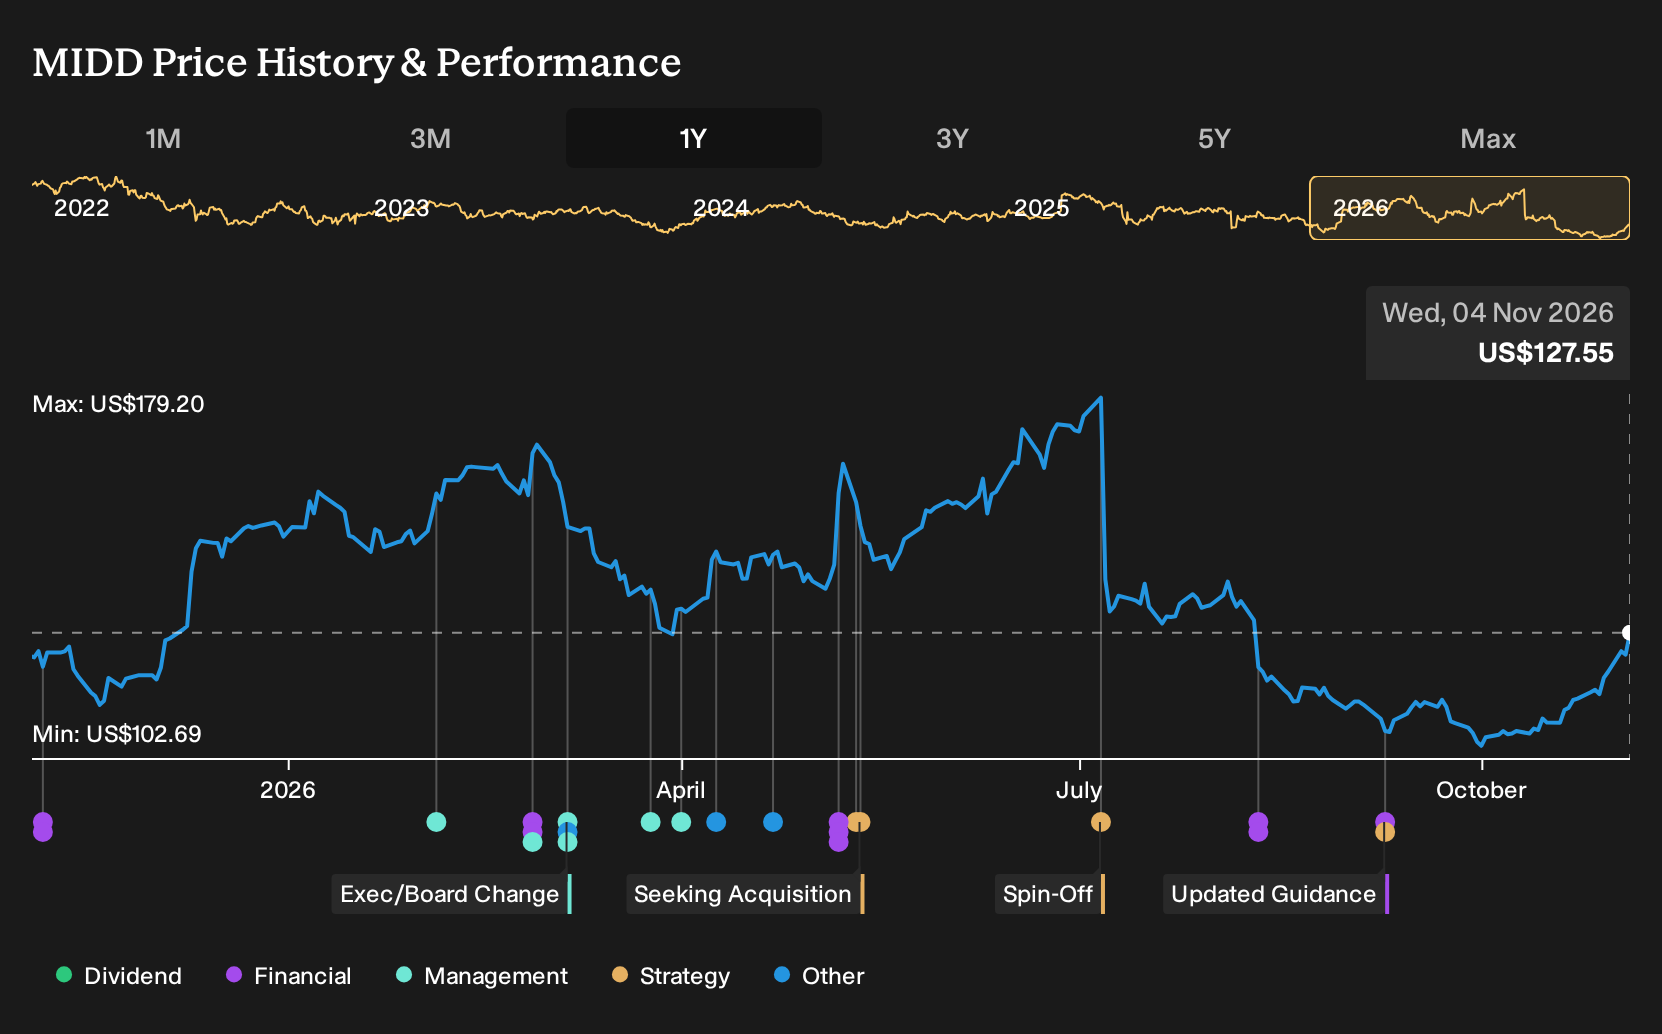
- Middleby has scheduled its Q3 2026 earnings release for 7:00 AM US Eastern Standard Time on 5 November 2026, followed by an earnings call, with consensus pointing to earnings of $1.74 per share and revenue that is expected to be lower than a year earlier.
- Forecasts indicate year over year declines in both earnings per share and revenue, and the slight downward revision to the EPS estimate over the past month may reflect concern about current demand, pricing, or cost pressures in Middleby’s commercial foodservice equipment operations.
- We will now assess how Middleby’s expected year over year earnings and revenue declines might affect its longer term investment profile.
Middleby Investment Narrative Recap
To own Middleby, an investor needs to be comfortable with a focused commercial foodservice equipment business where the thesis leans on margin improvement, Ice & Beverage scaling and aftermarket parts and service becoming a larger piece of the mix. The Q3 2026 expectations for lower earnings and revenue highlight that near term demand, pricing and cost pressures are still very real.
The key short term swing factor is execution on margin uplift programs while managing weaker volumes without eroding pricing power. The biggest risk is that Ice & Beverage and beverage automation keep running at lower profitability for longer, especially if restaurant traffic and quick service unit openings stay soft and delay upgrade and replacement cycles.
The most relevant near term milestone is Middleby’s Q3 2026 earnings release and call on 5 November 2026. Consensus points to earnings of US$1.74 per share, with a sharp year on year deterioration in both earnings and revenue for the quarter. Those numbers provide a timely check on how well the operational streamlining is holding up under softer demand.
Attention naturally falls on the operational excellence program, the exit from the loss making Brewing platform and the ramp of Ice & Beverage and automation projects such as the KFC KWENCH program. The upcoming update can clarify whether freight and steel inflation, mix into lower margin platforms and slower quick service customer spending are pressuring that margin expansion story or simply creating a bump in the road.
Middleby’s Longer Term Setup Through The Numbers
Middleby's narrative projects revenues of US$2.8b and earnings of US$360.7m by 2029, off a base of US$320.0m in earnings today, which implies a yearly revenue decline of 5.8% and an earnings increase of about US$40.7m if analysts are right about the long term mix and margin story.
Analysts building this story into their models are assuming a commercial equipment specialist that leans more on profitability than expansion in sales. Instead of chasing higher volumes, the thesis rests on a slow top line decline alongside higher profit margins and lower share count over time.
On the top line, consensus has Middleby's revenue falling by 5.8% per year over the next three years. That implies a smaller overall business by the late 2020s, but one that depends more on higher value segments and pricing discipline than on pure unit growth.
Earnings today are estimated at US$320.0m. The forecast points to US$360.7m of profit by 2029, which is an increase of roughly US$40.7m even with shrinking revenue. For an investor, this pairing of a contracting sales base with higher earnings is a clear sign the story being modelled is focused on better margins, mix and capital returns.
The assumptions behind that path are explicit. Profit margins are projected to rise from 9.4% today to 12.7% in three years. That would be a step change in profitability for Middleby and would need sustained gains from operational excellence work, the removal of lower quality earnings and a bigger slice of high margin aftermarket parts and service.
Shareholders are also being told to expect fewer shares in issue. Consensus has the share count falling by about 7.0% per year for the next three years. When a business combines higher margins with a shrinking share base, earnings per share can move up faster than overall profits, which is reflected in the US$9.44 EPS estimate for 2029.
The valuation overlay on these metrics is straightforward. For the analyst price target to hold, Middleby would need to earn US$360.7m on US$2.8b of revenue in 2029 and trade on a P/E of 20.6x, compared with 14.5x today and below the current 23.7x for the wider US Machinery industry. The entire case depends on whether you think that higher earnings on a smaller revenue base and a higher multiple feels realistic for this business model.
Those numbers sketch a tight narrative for readers. The under-pressure Q3 2026 setup, with weaker sales and earnings, is set against a longer term picture in which Middleby is leaner, more profitable and carries a richer valuation multiple. Your own view on the stock will likely come down to how confident you are that management can push margins from 9.4% toward 12.7%, grow earnings by roughly US$40m and support a higher P/E, all while revenue declines at 5.8% a year.
Uncover why Middleby's fair value indicates a 22% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One contrasting angle on Middleby focuses on the risk that freight, tariff and materials costs keep eating into profits more than consensus expects. The most pessimistic analysts were already working with faster revenue declines of about 7.8% a year and only US$352.3m of 2029 earnings. With today’s Q3 call, those views could easily shift again. This serves as a reminder that reasonable analysts can look at the same information and reach very different conclusions.
Explore another Middleby fair value estimate, including one that suggests as much as 18% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Middleby research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Middleby. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Middleby's overall financial health at a glance.
Looking for more investment ideas beyond Middleby?
If Middleby sits on your watchlist but you want a wider bench of options, it helps to line it up against other stocks with clear financial profiles. The Simply Wall St Screener gives you that broader field of candidates so you can compare quality, balance sheet strength and income potential side by side.
- For investors who care most about financial resilience, start with companies that pair sturdy balance sheets with solid fundamentals through the list of solid balance sheet and fundamentals (24 results).
- If your priority is capital preservation and smoother return profiles, narrow your search to businesses that screen well on resilience and risk using the 31 resilient stocks with low risk scores.
- Those hunting for underfollowed opportunities can focus on lesser known stocks with strong underlying metrics by scanning the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com