
Is EverQuote (EVER) Reasonable On Earnings Or Getting Stretched?
EverQuote has seen its share price move sharply in recent years, which puts fresh attention on what investors are really paying for. With the stock now reflecting a very different market view than a few years ago, the open question is whether that current price is supported by the company’s earnings power.
- EverQuote has delivered a 272.3% return over the past 3 years, which makes it important to ask how much of that shift is backed by sustainable profit generation.
- The business model depends heavily on how efficiently it turns insurance shopper traffic into paid policies, which can shape both current earnings quality and how dependable those profits look over time.
- Your read on EverQuote is one view; the desks covering it have another. See what analysts think EverQuote's shares could be worth.
For investors, the debate is whether EverQuote’s recent share price level is justified by the earnings it is producing today and is expected to produce over time.
If you are weighing whether EverQuote's 272.3% three year return lines up with its earnings profile, it can help to compare that same question across 35 high quality undervalued stocks.
Is EverQuote Still Cheap on Earnings?
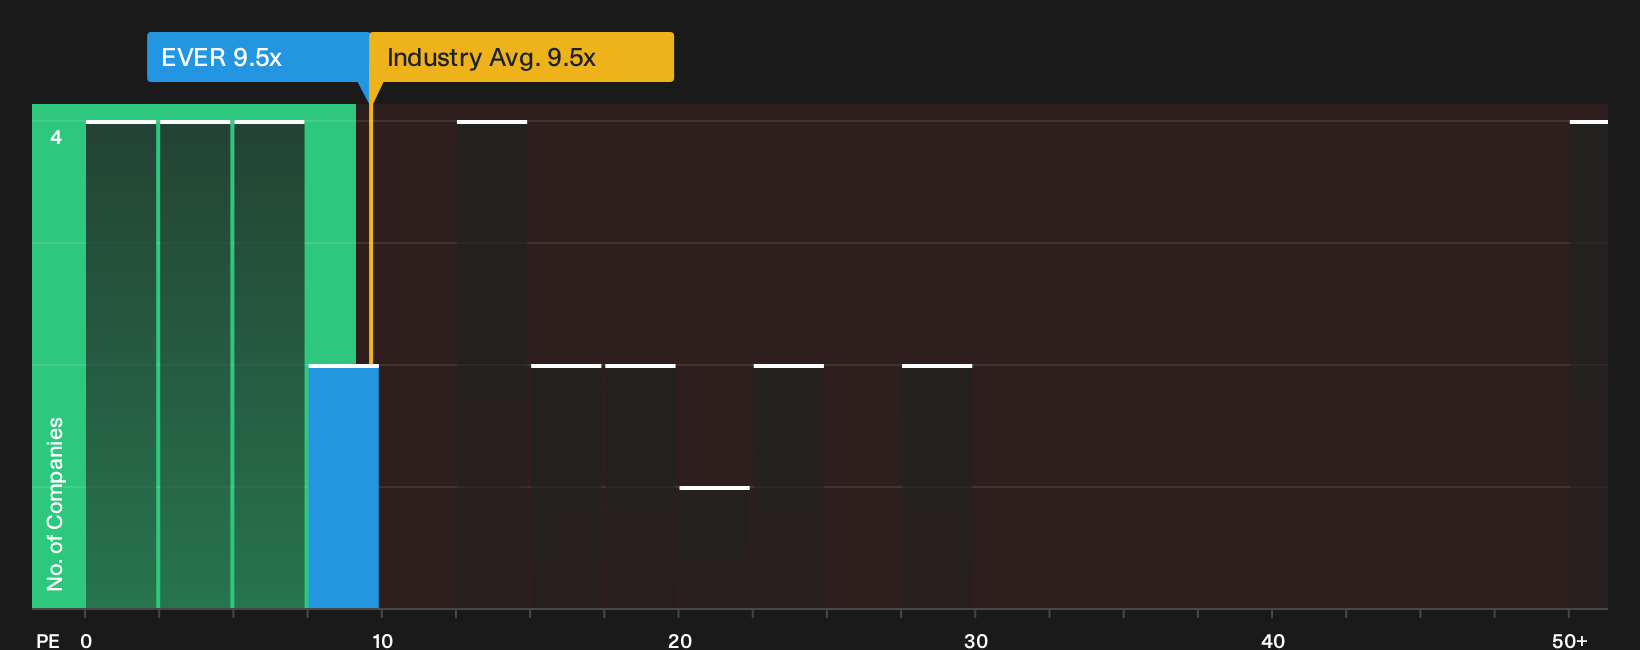
The P/E ratio suits EverQuote because earnings now sit at the center of how the market frames its potential. On headline numbers, EverQuote trades on a P/E of 9.5x, which is almost exactly in line with the broader Interactive Media and Services sector at about 9.5x and a touch above the peer group around 8.1x. That small premium to similar insurers and platforms suggests investors are already paying slightly more for each dollar of profit than they are for close comparables.
The fair value model that blends EverQuote’s growth profile, margins, size and risk points to a higher P/E than where the stock trades today. So even with the share price already rerating over the past three years, the current 9.5x still sits below what that tailored yardstick would imply is appropriate for the business. For anyone trying to decide whether EverQuote offers enough earnings for the price, this gap between the live multiple and the model benchmark is the piece worth investigating further. Explore the numbers behind EverQuote's P/E valuation.
The EverQuote Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the EverQuote valuation puzzle leaves off and spell out what kind of growth, margin profile and earnings path would need to hold for the stock to look meaningfully higher or lower than today’s price, based on scenarios shared on the Community page. Rather than lean on a single P/E or one model output, each narrative presents its own fair value assumptions so you can track those against future reported results.
Community investors looking at EverQuote are working from the same data, yet one group sees extra upside while the other treats it as closer to fully valued.
Bull case: 15% undervalued
"What makes EverQuote particularly interesting is that while the market appears to value it as a cyclical advertising business, the underlying economics increasingly resemble those of a high-return, cash-generative marketplace platform..."
Discover why this Narrative puts EverQuote at 15% undervalued.
Bear case: roughly fairly valued
"The main factor that has to go right is that EverQuote continues to convert carrier appetite for digital performance spend and AI tools into sustained revenue across auto and home while managing the planned step up in operating expenses..."
Explore why this Narrative puts EverQuote at roughly fairly valued.
EverQuote’s price is only one piece of the decision
To round out the picture on EverQuote, it helps to compare today’s valuation with where professional analysts think revenue, margins and earnings might head over the next several years. Explore where analysts expect EverQuote to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com