
Lam Research (LRCX) Tests Its Bull Case On Cautious Guidance And A Cheap Narrative
Lam Research (LRCX) is coming off a record quarter, with strong revenue and net income alongside fast growing recurring services and advanced packaging, yet cautious guidance and China related headwinds have unsettled some investors.
Lam Research’s share price has retreated sharply in the near term, with the stock down about 34% over the past month and posting a 30 day share price return of 33.68% and a 90 day share price return of 28.88%, as cautious guidance, China exposure and broader concerns around AI related spending have cooled enthusiasm after the record quarter. Even with that pullback and a latest share price of US$221.43, investors who held on through the last few years still sit on a very strong multi year total shareholder return. The company has recorded a 1 year total shareholder return of 37.16% and a 5 year total shareholder return of 279.56%, suggesting that recent weakness reflects a reset in risk perception rather than a clean break from the longer term story.
Seize the pullback in Lam Research as a chance to compare it with hand picked peers using the 53 AI infrastructure stocks powering the next wave of chipmaking demand.Bulls point to record results and Lam Research’s long runway in advanced packaging, while bears focus on China exposure and softer AI spend. Is the current share price closer to an opportunity or a warning sign as valuation comes into focus?
Most Popular Lam Research Narrative: 47.8% Undervalued
Against a last close of $221.43, the most followed Lam Research narrative anchors on a fair value of $423.85, which implies a wide gap that invites investors to scrutinize what is driving such a strong upside view.
Lam Research is the position I hold to be right about the AI memory bottleneck without having to be right about how long it lasts. That sentence is the entire thesis, so it is worth unpacking. Every direct memory holding, Micron, SanDisk, Seagate, makes money while supply stays short and loses the argument the moment capacity catches up. Lam makes money on the shortage and makes money on the response to it, because the capacity that eventually relieves the shortage has to be bought from somewhere, and a very large share of it gets bought from Lam.
See why 44 investors see Lam Research as 48% undervalued.
According to isidrohg, this thesis leans on a discount rate of 11.25% and a profit margin assumption of 31.27%, combined with a future P/E input of 54.40x, which together produce that $423.85 narrative fair value. Those parameters build a case that the recent pullback in Lam Research compresses the price far below what this narrative views as a reasonable long term outcome, even after accounting for cyclicality and sector risks.
Result: Fair Value of $423.85 (UNDERVALUED)
Still, two things could quickly flip this Lam Research narrative: a sharp pullback in AI related capex or tighter China export controls that hit orders.
Find out about the key risks to this Lam Research narrative.
Another View On Lam Research’s Valuation
The user narrative sees Lam Research as 47.8% undervalued at a fair value of $423.85. The SWS DCF model points in the opposite direction. On that framework, Lam Research at $221.43 trades above an estimated future cash flow value of $171.14, which flags the stock as overvalued. Which story do you treat as your anchor?
Look into how the SWS DCF model arrives at its fair value.
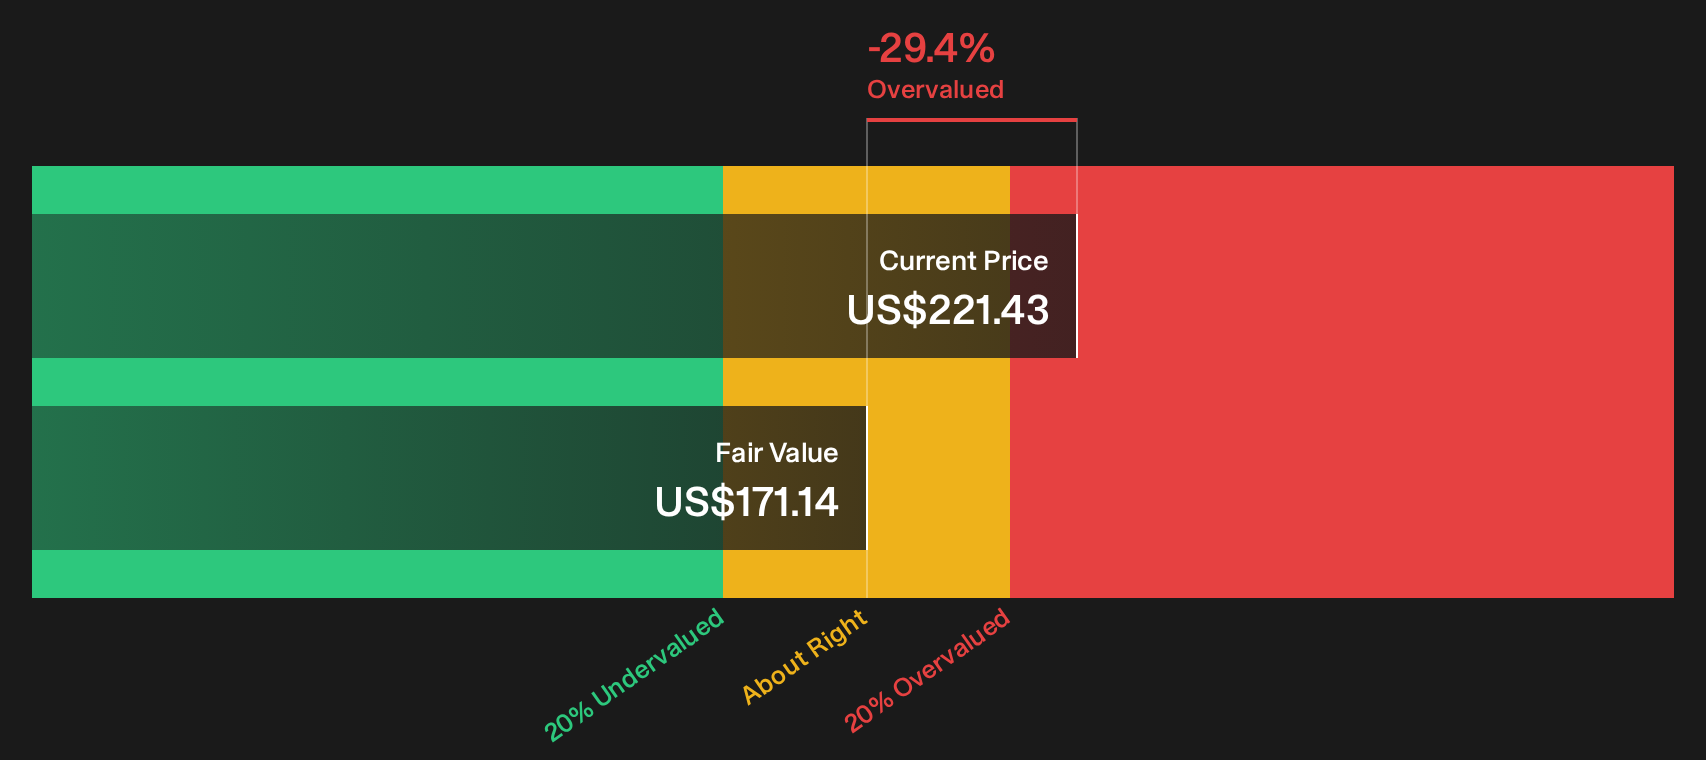
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lam Research for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Lam Research so far. If you want to move quickly rather than rely on headlines alone, start by weighing the 4 key rewards and 1 important warning sign.
Looking for more Lam Research sized ideas?
Big calls on a stock like Lam Research matter more when you can compare them against a wider bench of opportunities. Broaden your watchlist before the next move.
- Target long term compounding potential by reviewing companies on the 35 high quality undervalued stocks that combine strong fundamentals with prices the market has not fully recognised.
- Protect your downside as you hunt for upside by scanning resilient businesses through the 31 resilient stocks with low risk scores that score well on financial strength.
- Get ahead of the crowd by checking the 19 high quality undiscovered gems where solid balance sheets and cash flows have not yet attracted wide attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com