
United Bankshares (UBSI) Q3 Results Put Its Valuation Back In Focus
United Bankshares (UBSI) just released third quarter 2026 results, combining record net interest income, an expanding net interest margin, and fresh share repurchases with reported credit costs that remained contained through manageable net charge offs.
Against this backdrop of record net interest income and active buybacks, United Bankshares’ recent price momentum has been firm. The 1-month share price return is 6.03% and the year-to-date share price return is 28.24% at a latest share price of US$49.23, while long-term total shareholder returns of 39.96% over 1 year and 87.26% over 3 years point to investors steadily rewarding the story despite periodic credit cost headlines.
Scan beyond United Bankshares and compare its momentum and credit profile with a curated list of solid balance sheet and fundamentals (24 results) that are also managing risk while putting excess capital to work.
United Bankshares has already logged a strong run, yet its current price still sits below external valuation marks and implied intrinsic value. Is the recent rally the main event or just the opening act for the valuation story?
Price-to-Earnings of 12.9x: Is it justified?
On current figures, United Bankshares trades on a P/E of 12.9x, which sits below its peer group on one measure yet above on another, leaving investors with a mixed value signal at the recent price of $49.23.
The P/E ratio compares what you pay today for each dollar of earnings. It provides a simple shorthand for how the market values the bank’s profit stream. For a lender like United Bankshares, which reports net income of $512.08m on revenue of $1.26b and has an earnings record that data shows has grown 6.6% per year over the past 5 years, that lens is a common starting point for comparing it with other US banks.
On a direct peer comparison, the stock looks cheaper, with its 12.9x P/E described as good value relative to a 14.1x average for its comparison set. This indicates investors are not paying as high a multiple for similar earnings. At the same time, the same 12.9x is described as expensive when stacked against the broader US Banks industry at 11.3x and also above an estimated fair P/E of 11.5x, a level the market could move toward if sentiment cooled.
Explore the SWS fair ratio for United Bankshares.
Result: Price-to-Earnings of 12.9x (ABOUT RIGHT)
Still, United Bankshares depends heavily on US lending conditions and credit quality, so any sharp turn in loan performance or funding costs could challenge this valuation story.
Find out about the key risks to this United Bankshares narrative.
Another View on United Bankshares Valuation
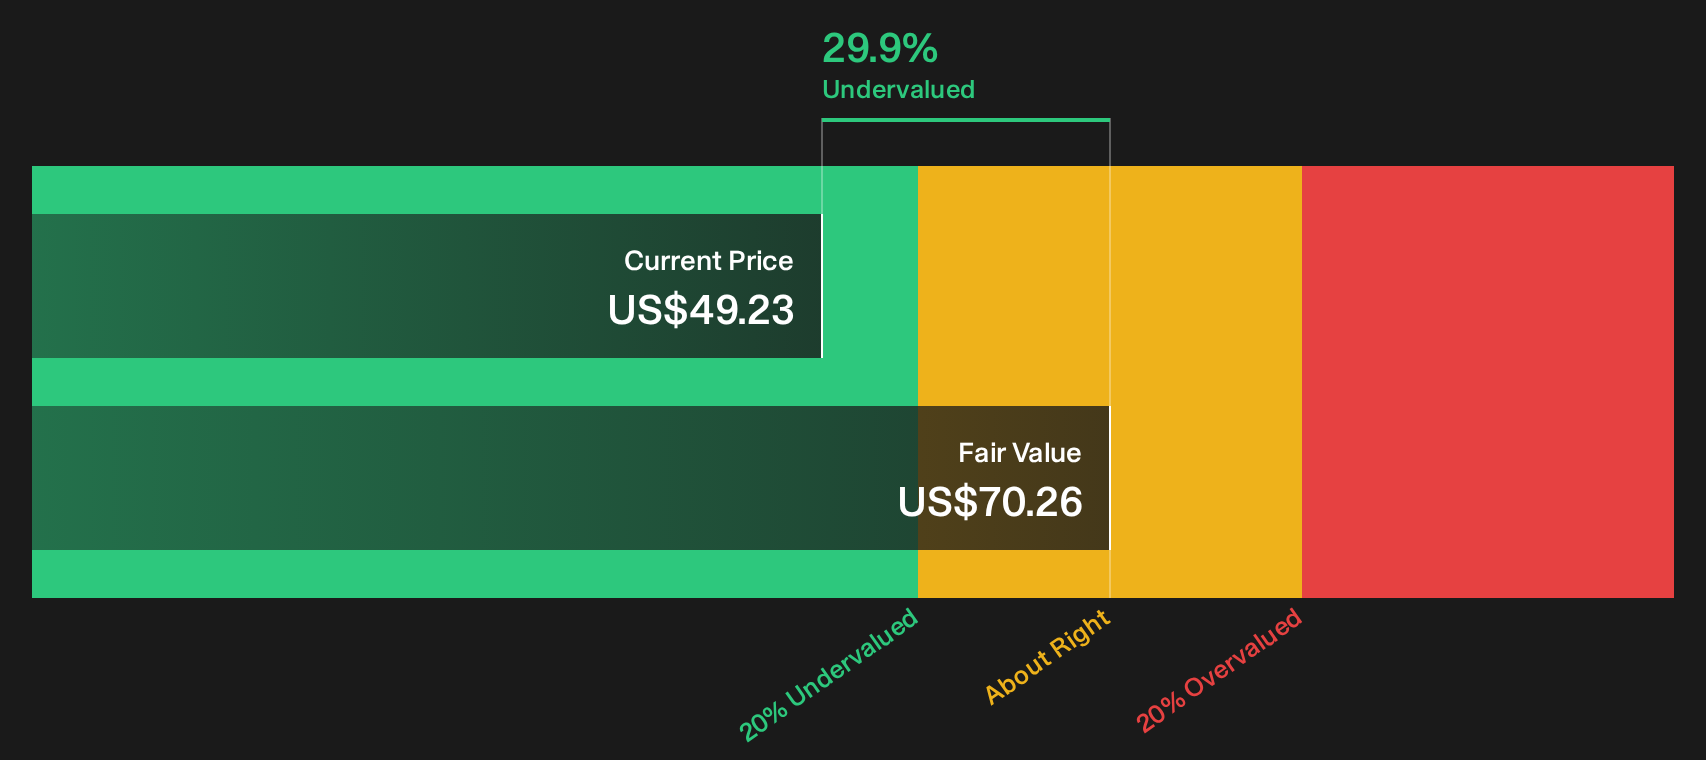
That 12.9x P/E tells only part of the story. Our DCF model values United Bankshares’ future cash flows at $70.26 per share, compared with the current $49.23 price, which implies the stock trades 29.9% below that estimate. Does that gap signal potential valuation upside, or does it reflect overly optimistic cash flow assumptions within the model?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out United Bankshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on valuation and sentiment around United Bankshares can sound compelling on paper, but your own takeaway matters most. Move quickly from curiosity to conviction by weighing these data points against the company’s potential and then check the 3 key rewards
Looking for more investment ideas beyond United Bankshares?
If United Bankshares has sharpened your focus on quality and valuation, broaden your watchlist now so you do not overlook other compelling setups.
- Target resilient cash flows and balance sheet strength by reviewing the 35 high quality undervalued stocks that combine financial quality with prices below implied worth.
- Build a dependable income stream and stress test yields with the 5 dividend fortresses that prioritise higher payout levels supported by fundamentals.
- Tilt your portfolio toward stability and capital preservation by scanning the 31 resilient stocks with low risk scores that screen for resilient financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com