
Can Schneider National (SNDR) Justify Its Valuation On Strong Q3 Results And New Partnership?
Schneider National (SNDR) drew fresh attention after releasing third quarter 2026 results that showed higher sales and earnings, and also announced a new intermodal partnership with Norfolk Southern that targets additional freight opportunities.
Recent price action reflects this mix of stronger earnings and new intermodal initiatives, with Schneider National’s share price up 10.53% year to date but down 16.33% over 90 days. At the same time, the 1 year total shareholder return of 36.32% points to momentum building over a longer horizon.
Scan Schneider National’s peers that combine freight exposure with earnings traction and balance sheet strength by jumping into our curated list of solid balance sheet and fundamentals (24 results) while this intermodal story is in motion.
Schneider National now pairs stronger recent earnings with a fresh intermodal agreement and a 1 year return above 36%. Does that mix still leave enough upside to compensate for the recent 90 day pullback risk?
Most Popular Narrative: 17% Undervalued
At a last close of $29.81 against a widely followed fair value estimate of about $35.86, Schneider National screens as materially cheaper than that narrative view suggests, which is why the underlying drivers matter so much here.
Disciplined capital allocation that includes low net leverage of 0.2x, net CapEx largely focused on fleet replacement in the US$350 million to US$400 million range for 2026, consistent dividends and buybacks, and a track record of accretive Dedicated acquisitions, provides Schneider National with capacity to pursue further earnings accretive M&A and targeted investments that can support revenue growth and cash flow.
See why 6 investors see Schneider National as 17% undervalued.
Result: Fair Value of $35.86 (UNDERVALUED)
Still, Schneider National’s thesis can be challenged if freight demand softens again, or if driver and fuel costs eat into the margin recovery story.
Find out about the key risks to this Schneider National narrative.
Another View: Schneider National Through The P/E Lens
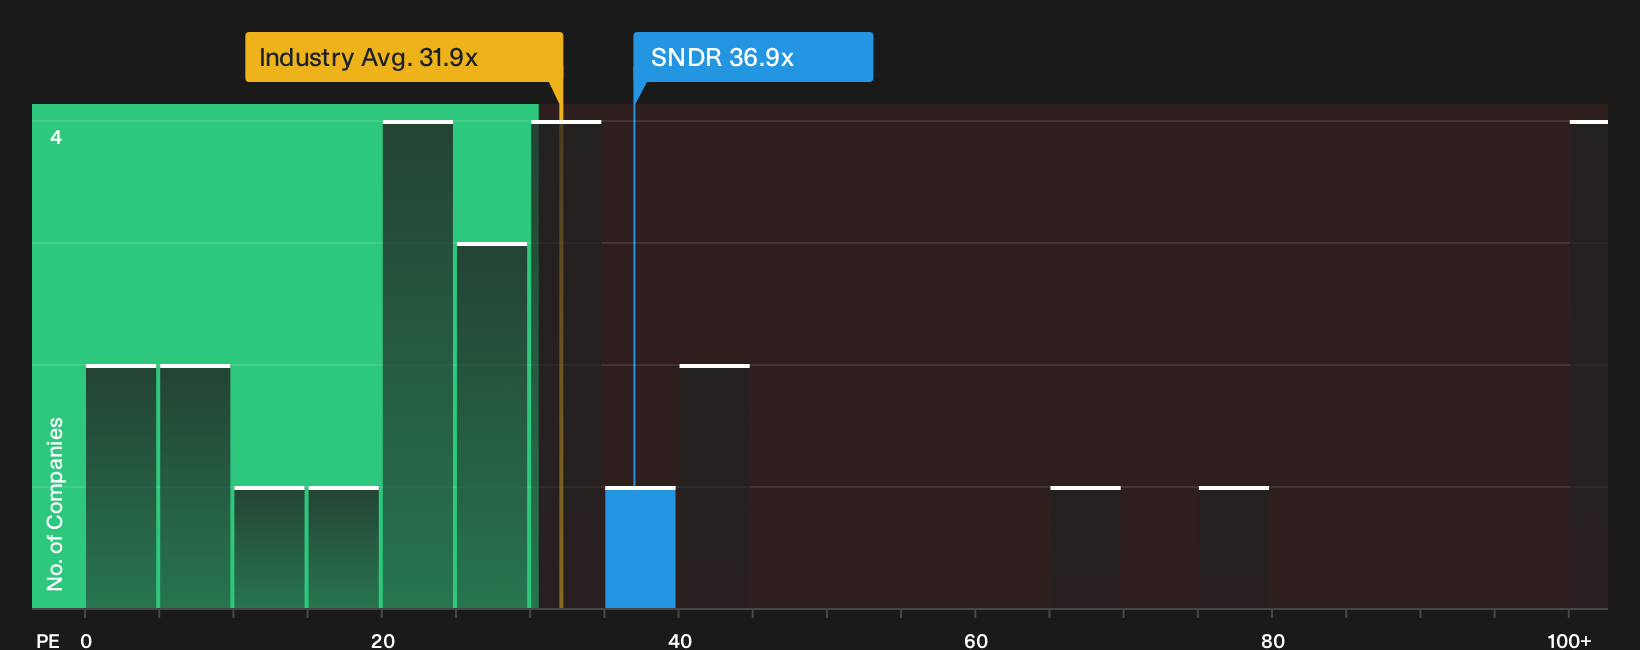
The first fair value story points to upside for Schneider National, yet the current P/E of 36.9x tells a cooler story. That figure sits above both the US Transportation sector at 31.9x and a fair ratio of 33.8x, which hints at some valuation risk if sentiment cools.
For investors who lean on earnings multiples, this gap matters. A P/E above sector and fair ratio levels can mean paying extra for growth and execution that still has to show through. The question is whether you are comfortable underwriting that premium, or whether you prefer situations priced closer to the fair ratio anchor.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals all over Schneider National, so consider using that tension to your advantage and review the underlying data before sentiment shifts again. To see what optimistic investors are focusing on right now, take a closer look at the 3 key rewards.
Looking For More Investment Ideas Beyond Schneider National?
If Schneider National has your attention, do not stop here. Use the Simply Wall St screener to uncover other opportunities that might fit your playbook even better.
- Target potential mispricing early by scanning a curated set of quality companies that look undervalued using the 35 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with healthier finances through the 31 resilient stocks with low risk scores.
- Spot future favourites before the crowd by running a search across the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com