
A record 62 billion euros grabbed new Meta bonds! Behind the popularity of tech giants' equity bonds: risk appetite shifts to high-quality growth
The Zhitong Finance App learned that at a time when the AI computing power infrastructure financing costs are significantly reducing the AI computing power industry chain and the overall valuation of new cloud forces and cloud computing giants, the impressive performance of Facebook and Instagram parent company Meta Platforms Inc. (META.US) recently issued Eurobonds shows that global capital is still willing to finance the long-term growth of high-quality technology companies.
By the close of the US stock market on Wednesday, large tech giants with strong fundamentals for a long time are becoming an important undertaking to fix market risk appetite. What is behind this is the combined effects of the US dollar index, easing discount rate pressure in the context of cooling US bond yields of 10 years or more, adjustments in capital expenditure expectations, and the market's reassessment of the competitive advantage of technology giants in the AI era.
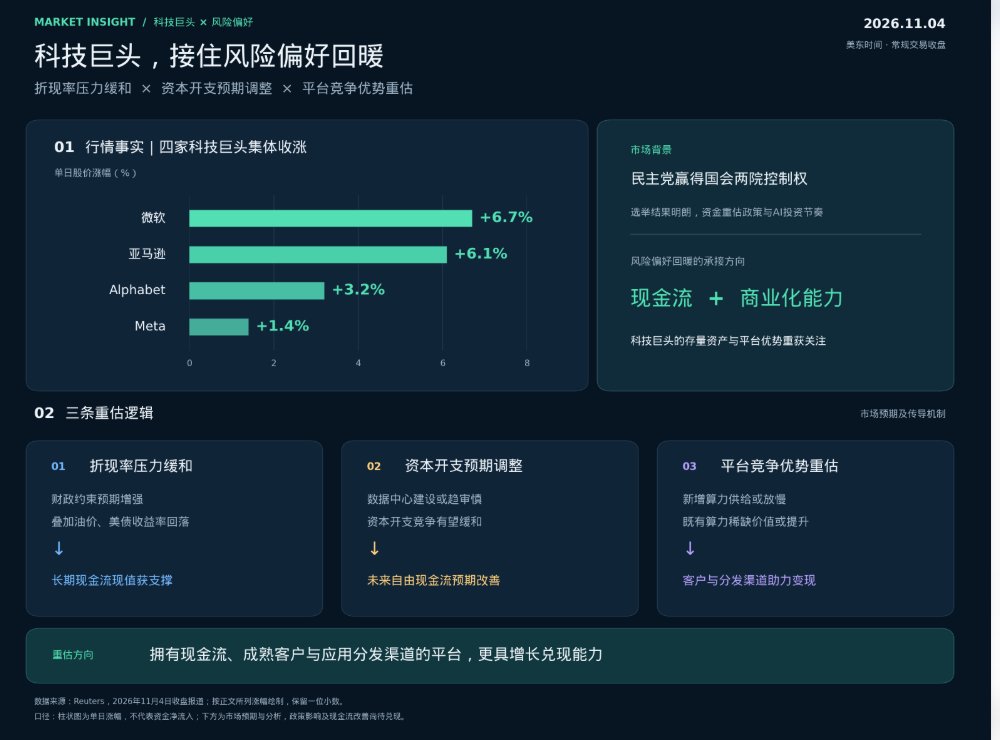
After the Democratic Party gained control of both houses of Congress on November 4, Microsoft, Amazon, Alphabet, and Meta rose 6.7%, 6.1%, 3.2%, and 1.4%, respectively. Expectations that fiscal expansion may be more constrained, compounded by falling oil prices and falling US bond yields, provided important support for global technology stock valuations.
At the same time, the market is beginning to trade another layer of bullish logic and the classic fundamental narrative under the AI wave: if the pace of data center construction tends to be cautious, it may ease the pressure on giants to continue to increase capital expenditure and increase the scarce value of existing computing power infrastructure. Large technology giants such as Meta and Microsoft, which have mature customer systems, application distribution channels, and abundant operating cash flow, are therefore in a better position to turn their stock computing power into revenue and profit, and attract capital to re-evaluate their long-term growth value.
According to the latest bond market statistics, the price of Eurobonds newly issued by Meta Platforms is already significantly higher than face value. Just during the European market trading session on Wednesday, the issuance attracted investor subscription orders, which set a record for issuing corporate bonds in the entire European market.
According to a series of data compiled by Bloomberg Intelligence, the indicative bond market prices for all six batches of bonds issued by Meta this time rose sharply higher on Thursday, and even the purchase price — that is, the price at which traders are willing to buy the bonds — was higher than face value. Large investment banks responsible for arranging the 9 billion euro (about 10.1 billion US dollars) issuance transaction on Wednesday. At the time of issuance, they generally set the issuance price of each batch of bonds at a level of slightly less than 100 euro cents per euro in face value.
Prior to this price increase, Meta had already completed a record bond issuance, with subscription orders reaching 62 billion euros, far exceeding the 31 billion euro bond market capital subscription record set by Budweiser InBev ten years ago. Subscription orders are increasing because the interest spreads offered by this offering are much higher than those offered by other hyperscale technology companies that have issued Eurobonds, and closer to those offered by bonds with credit ratings several levels lower than Meta's AA rating.
When Meta and other hyperscale tech companies recently issued bonds, they have offered attractive yields to attract investors who are increasingly skeptical about whether huge AI spending can achieve continued strong cash returns. Although investors are actively subscribing to the bonds issued by Meta this time, they are becoming increasingly picky about AI-related bonds as a whole, especially those issued by highly leveraged new cloud technology companies and technology companies with continuous negative cash flow.
Today's indicative price of Eurobonds issued by Google's parent company Alphabet Inc. on Monday was also higher than the face value as recently compiled by Bloomberg Intelligence.
At a time when AI financing costs are high, the 62 billion euro subscription scale voted for tech giants
Meta Eurobonds were subscribed for 62 billion euros, and all six batches were worth on the first day of listing, providing credit market support for this risk appetite correction. The 9 billion euro issuance corresponds to about 6.9 times the subscription, which not only reflects the appeal of higher issuance spreads, but also shows that global investors are still willing to bear long-term credit risk for high-quality technology giants; the Eurobonds issued by Alphabet during the same period also received higher than face value quotes, further highlighting the strong AI financing capacity of large technology platforms.
Judging from the specific capital rotation behind it and the investment mechanism under heightened risk appetite, stable demand for bonds means that financing channels remain smooth, while a rational pace of construction may improve future free cash flow expectations. Together, the two enhance the ability of tech giants to get through the current AI investment cycle.
What can be seen from this is that the current recovery in risk appetite has a clear quality orientation — global capital has begun to refocus on platform companies that can continue financing, effectively deploy computing power, and turn AI needs into commercial returns. As a result, large technology giants such as Microsoft, Meta, and Google's parent company Alphabet, Tencent, and Ali have become an important observation window for this round of valuation repairs.
This is why, according to analysts who have been optimistic about tech giants for a long time, there is no contradiction between Meta's 9 billion euro bond subscription scale, which is about 6.9 times the amount issued by AI computing power, semiconductors, and Xinyun: as 10-year US bond yields and AI financing costs continue to rise to historic highs after experiencing a surge, investors are re-distinguishing between companies that rely on external financing to continue to expand, and platform giants with huge operating cash flows, mature business models, and diversified financing channels. The high issuance spread granted by Meta attracted capital, and the price increase after listing further showed that the pricing of this batch of bonds was accepted by the market.
This divergence also occurred amid a rare sharp adjustment in global technology assets: the NASDAQ 100 index has entered a technical correction range, and the Philadelphia Semiconductor Index has fallen by about 25% in the past month, falling into a bear market. South Korea's KOSPI index fell 16.19% in October, then fell 5.3% on November 5. Samsung Electronics and SK Hynix fell 7.6% and 9.4% respectively on the same day, indicating that the sell-off of memory chips has reached deep into the core of the AI computing power infrastructure construction process. Google's parent company Alphabet had a sharp drop of 12.6% on October 29, and Intel fell nearly 29% the next day, the worst single-day performance since 1974
From financing anxiety to cash flow stratification, Wall Street is looking for a new fulcrum in the context of tech stock restoration
The recent selling pressure on AI Xinyun leader CoreWeave (CRWV.US), which is at the core of the “AI computing power sell-off storm” and the “AI bubble bursting argument”, has recently been under more direct selling pressure: the stock price fell 9.90% to close at $48.42 on November 4. The yield on its 2031 dollar bond maturing surpassed 16% on October 15; on the same day, the five-year CDS rose to 1,194.5 basis points in the intraday market, corresponding to the implied five-year cumulative default probability of more than 60% in the market. This probability includes a risk premium and is not a direct prediction of the actual rate of default.
For new cloud enterprises, equipment procurement, interest, and construction expenses come first, after delivery of computing power and customer repayment; delays in approval, electricity access, or deployment will widen the funding gap, while high benchmark interest rates and credit spreads further increase the cost of new financing and refinancing. Large platforms are also affected by rising financing costs, but their existing business cash flow and financing channels make credit risk clearly different from highly leveraged new clouds.
The Democratic Party won control of Congress and brought the pace of data center construction into pricing. The market is concerned about stricter restrictions on approval, energy, and construction, but this is currently mainly a policy expectation, and cannot be directly equated with completely restricting AI construction. On November 4, the Philadelphia Semiconductor Index fell 3.1%, but the S&P 500 index rose about 1.6%. Amazon and Alphabet rose 6.1% and 3.2% respectively: suppliers faced the risk of delays in order fulfillment, while platform companies may benefit from capital expenditure constraints, scarce computing power, and a more rational pace of investment.
Meanwhile, fiscal restraint expectations and cooling inflation expectations drove the 10-year US Treasury yield back to 4.891% from 4.951% the previous day. As a result, the pressure created by high financing costs is still there, but marginal changes after the election have begun to facilitate the restoration of valuations of high-quality technology assets.
Wall Street attitudes are also changing. Deutsche Bank is once again bullish on US technology stocks, believing that recent adjustments have been excessive, valuations and positions have cooled down, while profit growth is still resilient; Mike Wilson, chief US stock strategist at Morgan Stanley, believes that this round of adjustments is nearing its end, focusing on high-quality companies whose valuations have declined and profits are highly sustainable. The opportunity they both point to is a rematch between adjusted prices and the quality of long-term business growth, rather than a simultaneous rebound of all AI assets.
Pershing Plaza, where Ackman is at the helm, further pointed out in the latest shareholder letter that the market may prolong huge AI capital expenses, but the subsequent revenue acceleration brought about by these investments is not fully taken into account; customer relationships, data, distribution channels, and commercialization capabilities of large technology companies make it easier to transform additional computing power into fee-based services. Ackman's latest judgment was supported by strong AI-related cloud computing business growth: Amazon's AWS revenue increased 39.3% in the third quarter, and Alphabet's Google Cloud revenue increased 103%. The latter included significant TPU system sales contributions. The popularity of Meta bonds adds a part of financing to this bullish logic: when revenue growth, availability of financing, and return on investment are gradually linked, high-quality platforms have the foundation to move from valuation compression to revaluation.