
Modine Manufacturing (MOD) After The Earnings Miss And Spin Off Looks Cheap On Fair Value
Modine Manufacturing (MOD) is back in focus after quarterly results that missed earnings per share estimates but topped revenue forecasts, accompanied by an upbeat outlook tied to its recent Performance Technologies spin-off.
The latest earnings miss and updated outlook landed alongside a sharp reset in expectations, with the 1-day share price return down 21.43% and the 30-day share price return down 46.12%, even though the 5-year total shareholder return is very large. Recent weakness suggests momentum has faded in the short term as investors weigh softer near term earnings against Modine Manufacturing's longer run track record and the potential impact of the Performance Technologies spin off on future growth and risk.
Spot fresh ideas around Modine Manufacturing's recent reset by scanning a curated group of industrial and infrastructure names in the 41 power grid technology and infrastructure stocks.After a surge over the past few years and a steep reset in recent weeks, Modine Manufacturing now sits at a crossroads. Has most of the easy upside already played out, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 66% Undervalued
On the narrative view, Modine Manufacturing’s fair value of about $290.78 sits far above the last close at $98.56. This puts the recent share price slide against a still bullish long term earnings story built around data center and climate focused cooling.
The accelerating build out of data centers and the need for next generation cooling solutions are driving demand for Modine Manufacturing’s products, with management targeting data center revenue of about US$2b by fiscal 2028 after delivering US$1.1b in fiscal 2026 and guiding to 60% to 80% Data Center sales growth in fiscal 2027, which points to a significant revenue growth engine and potential operating leverage as new capacity fills.
See why 58 investors see Modine Manufacturing as 66% undervalued.
The most followed narrative values Modine Manufacturing using an 8.6% discount rate and ties that valuation to analyst forecasts that point to revenue of $4.9b and earnings of $696.9m by about 2029, with a future P/E of 29.1x implied by the current analyst price target. That framework links the current $98.56 price and the very large 5 year total return to a story where earnings are expected to grow 42.72% per year from a $144.2m base, margins are modeled to rise from 4.3% to 14.3%, and the business mix tilts further toward higher margin climate and data center solutions after the Performance Technologies spin off.
The same storyline does not ignore pressure points. Net profit margin has already slipped from 7.2% to 4.3%, earnings over the past year declined 23.3%, and management has had to contend with supply chain constraints that hit data center gross margin and forced resequencing of capacity ramps. All of this feeds into the higher 8.6% required return used in the model. Yet the narrative still treats issues like the $145.1m one off loss, recent share price volatility, and lower near term profitability as timing and execution risks around a longer term shift toward climate focused cooling where earnings quality is expected to improve.
On that basis, the gap between the modeled fair value of roughly $290.78 and the current price, along with the 188.8% upside implied by analyst targets and the SWS DCF estimate of $303.96 per share, is framed less as a simple multiple rerating and more as a question of whether Modine Manufacturing can convert its order book, large data center capacity agreements, and Performance Technologies separation into the higher returns on equity and margin profile that the narrative assumes.
Result: Fair Value of $290.78 (UNDERVALUED)
Still, the upbeat Modine Manufacturing narrative leans heavily on supply chains improving and on large data center capacity agreements holding their pricing power rather than squeezing margins.
Find out about the key risks to this Modine Manufacturing narrative.
Another View: What Multiples Say About Modine Manufacturing
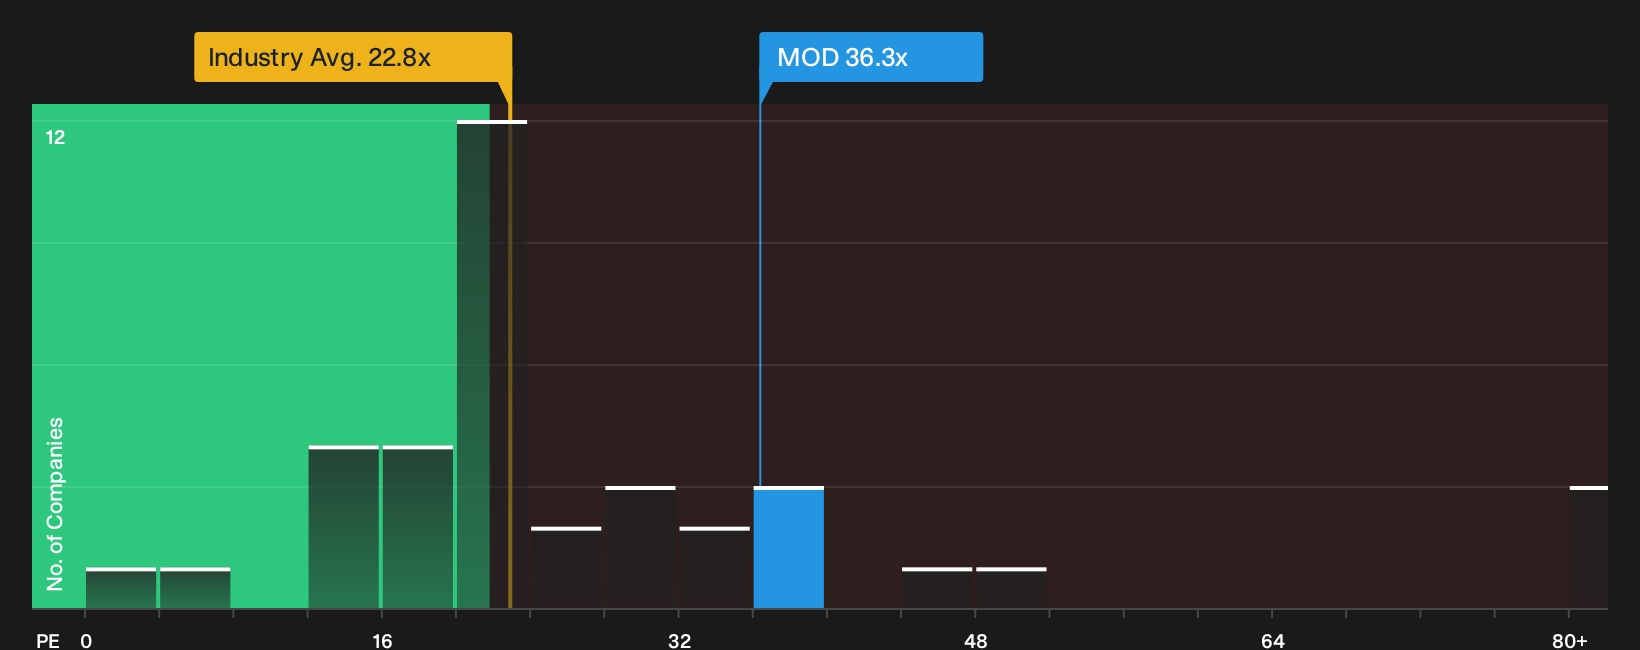
The story from earnings models presents Modine Manufacturing as materially undervalued, yet the market is not pricing it like a bargain on simple ratios. The stock trades on a P/E of 36.3x, which is richer than the US Building industry at 22.8x and above the 25.2x peer average, although still below a fair ratio of 52.1x implied by Simply Wall St's work. That mix of premium versus sector but discount to the fair ratio leaves you deciding whether this is justified quality or valuation risk that could compress.
To stress test that gap and see how the earnings multiple story compares with detailed cash flow work, it helps to dig into the full valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
For a clearer picture of how Modine Manufacturing’s current pricing compares to the wider market on this metric, take a close look at the
Next Steps
If this mix of optimism and concern around Modine Manufacturing feels familiar, take a moment now to test the story against the data yourself and see both sides of the argument with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Modine Manufacturing?
If Modine Manufacturing has sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist with a few targeted filters that surface very different kinds of opportunities.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (24 results) before conditions change and quality gets priced richer.
- Hunt for mispriced quality by running a 35 high quality undervalued stocks that highlights companies where fundamentals and market expectations tell very different stories.
- Spot potential future leaders early by filtering for a 19 high quality undiscovered gems that surfaces under-the-radar businesses with numbers worth a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com