
Select Water Solutions (WTTR) Could Be 31% Undervalued After Its Dividend Declaration
Select Water Solutions (WTTR) set a fresh marker for income focused investors after its board declared a quarterly cash dividend of $0.07 per Class A share, payable November 25, 2026.
Recent trading has been rough for Select Water Solutions, with the share price down 7.85% over the last session and 18.36% over 90 days, even after a strong year to date share price return of 52.39% and a 1 year total shareholder return of 50.11%. Near term momentum looks weak, while longer term performance, including a 3 year total shareholder return of over 150%, still reflects a materially stronger run for patient holders.
Scan income focused opportunities similar to Select Water Solutions by running the curated 5 dividend fortresses for ideas that combine cash payouts with more resilient balance sheets.
Select Water Solutions now splits investors. One side sees a high yielding water infrastructure play that has already rewarded patience; the other sees a stock losing steam. Which case does the current valuation lean toward?
Most Popular Narrative: 31% Undervalued
On the most followed narrative, Select Water Solutions screens as undervalued, with a fair value estimate of $24.57 against a last close of $16.90. That gap rests on the idea that long term water networks and recycling contracts can turn today’s infrastructure buildout into a more recurring earnings base.
The substantial and growing backlog of long term, acreage dedicated water infrastructure contracts in the Northern Delaware Basin remains in place, with recent agreements adding 256,000 newly dedicated acres and converting 104,000 ROFR acres, which can increase Select Water Solutions’ contracted revenue base and earnings visibility as these projects are built out and start contributing.
Ongoing transfer of customer owned recycling and disposal assets into Select Water Solutions’ integrated networks, including 14 underutilized saltwater disposal wells conveyed in a recent Northern Delaware contract, creates room for higher utilization and operating leverage that can lift consolidated net margins as volumes move through existing infrastructure.
See why 16 investors see Select Water Solutions as 31% undervalued.
Result: Fair Value of $24.57 (UNDERVALUED)
Still, the bullish Select Water Solutions story can unravel if heavy 2026 capex restrains free cash flow, or if tighter disposal well rules hit water volumes and earnings.
Find out about the key risks to this Select Water Solutions narrative.
Another View: What Multiples Say About Select Water Solutions
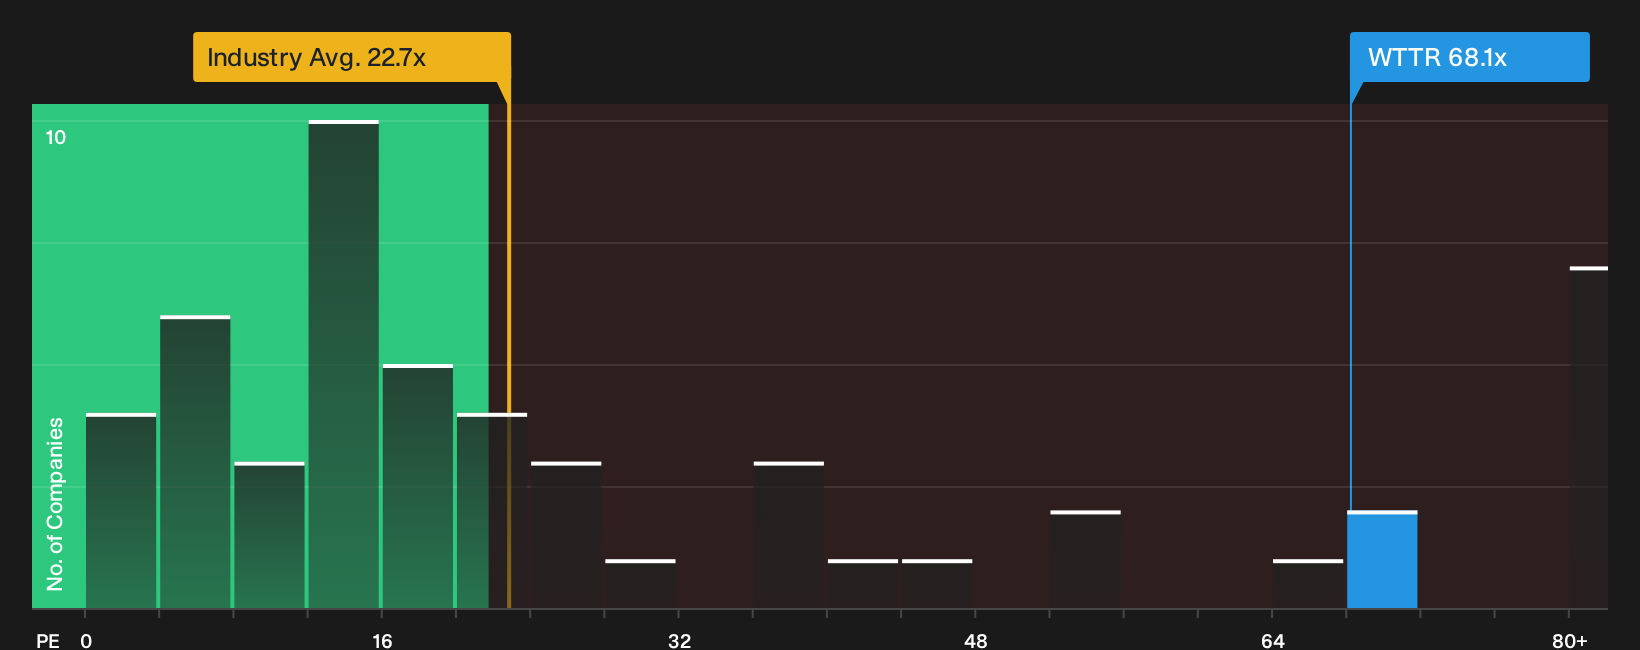
On simple valuation multiples, Select Water Solutions looks far less forgiving. The stock trades on a P/E of 68.1x, compared with 22.7x for the US Energy Services industry and a fair ratio estimate of 26x. That gap leaves little room if expectations cool or earnings timing slips.
For investors weighing this against the earlier fair value estimate, the question becomes how comfortable you are owning a business where optimism is already built into the earnings multiple. It also raises whether that premium is one you genuinely want to pay at today’s price or whether it is preferable to wait for a different entry point.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Select Water Solutions so far. If you want a sharper view before the market moves on, review the 3 key rewards and 2 important warning signs for yourself.
Looking for more investment ideas beyond Select Water Solutions?
If you only stop at Select Water Solutions, you risk missing out on other opportunities that better match your income goals, risk appetite, and time horizon.
- Target sharper value by reviewing the 35 high quality undervalued stocks, which filters for companies combining quality fundamentals with prices that may not fully reflect their financial strength.
- Prioritise resilience by scanning the list of solid balance sheet and fundamentals (24 results), focused on businesses with sturdier financial footing that can help anchor a diversified portfolio.
- Hunt for overlooked potential through the 19 high quality undiscovered gems and see which lesser known stocks align with the kind of long term story you want to own.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com