
Learn Why The Bull Case For Teva Pharmaceutical Industries (TEVA) Could Change Following Raised Revenue Guidance
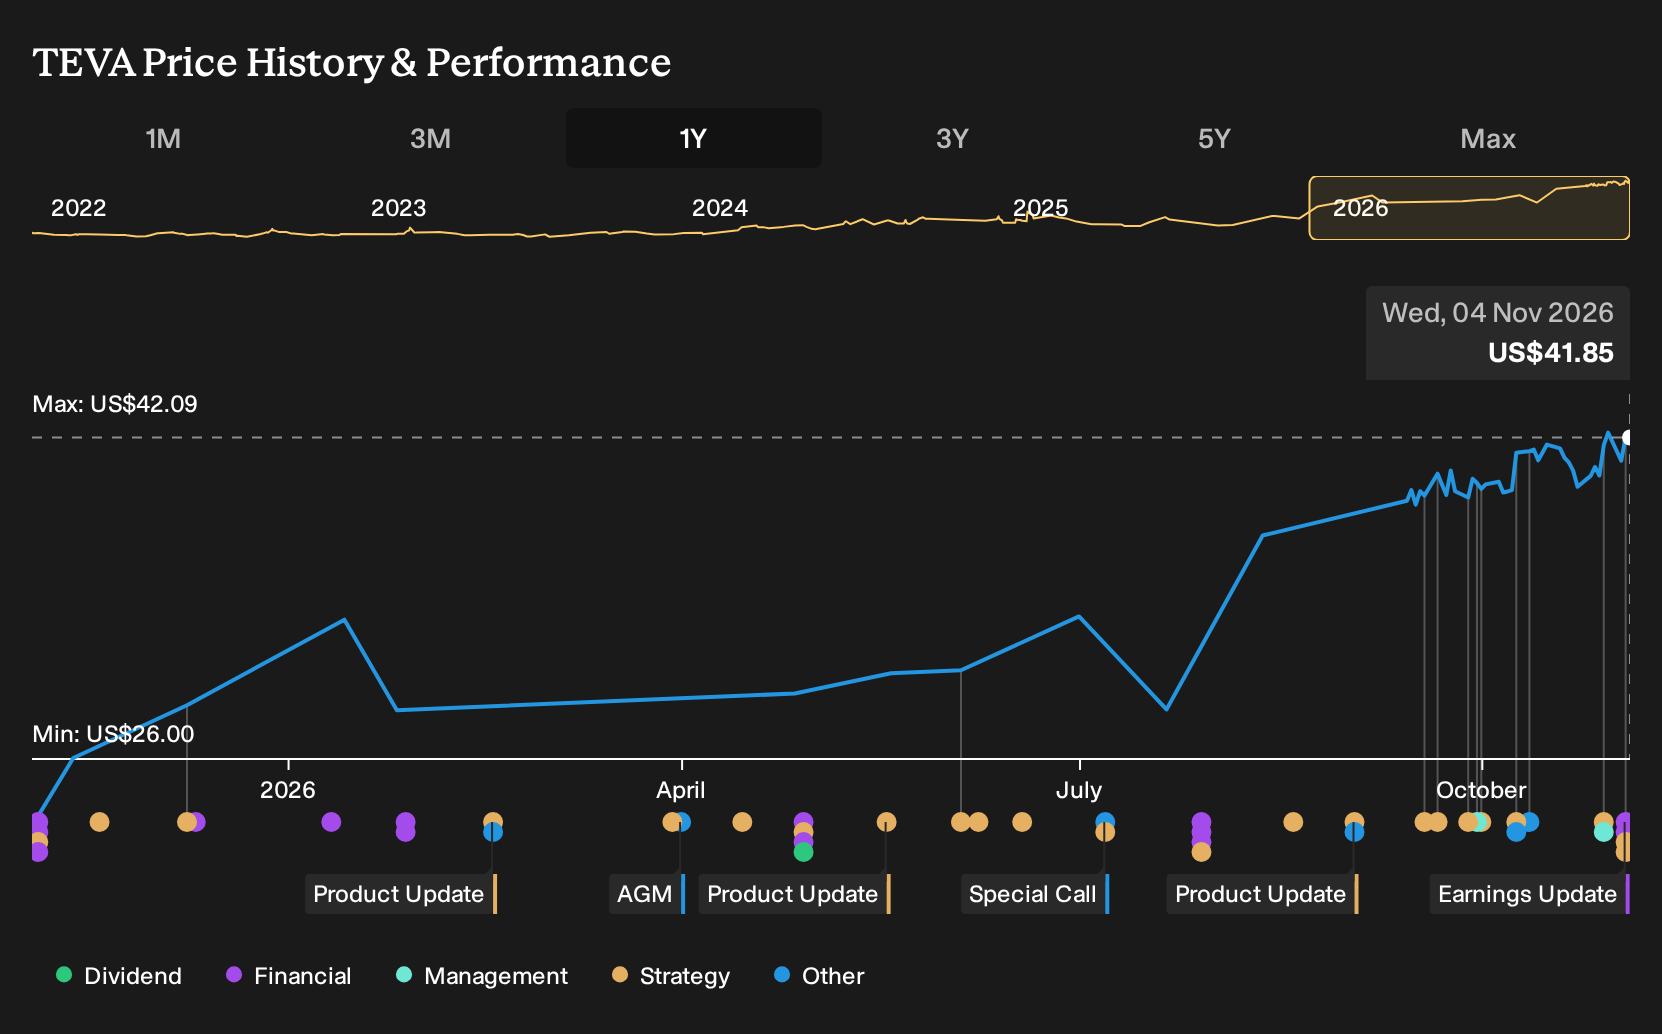
- Teva Pharmaceutical Industries reported Q3 2026 sales of US$4.4b with earnings above analyst estimates, raised its 2026 revenue outlook to a range of US$16.7b to US$17.0b, and disclosed higher long lived asset impairment charges alongside lower net income year on year.
- The business is focusing more on higher margin products, with strong branded drug growth, an expanded biosimilars deal with Samsung Bioepis, and new schizophrenia treatments such as Weltruza and UZEDY reshaping Teva Pharmaceutical Industries product mix.
- This article will now examine how Teva Pharmaceutical Industries investment narrative could be influenced by stronger branded drug momentum and raised guidance.
Scan how Teva Pharmaceutical Industries' branded drug momentum compares with peers by reviewing our hand picked 38 healthcare AI stocks that are capitalizing on the same push toward higher margin treatments.
What Is Teva Pharmaceutical Industries' Investment Narrative?
For Teva Pharmaceutical Industries, the long term story you would need to buy into is pretty simple. The business keeps shifting more weight toward higher margin branded products and biosimilars while using the generics engine and cash flow to fund that pivot. The latest quarter fits that script. Adjusted earnings and branded drug sales were strong enough for management to lift 2026 revenue guidance to US$16.7b to US$17.0b, even though reported Q3 net income of US$233 million and higher long lived asset impairments show the accounting picture is still messy.
In the short term, the key swing factors are execution on launches like Weltruza and UZEDY, pricing and volume in the generics portfolio, and how capital hungry the biosimilar build out becomes. Raised guidance and the Samsung Bioepis deal suggest management sees enough demand and operational traction to support the current plan. However, rising impairment charges, thinner net margins at 2.9%, and debt that is not well covered by operating cash flow keep financial risk front and center.
Even so, the stronger story around Teva Pharmaceutical Industries has to sit beside one uncomfortable funding issue that...
There's only one way to know the right time to buy, sell or hold Teva Pharmaceutical Industries. Head to Simply Wall St's company report for the latest analysis of Teva Pharmaceutical Industries's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community only has two fair value estimates for Teva Pharmaceutical Industries, yet they already span from about US$48.9 to US$67.1 per share. That gap shows how far opinions can stretch before the latest earnings beat, raised 2026 guidance and fresh biosimilar deals are even factored in. Use those contrasting views as a starting point, and explore several alternative angles before deciding where you sit.
Explore another Teva Pharmaceutical Industries fair value estimate, including one that suggests it could be worth just $48.94.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Teva Pharmaceutical Industries research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Teva Pharmaceutical Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teva Pharmaceutical Industries' overall financial health at a glance.
Looking For More Ideas Beyond Teva Pharmaceutical Industries?
If you want to cross check Teva Pharmaceutical Industries against other opportunities, broaden your watchlist with a few focused stock shortlists built from the same data driven process behind this analysis.
- For investors who care most about resilient balance sheets and solid fundamentals, review the list of solid balance sheet and fundamentals (24 results) that can help you stress test your portfolio quality.
- If you are hunting for companies that combine quality metrics with pricing that may look appealing on several checks, scan the 35 high quality undervalued stocks to see what else matches your filters.
- When capital preservation and smoother rides matter more than headline growth, consider broadening your watchlist with the 31 resilient stocks with low risk scores that filters for businesses exhibiting lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com