
Is NatWest Group (LSE:NWG) A Bargain As Earnings And Buybacks Lift Optimism?
NatWest Group (LSE:NWG) just wrapped up a busy 30 October, pairing third quarter earnings with an update on its ongoing share buyback. Both announcements give investors fresh numbers to assess the bank today.
NatWest Group’s recent updates landed against a choppy backdrop, with the 1-day share price return of 5.34% partly offsetting a 30-day share price return that is down 7.90% and a 90-day share price return that is down 14.16%. At the same time, the 1-year total shareholder return of 9.98% and a very large 5-year total shareholder return of about 3.8x highlight that longer term holders have still seen strong gains despite more recent momentum fading.
Scan beyond NatWest Group and explore other banks and financials that screen well on quality and value with the hand picked 14 high quality undervalued stocks already filtered for you.
NatWest Group now looks like a robust, profitable bank that is directing meaningful cash to buybacks after a strong multi year run. The real tension for investors is whether that quality is already fully priced in.
Most Popular Narrative: 23% Undervalued
Against a last close of £6.11, the most followed narrative on NatWest Group points to a fair value of £7.98 and relies on specific growth, efficiency and capital return assumptions to reach that figure.
Continued strong capital generation of 137 basis points of CET1 in the first half of 2026 after funding £17b of organic loan growth and the £2.7b Evelyn transaction, combined with existing guidance for a 50% payout ratio and ongoing buybacks, is cited as creating scope for higher earnings per share even if headline profits are stable.
See why 128 investors see NatWest Group as 23% undervalued.
Result: Fair Value of £7.98 (UNDERVALUED)
Still, the NatWest Group story can break if net interest margins flatten while loan growth outpaces deposits, and political moves on UK bank taxes bite harder than expected.
Find out about the key risks to this NatWest Group narrative.
Another View: What NatWest Group’s P/E Is Really Saying
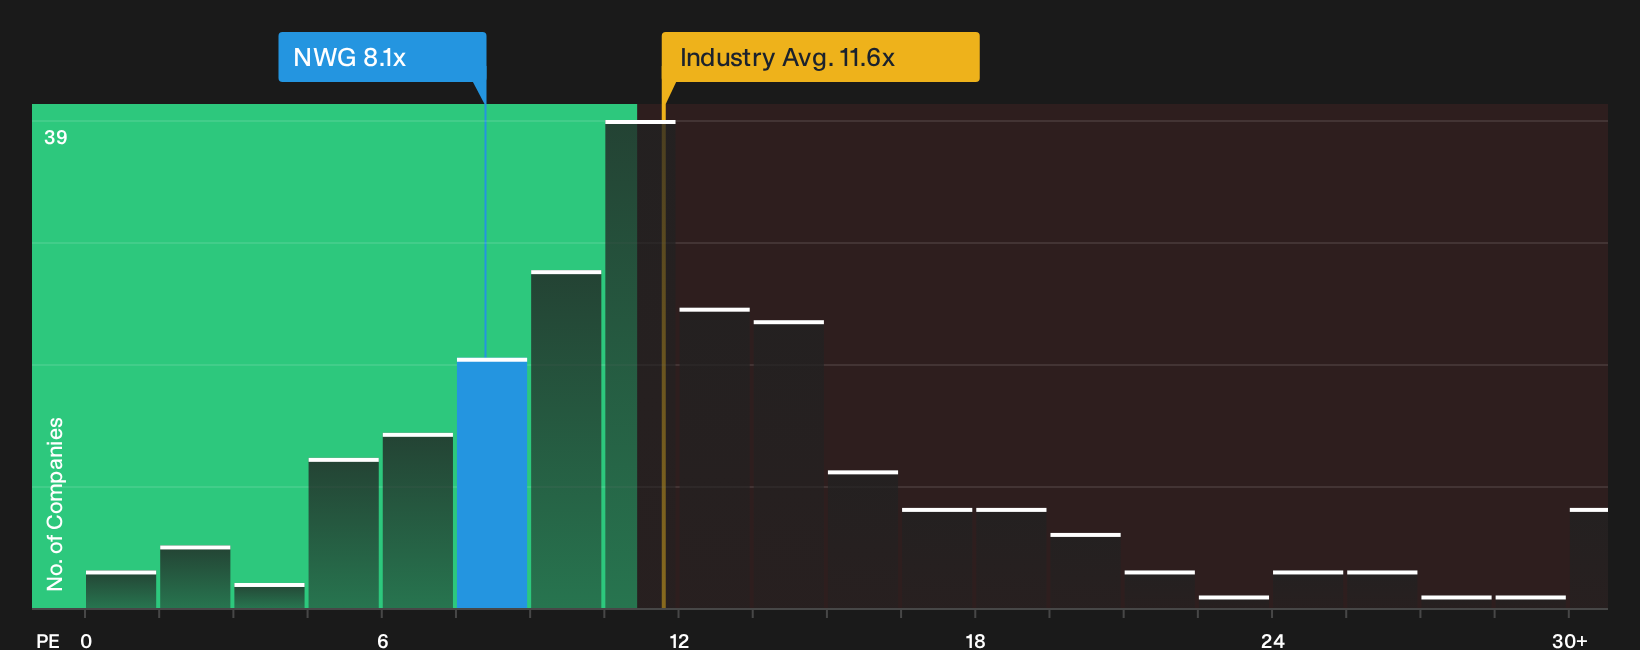
Fair value models paint NatWest Group as heavily undervalued, yet the P/E picture is more cautious. The shares trade on 8.1x earnings, slightly above a fair ratio of 7.9x. This points to a modest valuation premium rather than a clear-cut bargain. So is the gap a warning sign or simply the cost of quality?
Our P/E comparison adds more colour. NatWest Group trades below peers on 10.3x and the wider European banks group on 11.6x. This hints at some relative value even if the fair ratio suggests limited room for a re rating. The question is whether you believe the market drifts toward the cheaper peer pack or closer to that 7.9x fair ratio over time.
See what the numbers say about this price in the valuation breakdown, then decide which signal you trust most, the cash flow model or the earnings multiple, by using the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals or a clear opportunity: the NatWest Group picture will only really make sense once you have walked through the data yourself and weighed both sides. Move quickly and review the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond NatWest Group?
If NatWest Group is already on your radar, broaden your watchlist with other focused ideas that match different goals, risk levels and income needs.
- Target resilient income by reviewing companies in the 4 dividend fortresses that may appeal if you want yield backed by stronger financial profiles.
- Hunt for potential mispriced opportunities using the 5 high quality undiscovered gems where solid fundamentals meet lower market attention.
- Dial down risk and stress test your portfolio against shocks by filtering for the 5 resilient stocks with low risk scores before capital moves elsewhere.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com