
We're Keeping An Eye On Century Therapeutics' (NASDAQ:IPSC) Cash Burn Rate
There's no doubt that money can be made by owning shares of unprofitable businesses. By way of example, Century Therapeutics (NASDAQ:IPSC) has seen its share price rise 198% over the last year, delighting many shareholders. But while history lauds those rare successes, those that fail are often forgotten; who remembers Pets.com?
In light of its strong share price run, we think now is a good time to investigate how risky Century Therapeutics' cash burn is. For the purposes of this article, cash burn is the annual rate at which an unprofitable company spends cash to fund its growth; its negative free cash flow. We'll start by comparing its cash burn with its cash reserves in order to calculate its cash runway.
How Long Is Century Therapeutics' Cash Runway?
A company's cash runway is calculated by dividing its cash hoard by its cash burn. In June 2026, Century Therapeutics had US$120m in cash, and was debt-free. Importantly, its cash burn was US$88m over the trailing twelve months. That means it had a cash runway of around 16 months as of June 2026. While that cash runway isn't too concerning, sensible holders would be peering into the distance, and considering what happens if the company runs out of cash. Depicted below, you can see how its cash holdings have changed over time.
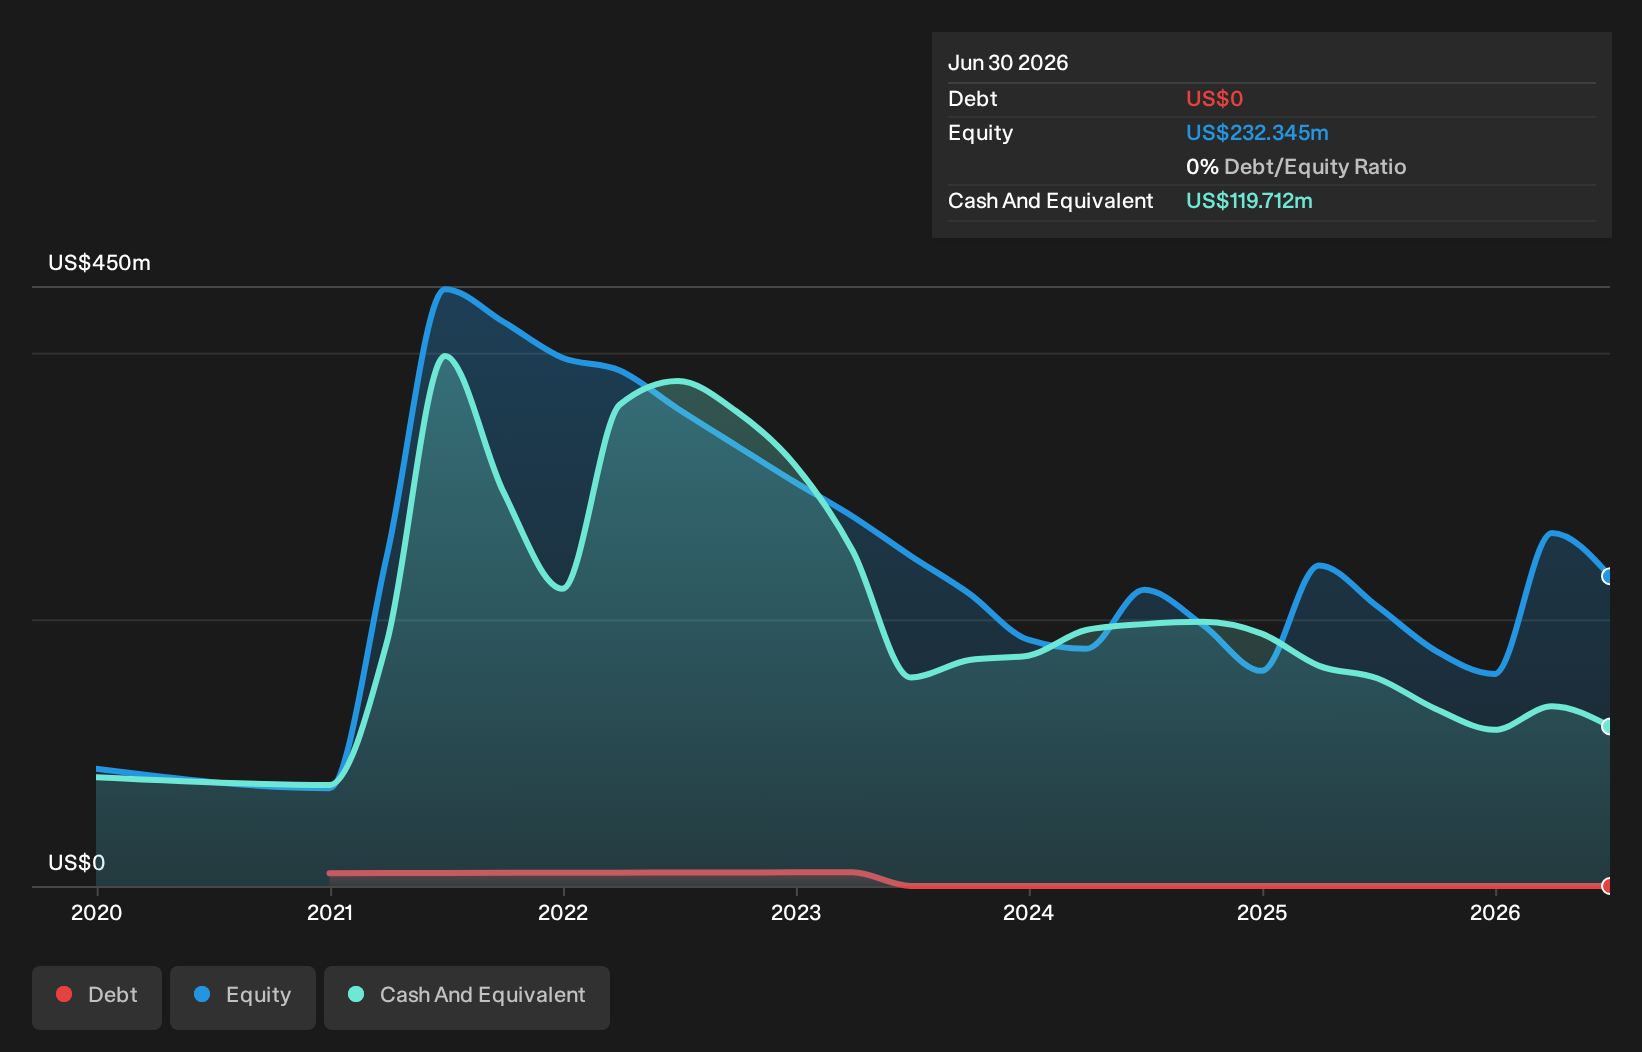
Check out our latest analysis for Century Therapeutics
How Is Century Therapeutics' Cash Burn Changing Over Time?
Century Therapeutics didn't record any revenue over the last year, indicating that it's an early stage company still developing its business. So while we can't look to sales to understand growth, we can look at how the cash burn is changing to understand how expenditure is trending over time. Even though it doesn't get us excited, the 23% reduction in cash burn year on year does suggest the company can continue operating for quite some time. Clearly, however, the crucial factor is whether the company will grow its business going forward. For that reason, it makes a lot of sense to take a look at our analyst forecasts for the company.
How Hard Would It Be For Century Therapeutics To Raise More Cash For Growth?
While Century Therapeutics is showing a solid reduction in its cash burn, it's still worth considering how easily it could raise more cash, even just to fuel faster growth. Companies can raise capital through either debt or equity. Commonly, a business will sell new shares in itself to raise cash and drive growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Century Therapeutics' cash burn of US$88m is about 32% of its US$275m market capitalisation. That's not insignificant, and if the company had to sell enough shares to fund another year's growth at the current share price, you'd likely witness fairly costly dilution.
How Risky Is Century Therapeutics' Cash Burn Situation?
Even though its cash burn relative to its market cap makes us a little nervous, we are compelled to mention that we thought Century Therapeutics' cash burn reduction was relatively promising. We don't think its cash burn is particularly problematic, but after considering the range of factors in this article, we do think shareholders should be monitoring how it changes over time. On another note, Century Therapeutics has 5 warning signs (and 3 which don't sit too well with us) we think you should know about.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.