
Arcutis Biotherapeutics (ARQT) Returns To Profit, Is The Premium Already Priced In?
Arcutis Biotherapeutics (ARQT) is back in focus after its latest quarterly report, with third quarter 2026 revenue of US$143.92 million and net income of US$8.8 million from continuing operations.
Recent trading has echoed those headline numbers. Arcutis Biotherapeutics’ 1 month share price return of 42.35% and 90 day share price return of 34.64% suggest momentum has been building into and around the earnings release, while the 1 year total shareholder return of 35.66% and very large 3 year total shareholder return signal that investors have already seen substantial gains as sentiment toward the business has shifted with improving profitability.
Scan how Arcutis Biotherapeutics fits alongside other potential breakout ideas with the carefully filtered 19 high quality undiscovered gems, which share strong fundamentals and remain off many investors’ radar.
After a move like Arcutis Biotherapeutics just logged, the tension shifts to timing. Is it worth stepping in after the jump, or does waiting for a calmer entry make more sense once valuation is on the table?
Preferred Price-to-Sales Multiple of 9.2x: Is it justified?
On valuation, Arcutis Biotherapeutics sits on a P/S ratio of 9.2x, and the last close at $34.05 reflects that investors are paying a premium to revenue compared with some peers.
P/S compares the company’s market value to its annual sales. For a biopharma group like Arcutis Biotherapeutics it often serves as a shorthand for how much investors are willing to pay today for each dollar of current top line while the earnings story is still maturing.
The stock looks expensive versus the peer group average P/S of 6.4x. This implies the market is placing a higher value on its dermatology portfolio and forecast earnings profile than on similar businesses. The fair P/S ratio estimate of 9x is slightly lower than the current 9.2x, which suggests the market price is already leaning ahead of that regression-based level and could eventually drift closer to it if sentiment cools.
Explore the SWS fair ratio for Arcutis Biotherapeutics.
Result: Price-to-sales of 9.2x (OVERVALUED)
Still, the story around Arcutis Biotherapeutics can change quickly if dermatology sales underwhelm expectations or if fresh clinical data undercuts confidence in its pipeline.
Find out about the key risks to this Arcutis Biotherapeutics narrative.
Another View on Arcutis Biotherapeutics: DCF Paints a Different Picture
The earlier P/S workup pointed to a rich tag for Arcutis Biotherapeutics, yet the SWS DCF model tells a different story. With the shares at $34.05 and an estimated future cash flow value of $91.44, this framework suggests the stock is trading at a materially lower level than that valuation. Which lens do you rely on more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
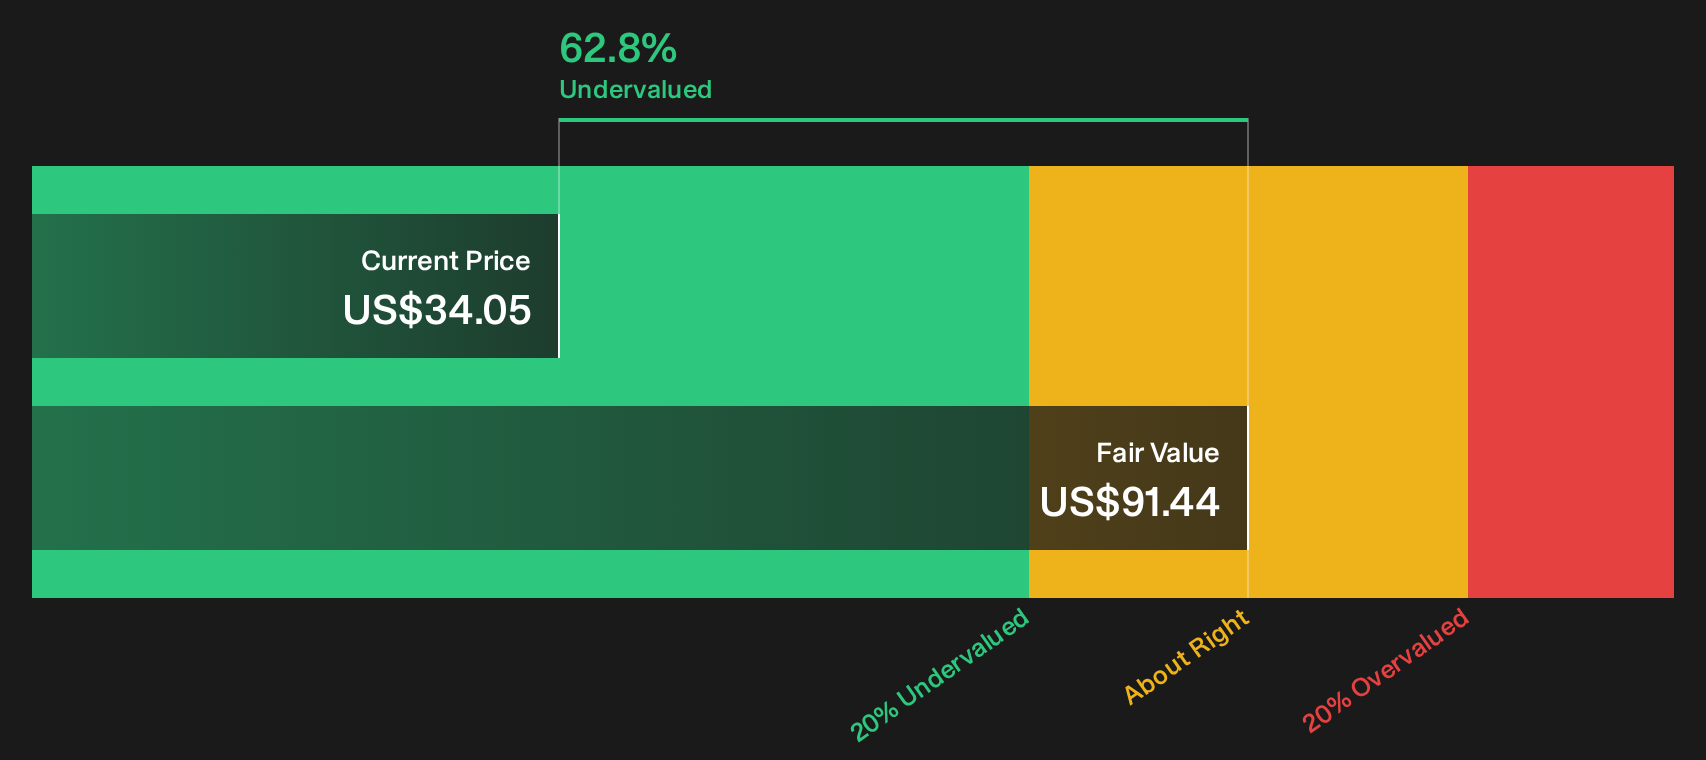
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Arcutis Biotherapeutics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Arcutis Biotherapeutics is clearly upbeat, so move quickly, pull up the same data, and stress test the thesis against your own risk tolerance. To see why some investors are optimistic, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Arcutis Biotherapeutics?
If you want to keep building an edge, do not stop your research with Arcutis Biotherapeutics. Use focused stock lists to quickly surface candidates that fit your own risk profile, income needs, and valuation discipline.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) that meet strict financial health checks.
- Hunt for potential value opportunities by reviewing the 35 high quality undervalued stocks that combine quality metrics with appealing pricing.
- Prioritize capital preservation by filtering through the 31 resilient stocks with low risk scores that score well on downside and volatility measures.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com