
Learn Why The Bull Case For Omega Healthcare Investors (OHI) Could Change Following Third Quarter Earnings
- Omega Healthcare Investors reported third quarter 2026 results that included US$340.55 million in revenue, US$83.09 million in net income, and US$0.27 in diluted EPS from continuing operations, plus a US$0.68 dividend declared for payment in November.
- Alongside the earnings release, Omega Healthcare Investors highlighted active portfolio reshaping, including a US$563 million asset sale, facility transitions to new operators, and leverage reduced to what management described as the lowest level in the company’s history.
- This article examines how Omega Healthcare Investors' investment narrative aligns with its Q3 earnings, portfolio recycling, and lower leverage profile.
Scan how Omega Healthcare Investors’ Q3 reshaping compares to other income-focused real estate plays by zeroing in on our handpicked 5 dividend fortresses.
Omega Healthcare Investors Investment Narrative Recap
To own Omega Healthcare Investors, you need to be comfortable with a skilled nursing focused REIT that leans heavily on rent collection from a concentrated set of operators, uses capital recycling, and prioritises a sizeable dividend. The short term swing factor is how quickly the reshaped portfolio and recent transitions translate into steady cash earnings, not just accounting profit.
The biggest current risk sits with operator credit and transaction timing. Q3 net income of US$83.09 million and diluted EPS of US$0.27 came alongside large asset sales and one off items, which can blur the underlying run rate. If reinvestment of sale proceeds drifts or operator issues resurface, reported revenue and earnings could lag expectations.
The most relevant recent move is the reaffirmed US$0.68 quarterly dividend, payable on November 16, 2026. For many investors, the Omega Healthcare Investors thesis starts with that cash payout, since REIT distributions are often central to total returns and, in this case, are taxed at ordinary income rates in taxable accounts.
Keeping that dividend intact against a backdrop of Q3 EPS of US$0.27 puts attention on funds available for distribution, leverage, and the pace of acquisitions after the US$563 million asset sale. The key execution question is whether management can recycle capital into higher yielding deals quickly enough to support the payout while dealing with any future tenant restructurings.
Omega Healthcare Investors Earnings Outlook Versus Q3 Reality
Analysts looking at Omega Healthcare Investors are not baking in a growth story. They are modelling revenue shrinking by 1.5% per year over the next three years and profit margins easing from 66.8% today to 57.1% by 2029. That is a very different tone compared with the Q3 headline of asset sales, lower leverage and a maintained dividend.
Current earnings are put at US$842.0 million, with consensus calling for US$688.2 million of profit, or US$2.02 per share, by 2029. That implies an earnings drop of about US$153.8 million from today’s level, even before you consider the more cautious analysts who see a path closer to US$584.6 million. For an income focused REIT, that kind of step down in profit sits in the background of every discussion about dividend resilience and reinvestment pacing.
Omega Healthcare Investors would also need to support a much higher valuation multiple to meet consensus targets. The stock is currently on a P/E of 16.9x, while the analyst framework uses a future P/E of 30.6x on those 2029 earnings. That assumed multiple is above the 28.7x figure cited for the broader US Health Care REITs group, so investors are being asked to accept both lower forecast revenue and earnings alongside a richer earnings multiple.
On the top line, analysts tie their price targets to an estimated US$1.2b of revenue and US$688.2 million of earnings in 2029. That profile sits alongside expectations that the share count increases by 2.53% each year for the next three years, which can further dilute per share metrics if earnings do not keep pace. For readers tracking Q3’s asset sale program and facility transitions, the key question is how those moves line up with a consensus outlook that bakes in declining revenue and slimmer margins.
Omega Healthcare Investors' narrative projects US$1.2b revenue and US$688.2 million earnings by 2029. This assumes revenue decreases by 1.5% per year and an earnings decrease of about US$153.8 million from US$842.0 million today.
Uncover how Omega Healthcare Investors' fair value indicates a 6% potential upside to its current price before the market closes that discount.
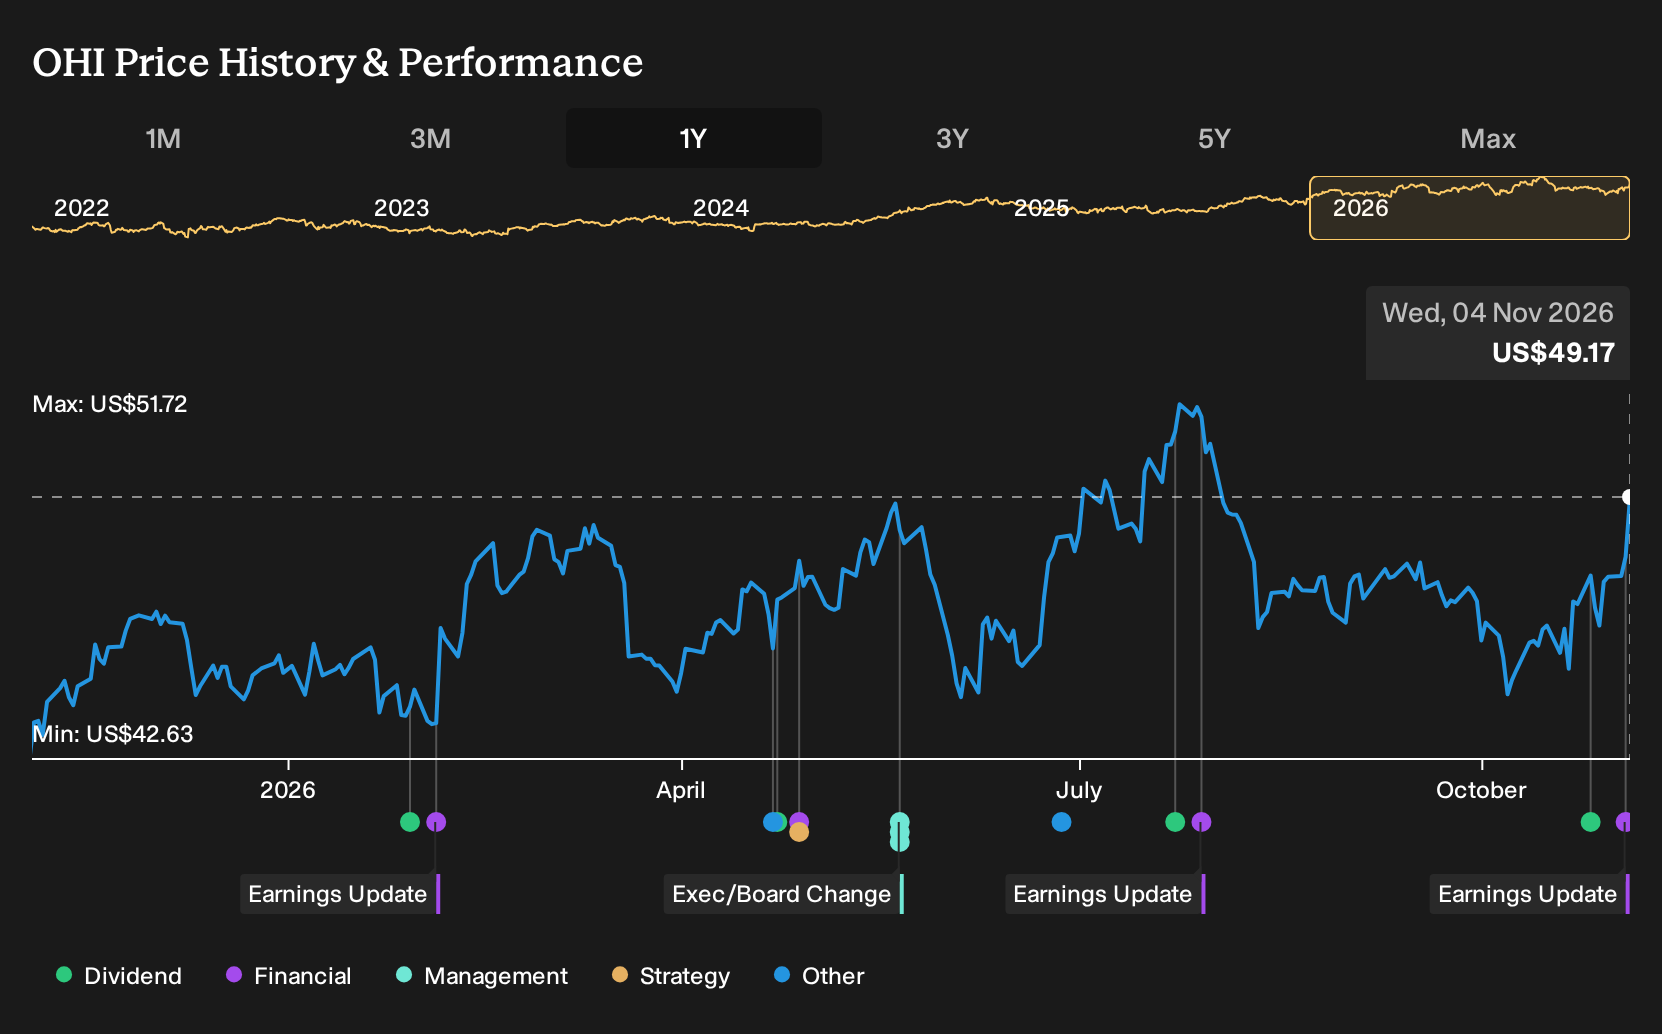
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$51.89 to US$87.18, which shows how far apart private investors can be on Omega Healthcare Investors. Set that against tenant concentration risks and the affirmed US$0.68 dividend, and you get a mix of income appeal and operational questions. You should expect disagreement and seek out several of these viewpoints before deciding how Q3 changes the story for you.
Explore another Omega Healthcare Investors fair value estimate, including one that suggests there could be as much as 77% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Omega Healthcare Investors research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Omega Healthcare Investors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Omega Healthcare Investors' overall financial health at a glance.
Looking For More Ideas Beyond Omega Healthcare Investors?
If Omega Healthcare Investors has sharpened your thinking about income, balance sheets, and risk, use that same framework to scan a wider opportunity set. You do not need to stop at one REIT when there is a whole market of businesses with different payout profiles and financial strengths to compare.
- For investors who want potential upside with a margin of safety, start with companies that combine quality fundamentals and attractive pricing by reviewing the 35 high quality undervalued stocks.
- If balance sheet resilience sits high on your checklist, focus on businesses with robust finances and lower leverage by using the list of solid balance sheet and fundamentals (24 results).
- Income seekers who like the Omega Healthcare Investors dividend story can broaden their watchlist by scanning a curated 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com