
Buyback Plan Could Be A Big Deal For Expro (XPRO)
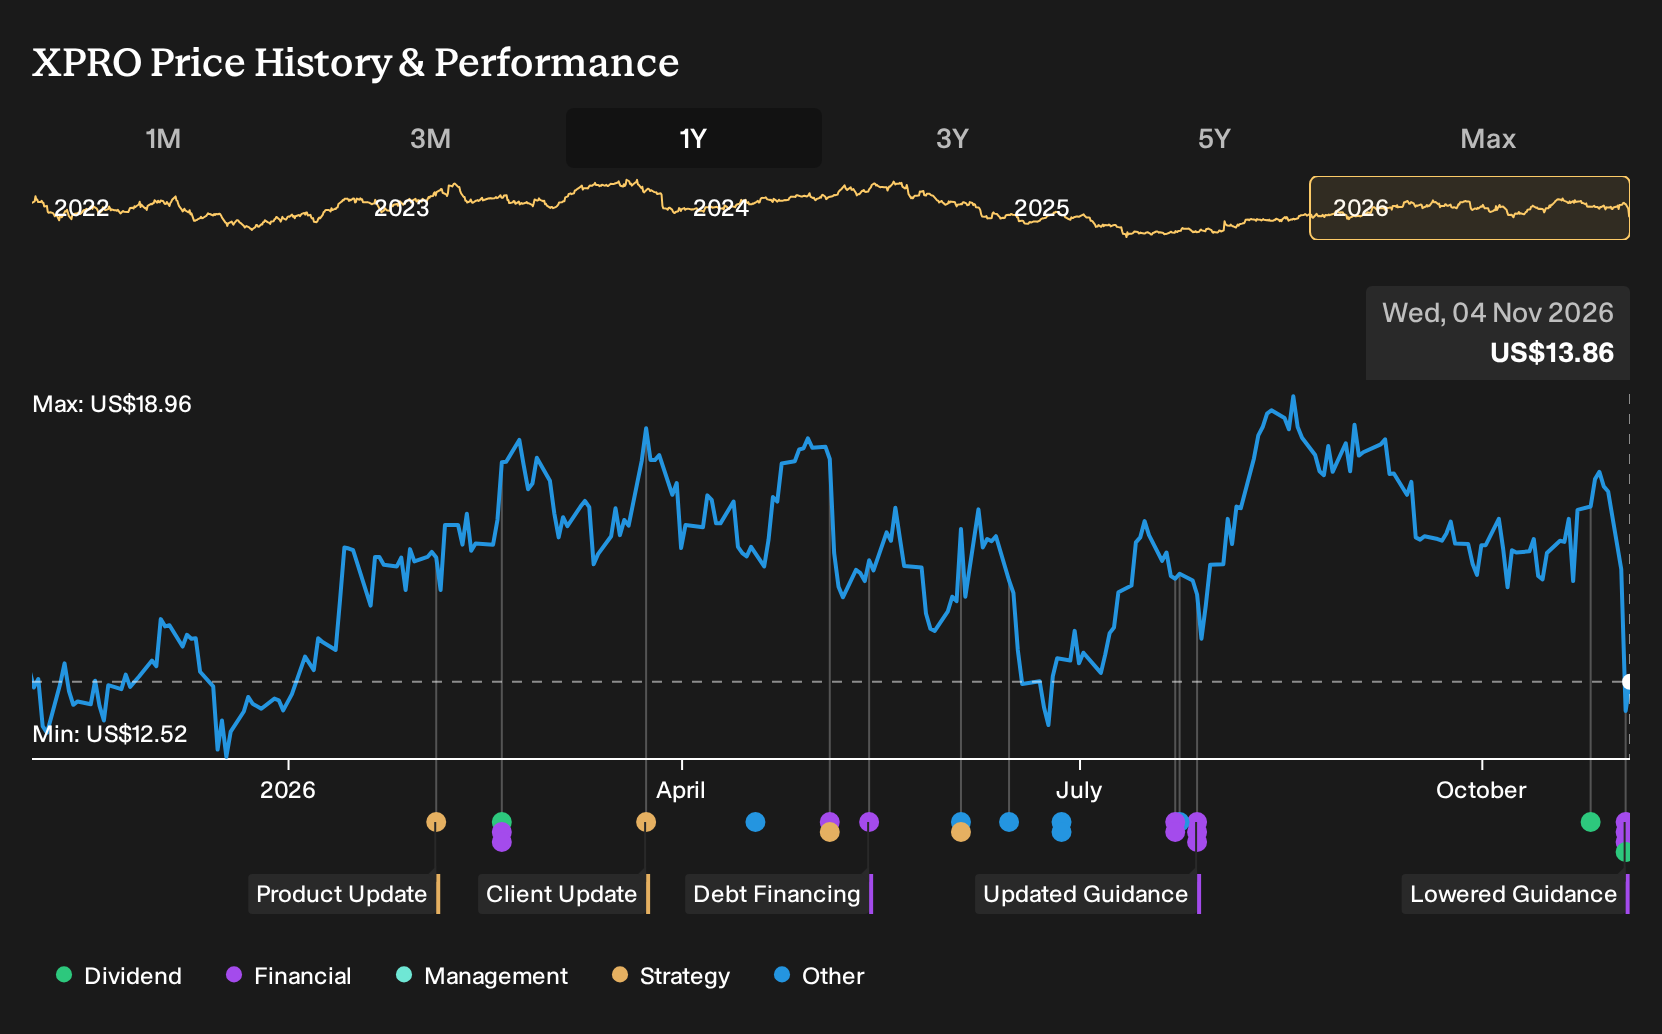
- Expro reported mixed Q3 2026 results, with sales of US$439.94 million and a net loss of US$5.2 million, alongside updated guidance and a new US$100 million share repurchase program running through 2027.
- The combination of a swing to losses, narrower full year revenue guidance, and fresh buyback capacity highlights management’s focus on cost discipline, capital returns, and tighter execution on well construction and well management projects.
- We will look at how Expro's investment narrative around margin expansion and capital returns interacts with its new US$100 million repurchase plan.
Scan how Expro's mix of buybacks, earnings volatility, and project driven revenue compares with other oilfield service peers in our 19 high quality undiscovered gems.
Expro Investment Narrative Recap
For Expro, the thesis still revolves around turning a solid offshore and international footprint into cleaner profitability and steadier cash generation. The latest quarter delivered US$439.94 million of sales but swung to a net loss of US$5.2 million, which keeps execution on cost programs and higher margin work as the key short term catalyst. The main thing to watch is whether upcoming projects, including the Q4 revenue guidance range of US$465 million to US$485 million, translate into better margins rather than just more activity.
The biggest operational risk right now is that earnings volatility persists while the business remains heavily exposed to international and offshore spending, especially where geopolitics or regulation can disrupt higher margin jobs. With nine month sales broadly similar to last year but profitability weaker, the recent results mainly reinforce that risk rather than change it. If the impact of project delays or mix shifts proves temporary, the long term margin expansion story remains in place. If the impact proves more persistent, the margin recovery narrative starts to look stretched.
The new US$100 million share repurchase program running through 2027 is the announcement that ties closest to this update. Expro has already bought back US$52 million under the prior authorization, retiring 3,227,537 shares, or 2.85% of the float. The extra capacity means management is setting expectations that net cash generation and balance sheet flexibility can support continued capital returns even with recent losses and one off items in the numbers.
For you as a shareholder, the practical question is whether this buyback sits on top of, rather than instead of, progress on Drive 25 cost savings, integration of Enhanced Drilling and Coretrax, and improvement in free cash flow margins. If operating results stay choppy, repurchases concentrate exposure to a business that still has low reported profit margins and limited scale versus bigger peers. If the cost and mix initiatives gain traction, the reduced share count could increase any eventual improvement in earnings per share.
Expro's narrative projects US$1.9b revenue and US$177.9 million earnings by 2029. That profile assumes 6.4% yearly revenue growth and an earnings increase of about US$157 million from US$20.7 million today.
Explore why Expro's fair value suggests a 26% potential upside to its current price before other investors respond to that opportunity.
Exploring Other Perspectives
For Expro, the most optimistic twist comes from the bullish view on Middle East recovery. Those analysts were penciling in US$1.9b of revenue and US$185.1 million of earnings by 2029, and a US$20.0 price target, before this latest loss and fresh US$100 million buyback. This may prompt them to rethink that optimism.
Explore 2 other Expro fair value estimates, including one that suggests potential upside of as much as 205% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Expro research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Expro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Expro's overall financial health at a glance.
Looking for more investment ideas beyond Expro?
Once you have a view on Expro, it can help to widen the lens and compare it with other opportunities that fit different portfolio roles.
- If you want potential upside with a focus on balance sheet strength and solid fundamentals, take a look at our list of solid balance sheet and fundamentals (24 results) to see which companies meet that standard.
- For investors who prioritise quality at a reasonable price, scan the 35 high quality undervalued stocks to spot businesses where fundamentals and valuation may be out of sync.
- If capital preservation and smoother performance are higher on your checklist, review the 31 resilient stocks with low risk scores and compare how those stocks line up against your current holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com