
Nelnet (NNI) Looks Overvalued As Its Share Price Jumps To $127.58
Nelnet (NNI) has drawn fresh attention after a recent price move that left the share price at US$127.58. This has invited investors to reassess the diversified financial group’s mix of loan servicing, education technology, and banking.
Recent trading tells a mixed story for Nelnet. A 4.11% 1 day share price return and a 4.68% 7 day share price move sit against a 90 day share price return that fell 5.39%, while the 5 year total shareholder return of 56.52% points to a steadier long run outcome.
Compare Nelnet’s recent swings with other financial stocks that pair diversified revenue and balance sheet strength by scanning the hand picked list of solid balance sheet and fundamentals (24 results).
Nelnet now trades slightly above both its estimated fair value and the average analyst target after that recent jump. Is the market being too cautious on the mix of lending, servicing, and education payments, or not cautious enough?
Price-to-Earnings of 15.1x: Is it justified?
Narrowing in on Nelnet, the stock trades on a P/E of 15.1x at a last close of $127.58, which puts it roughly in line with close peers but richer than the wider consumer finance group.
The P/E ratio compares the current share price to earnings per share. For a diversified financial business like Nelnet, this metric effectively reflects what investors are willing to pay for each dollar of current profit, especially when earnings forecasts are limited or patchy.
Here, the market is assigning Nelnet a multiple that almost matches the peer average P/E of 15.3x. It is, however, materially higher than the broader US Consumer Finance industry average of 8.5x. That suggests investors are putting a relatively full price on the company’s earnings profile despite earnings having declined by 10.6% per year over the past 5 years and a forecast earnings growth rate of 1% per year that trails the wider US market expectation of 17% per year.
The gap to an estimated fair P/E of 10.6x is also meaningful. Compared to that reference point, the current 15.1x looks demanding. This points to a level the market could move toward if sentiment or earnings do not shift in Nelnet’s favor.
Explore the SWS fair ratio for Nelnet.
Result: Price-to-Earnings of 15.1x (OVERVALUED)
Still, the recent share price strength, along with a P/E above the sector average, could unwind quickly if earnings disappoint or if sentiment toward consumer finance tightens again.
Find out about the key risks to this Nelnet narrative.
Another View on Nelnet’s Value
There is a sharp contrast when shifting from Nelnet’s P/E to our DCF model. On that second yardstick, the stock at $127.58 sits far above an estimated future cash flow value of $20.58, which signals a very stretched price instead of a modest premium.
This kind of gap limits room for error. If cash flows do not track the optimistic path implied in today’s price, the adjustment could be painful for anyone expecting only mild moves around current levels.
Look into how the SWS DCF model arrives at its fair value.
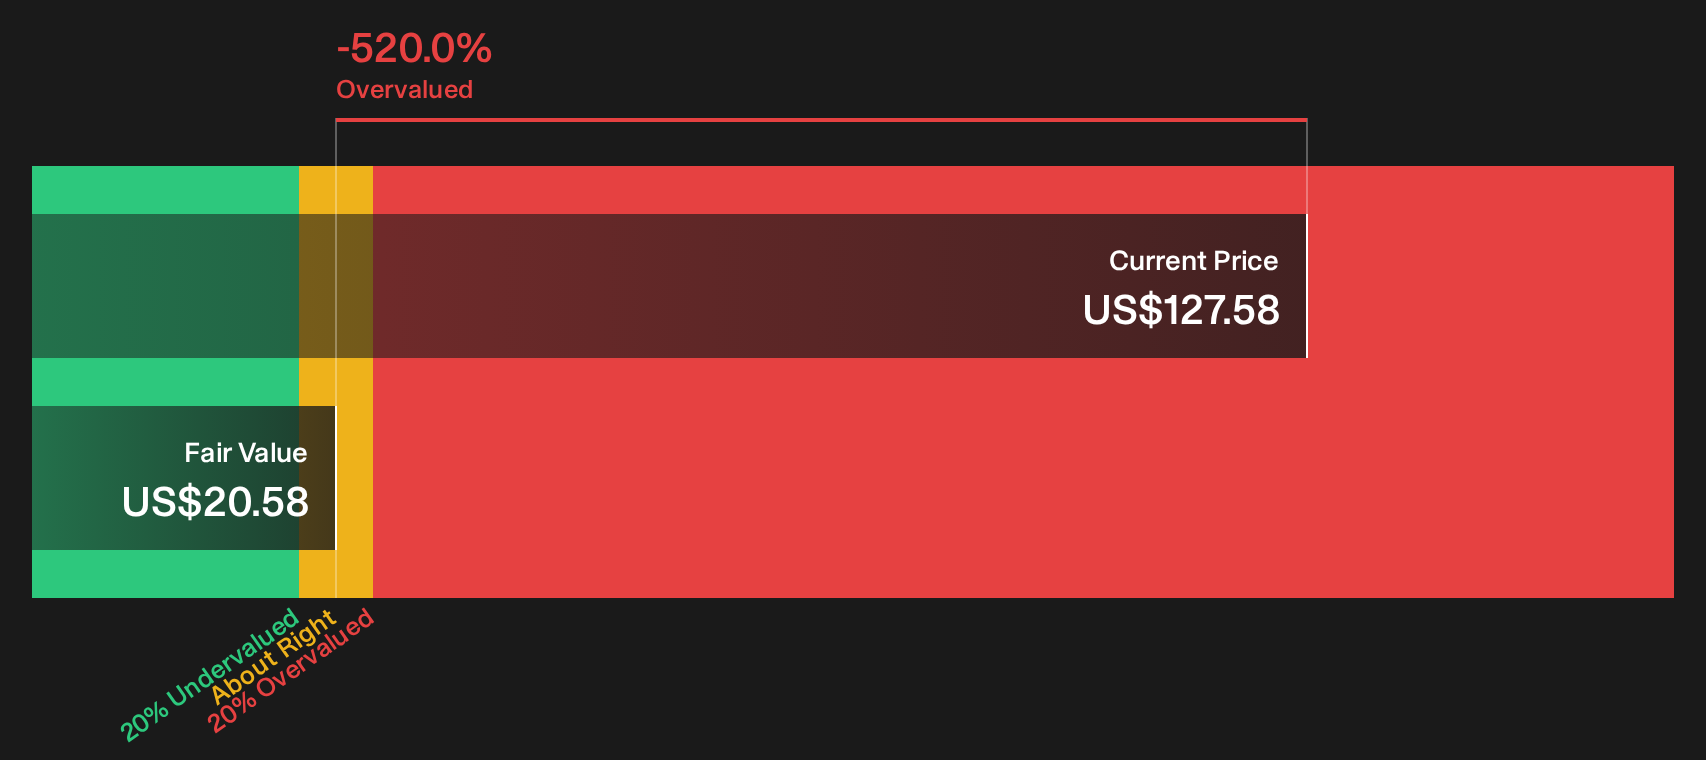
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nelnet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Seeing mixed signals on Nelnet’s valuation and feeling unsure what to make of it is normal. Consider reviewing the underlying data for yourself and weighing both the concerns and bright spots by checking the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Nelnet?
If Nelnet’s valuation picture feels tight, widen your lens. Fresh ideas can balance your portfolio and sharpen how you judge opportunities like this one.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (24 results) that highlights companies pairing financial strength with underlying fundamentals.
- Hunt for mispriced quality through the 35 high quality undervalued stocks focused on businesses where fundamentals and price appear out of sync.
- Spot early stage potential with the 7 elite penny stocks with strong financials that filters for smaller companies backed by stronger financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com