
Is Veeva Systems (VEEV) Still Below Fair Value After UCB Backed Vault CRM?
Veeva Systems (VEEV) is back in focus after UCB committed to its Vault CRM platform, reinforcing how life sciences groups are using Veeva’s industry-specific AI tools for commercial execution.
Recent price action backs up that customer traction. Veeva Systems has a 30 day share price return of 9.59% and a 90 day share price return of 42.62%, while the 1 year total shareholder return is 5.21%. This points to strong near term momentum on top of mixed longer term results.
Scan beyond Veeva Systems and see how other life sciences and AI-focused players are lining up by fundamentals with the curated 38 healthcare AI stocks.
Veeva Systems now has big pharma leaning on its platforms and a share price that has surged in recent months. The business looks strong. Is the current tag on that strength still reasonable?
Most Popular Narrative: 19% Undervalued
The most followed valuation view pegs Veeva Systems at a fair value of $383.14 a share versus the last close of $310.63, which implies the story in the background still treats the current quote as a discount.
Veeva’s attraction is not simply that it sells software to pharmaceutical companies.
Its attraction is that it sits inside workflows where reliability, compliance, historical data, and institutional trust matter enormously. Those characteristics can produce customer relationships that are unusually long-lived and difficult to displace.
See why 52 investors see Veeva Systems as 19% undervalued.
According to John_Eric, who authored the most widely followed narrative, that fair value is built on Veeva Systems being treated as a long term compounder where embedded workflows and high retention give the business time to turn product breadth, including life sciences specific AI tools, into earnings power. The gap between the $383.14 fair value marker and the $310.63 share price reflects that view, even though the stock has already moved sharply in recent months.
The same narrative framework also leans on a relatively high profit margin of 28.37% and revenue growth assumptions of 22.85% that were baked into the model when it was set up. Those inputs sit alongside a discount rate of 8.05%, which is the hurdle rate used to bring expected cash flows back to today and helps explain why the outcome shows Veeva as undervalued rather than just fairly priced.
Readers should keep in mind that this narrative is one possible map, not a guaranteed outcome, and it can diverge from other signals on Veeva Systems such as analyst targets, which currently sit slightly below the market price, or alternative models that point to different fair values. Treat the $383.14 estimate as a reference point to test your own assumptions on growth, margins, and risk rather than a forecast that must be met.
Result: Fair Value of $383.14 (UNDERVALUED)
Still, two pressure points could upend that 19% undervalued narrative: slower life sciences software spending and weaker adoption of Veeva Systems’ Falcon AI products.
Find out about the key risks to this Veeva Systems narrative.
Another View: What Veeva Systems’ P/E Ratio Is Saying
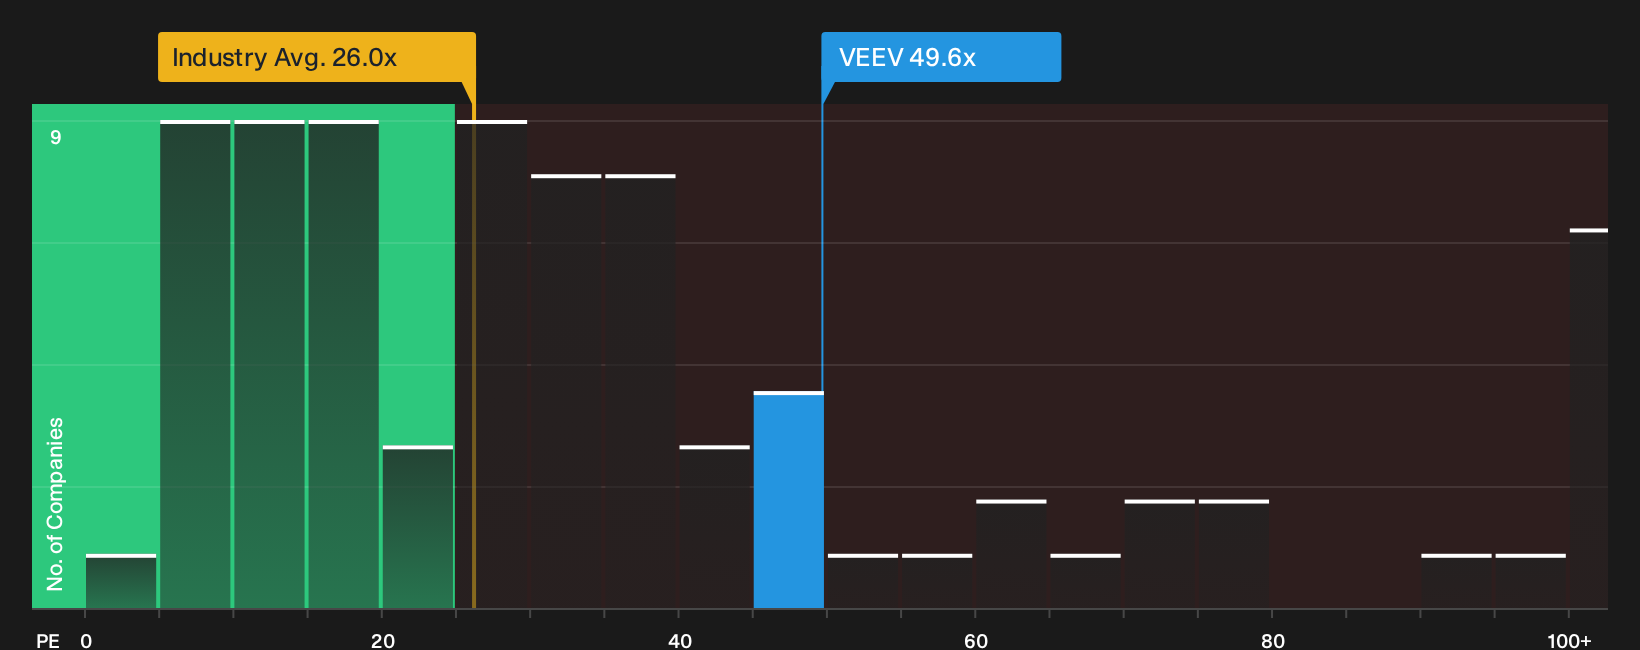
There is a different signal coming from simple price multiples. Veeva Systems trades on a P/E of 49.6x, while the fair ratio is 34x, the US Healthcare Services industry sits around 26x, and peers average 51.4x. That points to a quality premium, and also raises a question about how much upside is already priced in for you as a shareholder.
For a closer look at how that gap could close through either earnings catching up or the share price cooling off, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Veeva Systems currently presents mixed signals. The data shows elements of both concern and optimism. Consider reviewing the details and testing the story yourself by checking the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Veeva Systems?
If you stop with Veeva Systems, you miss a wider field of opportunities. Use the Simply Wall St Screener to compare quality, value, and resilience across different companies.
- Target resilient balance sheets and steady fundamentals by running the list of solid balance sheet and fundamentals (24 results).
- Spot potential value gaps where quality and price look misaligned through the 35 high quality undervalued stocks.
- Hunt for under the radar opportunities that larger investors may overlook using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com