
CAVA (CAVA) Stock Looks Stretched Against Its Current Earnings
CAVA Group has delivered a 3 year return of 99.3%, putting a lot of attention on whether that kind of share price outcome lines up with what the business is actually earning. After a stretch that included both upbeat expansion headlines and a sharp pullback around recent results, the question is how much of CAVA's earnings power is already built into today's price.
- A 99.3% gain over 3 years puts long term holders in a strong position, which raises the stakes for whether current earnings can carry that valuation.
- Recent news around slower same restaurant growth and the impact of a food safety scare has put the focus on how durable CAVA's margins and profit trajectory really are, which feeds directly into what investors might be willing to pay for each dollar of earnings.
- The analysts covering CAVA Group have run their own numbers. See what analysts think CAVA Group's shares could be worth.
The issue now is whether CAVA's current share price can be justified by its earnings when set against the Fair Ratio benchmark.
If you want a second reference point beyond CAVA Group's recent swings, a focused screen built around 35 high quality undervalued stocks can be a useful place to start your next round of research.
Is CAVA Group Getting Expensive on Earnings?
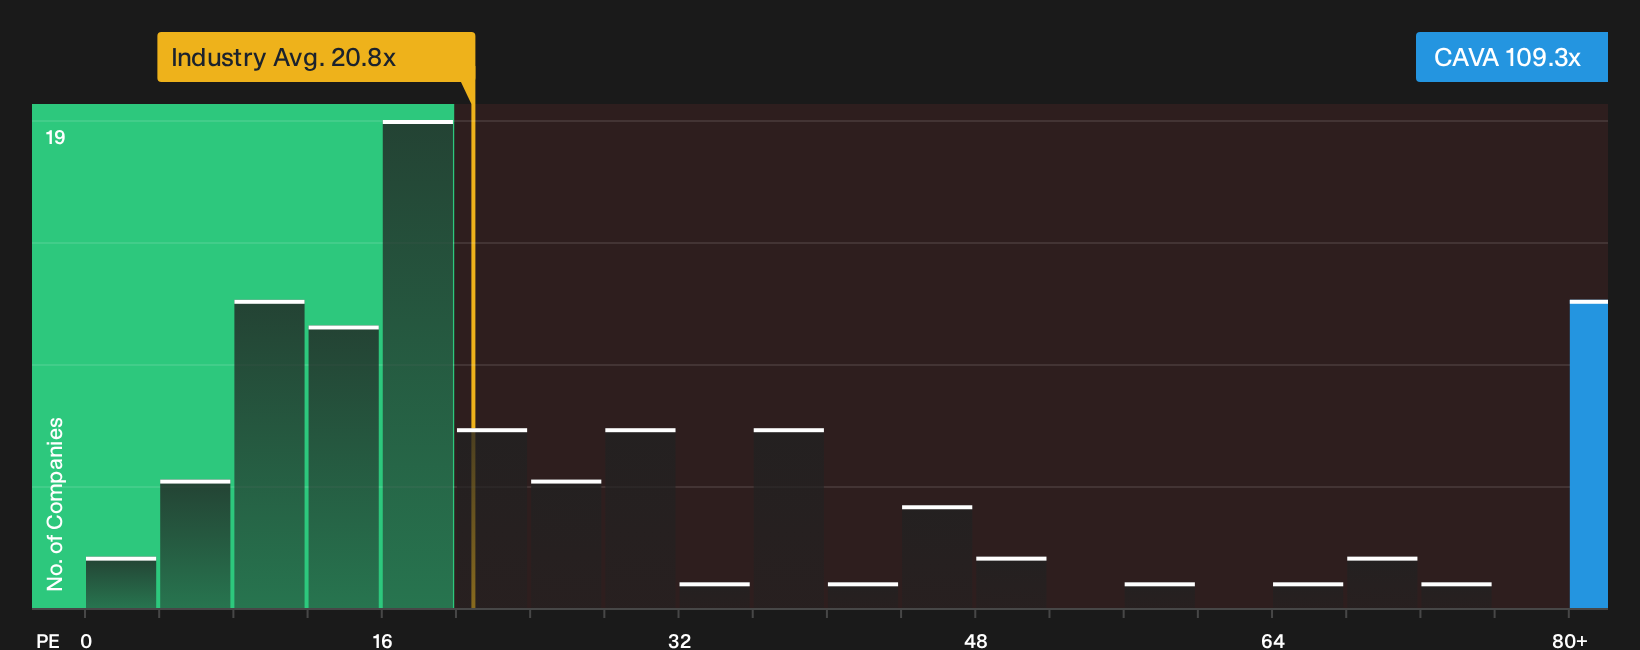
The P/E ratio works well for CAVA Group because the stock already has positive earnings to anchor the comparison. On this yardstick, the shares trade at about 109.3x earnings, which is roughly double the 55.9x peer average and far above the broader hospitality sector near 20.8x. That kind of premium means investors are paying a high price for each dollar of profit relative to similar restaurant operators.
Recent Q3 news around a revenue and earnings miss, plus management comments about industry pressures, sits awkwardly next to such a rich multiple, since the valuation leaves less room for bumps in the road. A Fair Ratio model that blends CAVA Group’s growth profile, profitability, size and risk flags the current P/E as overvalued and shows the stock as screening extremely expensive because the framework heavily penalises the current risk and earnings base. For readers, the key question is whether the brand strength, unit expansion and margins justify paying this kind of premium today. Explore the numbers behind CAVA Group's P/E valuation.
The CAVA Group Narrative: What Would Justify Today's Price?
Narratives for CAVA Group pick up where the valuation puzzle leaves off, spelling out which future paths for growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it does today on Simply Wall St's Community page. Instead of a single ratio or model output, they present the underlying storyline that each number relies on, so you can watch how real world results compare with it over time.
Bulls and bears on CAVA Group are reading the same expansion story but drawing very different conclusions about what the current price already assumes.
Bull case: 25% undervalued
"Strengthening digital engagement through higher digital mix approaching about 40% of sales, expanded loyalty features like tiers and the invite only Oasis level…"
Discover why this Narrative puts CAVA Group at 25% undervalued.
Bear case: 36% overvalued
"While CAVA Group continues to open restaurants at a rapid pace and talks about a long runway for national expansion, the Cyclospora outbreak that caused a 4.2% decline in traffic…"
Explore why this Narrative puts CAVA Group at 36% overvalued.
Before you move on CAVA Group still has other questions to answer
Valuation only tells part of the story for CAVA Group, since Simply Wall St’s broader checks have already flagged specific areas of concern that deserve your attention next. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com