
Rocket Lab (RKLB) Launches HawkEye Mission As Its Valuation Story Faces A Reality Check
Rocket Lab (RKLB) just completed its dedicated Electron mission for HawkEye 360, deploying three HAWK satellites into a 520 km low Earth orbit from New Zealand. For investors, that fresh operational data point now sits beside a sharply weaker share price over the past month.
That successful HawkEye 360 launch lands at a time when Rocket Lab’s share price has fallen 28% over the past month and 31% year to date. However, the 3 year total shareholder return is extremely high, which hints that recent volatility reflects shifting expectations around Neutron delays, the Iridium deal and broader space sector sentiment rather than a simple one way view on the business.
Scan beyond Rocket Lab and compare this volatility story with a curated group of space and tech contractors that currently screen as 19 high quality undiscovered gems in the Simply Wall St tool.
Bulls point to Rocket Lab’s contracts, Iridium move and Electron track record, while bears focus on Neutron delays, insider sales and a high P/S multiple. Which story does the valuation actually support next?
Most Popular Narrative: 49% Undervalued
Rocket Lab's most followed valuation story pins fair value at $102.15 against a last close of $52.37, so the gap between price and narrative is wide and forces investors to ask what really has to go right.
Rocket Lab's move toward end-to-end space solutions, including the acquisition of Geost and expanding vertically integrated payload, satellite, and launch service capabilities, uniquely positions the company to capture larger national security and defense contracts such as the Golden Dome and SDA constellations. This is cited as supporting significant top-line growth and enhanced gross margins in future quarters.
Escalating demand for real-time data, earth observation, and global connectivity is described as driving increasing recurring revenue opportunities through satellite constellation launches and manufacturing. Rocket Lab's high Electron launch cadence and in-house satellite production (including potential for future proprietary constellations) are presented as enabling the company to capitalize on these industry tailwinds, supporting multi-year revenue growth and backlog expansion.
See why 481 investors see Rocket Lab as 49% undervalued.
Result: Fair Value of $102.15 (UNDERVALUED)
Still, the Neutron delay to 2027 and ongoing cash burn tied to high R&D and capital spending could quickly challenge the bullish Rocket Lab valuation story.
Find out about the key risks to this Rocket Lab narrative.
Another View: Rocket Lab Looks Expensive On Sales
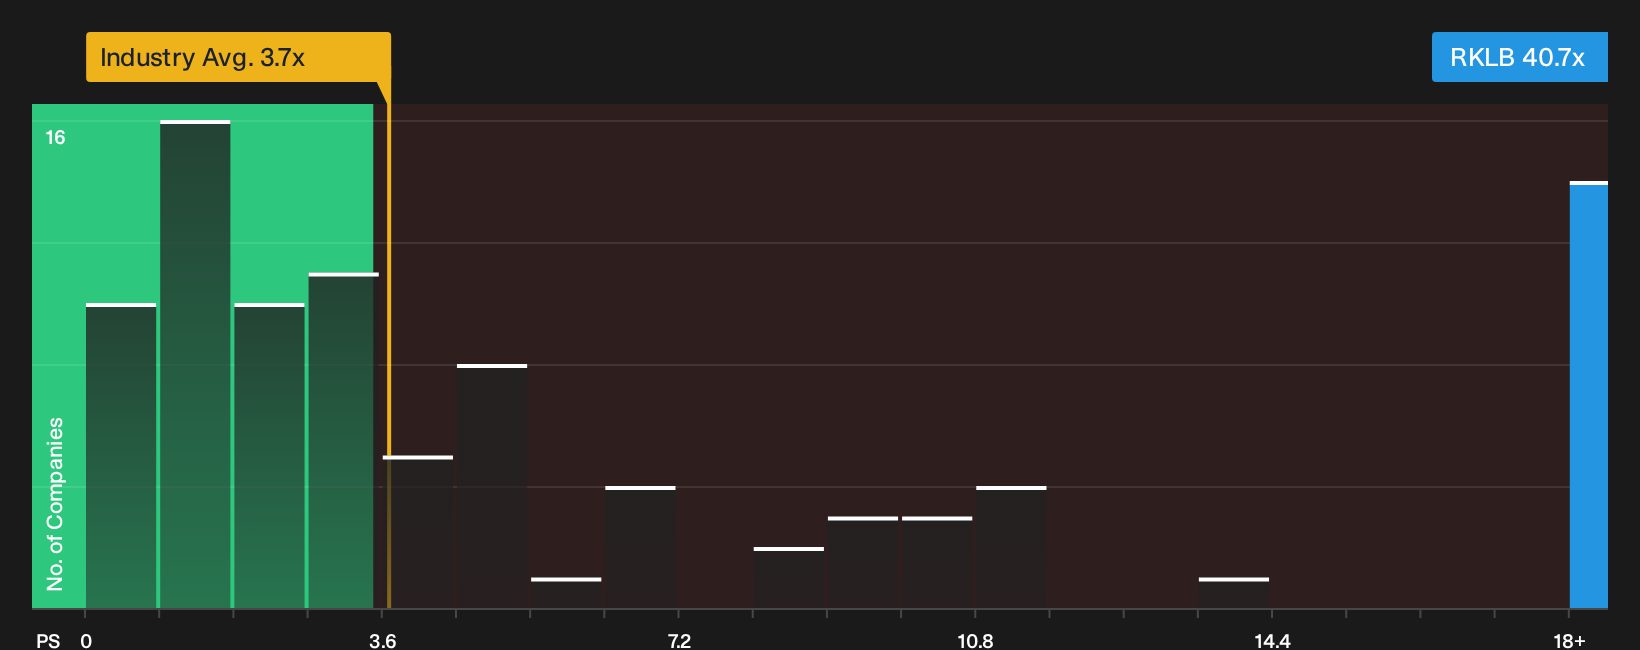
Rocket Lab may screen as 49% undervalued on analyst fair value, yet the simple sales multiple tells a very different story. The stock trades on a P/S ratio of 40.7x compared with a fair ratio of 9.2x, the US Aerospace & Defense group at 3.7x and peers at 9.1x. That gap suggests investors are paying a heavy premium for future execution, so the real question is whether you are comfortable underwriting that kind of stretch.
Before leaning on this high sales multiple, it is worth stress testing whether the underlying assumptions match your own view on contract risk, Neutron timing and dilution. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Rocket Lab can either sharpen your thinking or cloud it. Move quickly, test the numbers yourself and weigh the 2 key rewards and 2 important warning signs.
Looking for more Rocket Lab sized ideas?
If Rocket Lab has sharpened your thinking, do not stop here. Broaden your watchlist now so you are not chasing the next move after it happens.
- Target potential upside in quality first by scanning a focused list of 35 high quality undervalued stocks that pair strong fundamentals with appealing valuations.
- Prioritize staying power over thrills by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you focus on businesses built to handle tougher conditions.
- Reduce portfolio stress by filtering for 31 resilient stocks with low risk scores that aim to keep volatility in check while you focus on long term compounding.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com