
Does Earnings Beat Change The Bull Case For Alkermes (ALKS)?
- Alkermes reported past third quarter 2026 revenue of US$480.13 million and net income of US$16.29 million, while nine month results showed US$1.37b in revenue and a net loss of US$49.69 million.
- The launch of a phase 2 trial for orexin 2 agonist ALKS 7290 in major depressive disorder adds another potential use for Alkermes’ growing orexin portfolio, which already targets sleep, addiction and psychiatric conditions.
- We will now look at how Alkermes’ stronger proprietary sales and the new ALKS 7290 depression trial shape its investment narrative.
Compare Alkermes' orexin driven story with other potential opportunities by scanning our hand picked 38 healthcare AI stocks focused on neuroscience, data driven therapies and next generation healthcare platforms.
Alkermes Investment Narrative Recap
To own Alkermes, you need to believe the orexin and neuroscience portfolio can offset a period of weaker profitability. Third quarter 2026 results showed US$480.13 million in revenue and US$16.29 million in net income, yet nine month figures still reflected a net loss. The short term swing factor is whether proprietary product momentum and cost control can narrow that earnings gap without starving the pipeline.
The biggest risk right now is sustained high R&D and integration spend that keeps GAAP losses elevated while the share price already reflects meaningful pipeline success. Recent earnings do not materially change that equation. They reinforce that Alkermes is spending heavily on orexin programs while relying on existing psychiatry, addiction and sleep products to fund the effort.
The most relevant announcement here is the new phase 2 study of ALKS 7290 in major depressive disorder. This expands Alkermes' orexin 2 program beyond ADHD and hypersomnolence conditions into a large psychiatric indication, using adjunctive treatment alongside standard antidepressants as the test case.
For you as an investor, ALKS 7290 is now more tightly linked to both upside and downside. Positive safety and symptom data could support a broader orexin thesis and help justify elevated R&D. Weak tolerability or limited benefit on measures such as MADRS or CGI S would add to the risk that higher expenses do not translate into future approvals or new revenue streams.
Alkermes' current projections point to revenue of US$2.3b and earnings of US$363.0 million by 2029, based on analysts looking for 10.6% yearly revenue growth and an earnings increase of roughly US$297 million from US$66.1 million today.
Uncover how Alkermes' fair value indicates a 23% potential upside to its current price, which could narrow quickly.
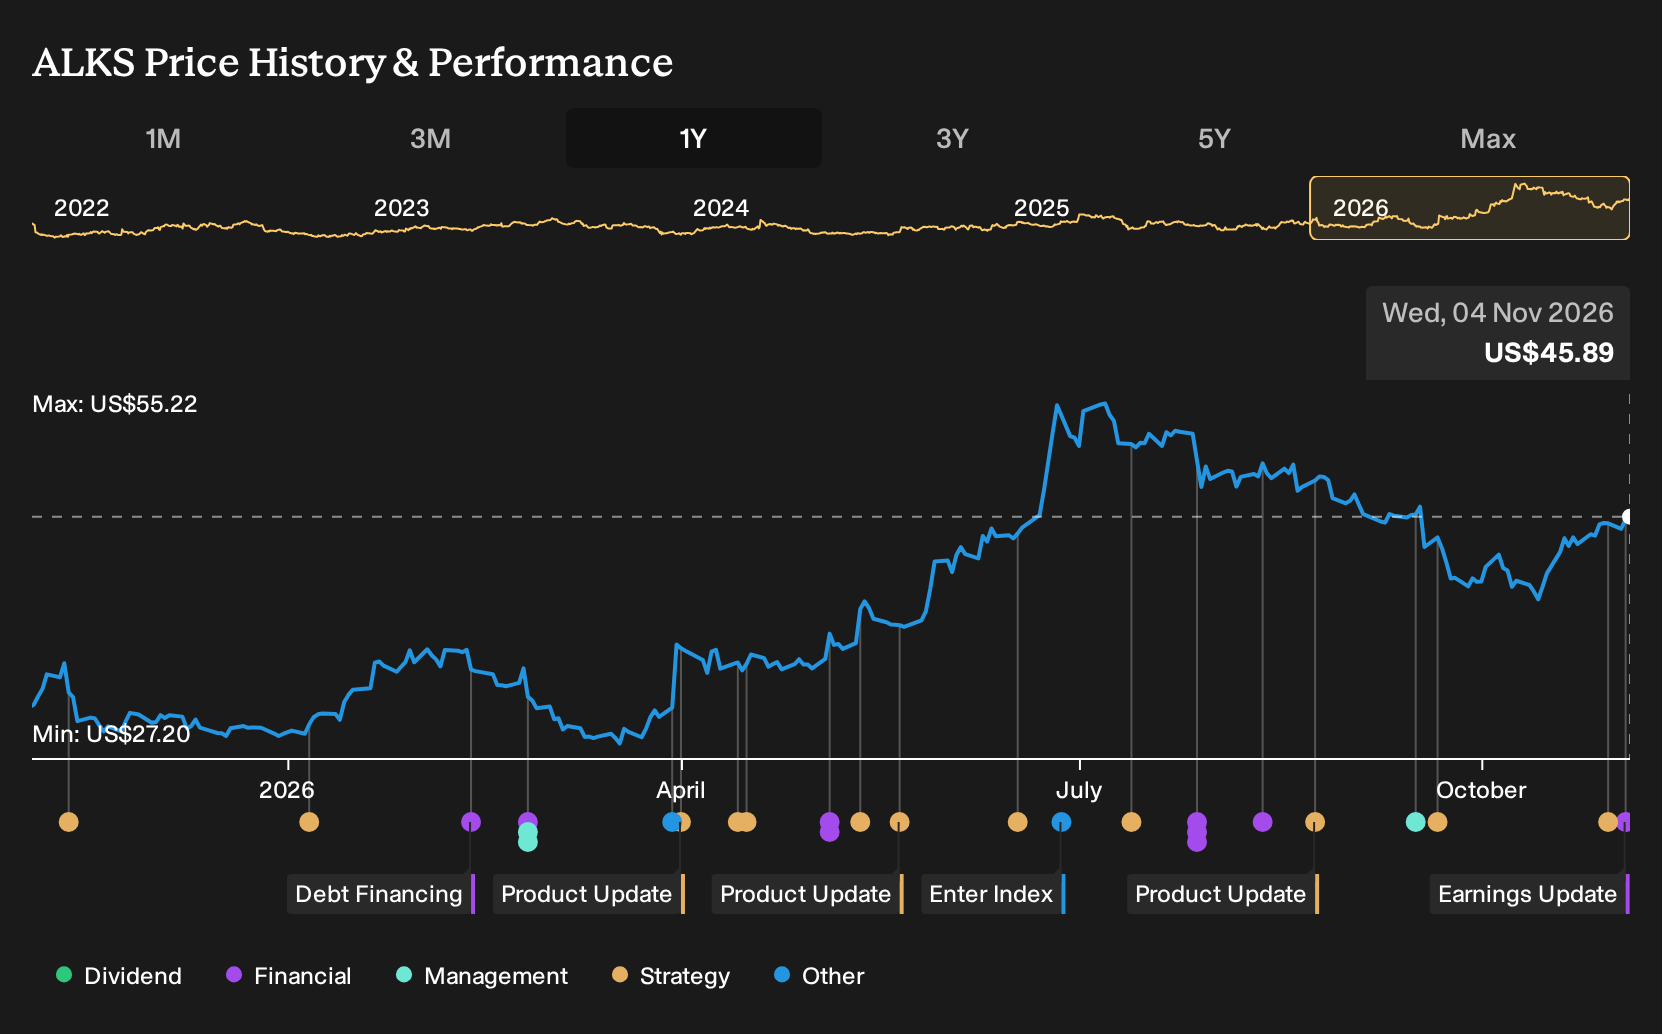
Exploring Other Perspectives
For Alkermes, the more cautious analysts fixate on sustained high SG&A as the key risk, not the orexin data itself. Before this latest earnings and ALKS 7290 depression trial update, the lowest forecasts were built on only 6.4% annual revenue growth and 2029 earnings as low as about US$346.5 million or even a loss. That is a very different story from the consensus, and this new information could push those expectations higher or lower. Use that spread as a reminder that smart people can disagree widely, and treat it as a prompt to compare several viewpoints before you decide where you stand.
Explore 4 other Alkermes fair value estimates, including one that suggests there could be as much as 17% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alkermes research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Alkermes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alkermes' overall financial health at a glance.
Looking For More Investment Ideas Beyond Alkermes?
If Alkermes has helped sharpen your thinking but you want a broader watchlist, the Simply Wall St Screener can surface other stocks that fit the kind of risk and return profile you care about most.
- For readers who care most about balance sheet strength and business resilience, start with a list of solid balance sheet and fundamentals (24 results) that do not lean heavily on fragile financing.
- If capital preservation is your priority and you want steadier price action, filter for 31 resilient stocks with low risk scores that score well on our risk checks.
- When you want to hunt for potential future leaders before they are widely followed, focus on a 19 high quality undiscovered gems that already show strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com