
Empire State Realty OP (ESBA) Following A 17% Monthly Rebound Looks Cheap On Sales
Empire State Realty OP (ESBA) has drawn fresh attention after a recent swing in returns. The partnership shows a roughly 17% gain over the past month and a modest rise over the past 3 months.
The recent 17.1% one-month share price return for Empire State Realty OP contrasts with a year-to-date share price decline of 19.4% and a one-year total shareholder return that is down 27.1%. This suggests short-term momentum may be building following a weaker longer period for investors.
Scan how Empire State Realty OP compares with other real estate plays showing similar momentum and recent weakness by reviewing the curated 35 high quality undervalued stocks.
After that sharp one month rebound against a much weaker one year record, the real issue for Empire State Realty OP is whether current pricing still offers a skewed reward versus the risks. The valuation markers give the next clue.
Preferred Price-to-Sales of 1.8x: Is it justified?
On the numbers, Empire State Realty OP screens as inexpensive against peers. The units last closed at $5.03, while the partnership is described as good value on a P/S ratio of 1.8x compared both to a 4.6x peer average and a 3x North American REITs average.
The price to sales multiple takes the market value of the equity and compares it to annual revenue. For a real estate focused vehicle like Empire State Realty OP, where earnings can be noisy because of depreciation and one off items, P/S can give a cleaner read on what investors are paying for each dollar of top line generated by the Observatory and Real Estate segments.
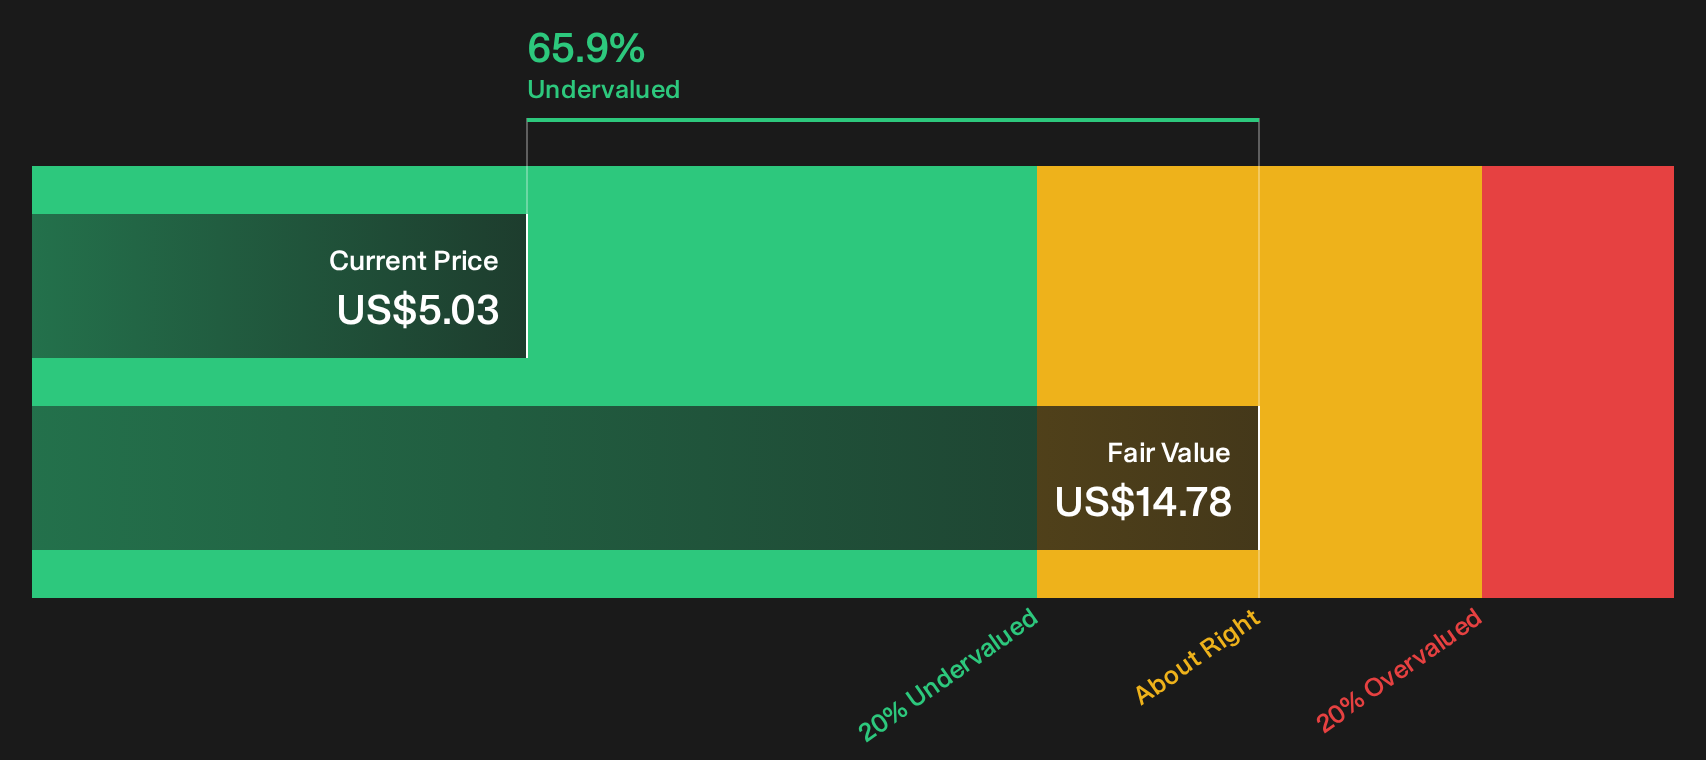
A P/S of 1.8x against a peer group at 4.6x suggests the market is assigning a marked discount to this partnership's revenue stream. That gap may reflect weaker recent earnings quality, including the impact of a large one off loss of $25.3m and thinner current profit margins of 0.6% compared with 8.5% last year, as well as interest payments that are not well covered by earnings. Even with those issues, the current multiple is far below where similar REITs trade according to the statement data. This points to investors pricing in a heavier set of risks relative to sector averages rather than paying up for the SWS DCF estimate that places fair value at $14.78 per unit.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Sales of 1.8x (UNDERVALUED)
Still, thin 0.6% profit margins and interest costs that earnings do not comfortably cover could quickly challenge any Empire State Realty OP recovery narrative.
Find out about the key risks to this Empire State Realty OP narrative.
Another View on Empire State Realty OP's Value
That 1.8x P/S tag for Empire State Realty OP looks low compared with peers, yet our DCF model presents an even starker picture. Based on those cash flow assumptions, the fair value estimate is approximately $14.78 per unit, while the current price is about $5.03. This implies a significant valuation gap that investors need to interpret carefully. Is this a genuine mispricing, or a signal that the market questions the durability of those future cash flows?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Empire State Realty OP for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Empire State Realty OP's value story. If you want to move quickly and judge the risk and reward trade off yourself, start with the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond Empire State Realty OP?
If Empire State Realty OP has your attention, do not stop here. The next strong opportunity may be sitting in plain sight on a different ticker.
- Target resilient balance sheets and steady fundamentals by scanning our hand picked list of solid balance sheet and fundamentals (24 results) that keeps financial strength front and center.
- Hunt for mispriced quality by reviewing the carefully filtered 19 high quality undiscovered gems that many investors have not focused on yet.
- Prioritise capital preservation by checking the curated 31 resilient stocks with low risk scores built to spotlight businesses with lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com