
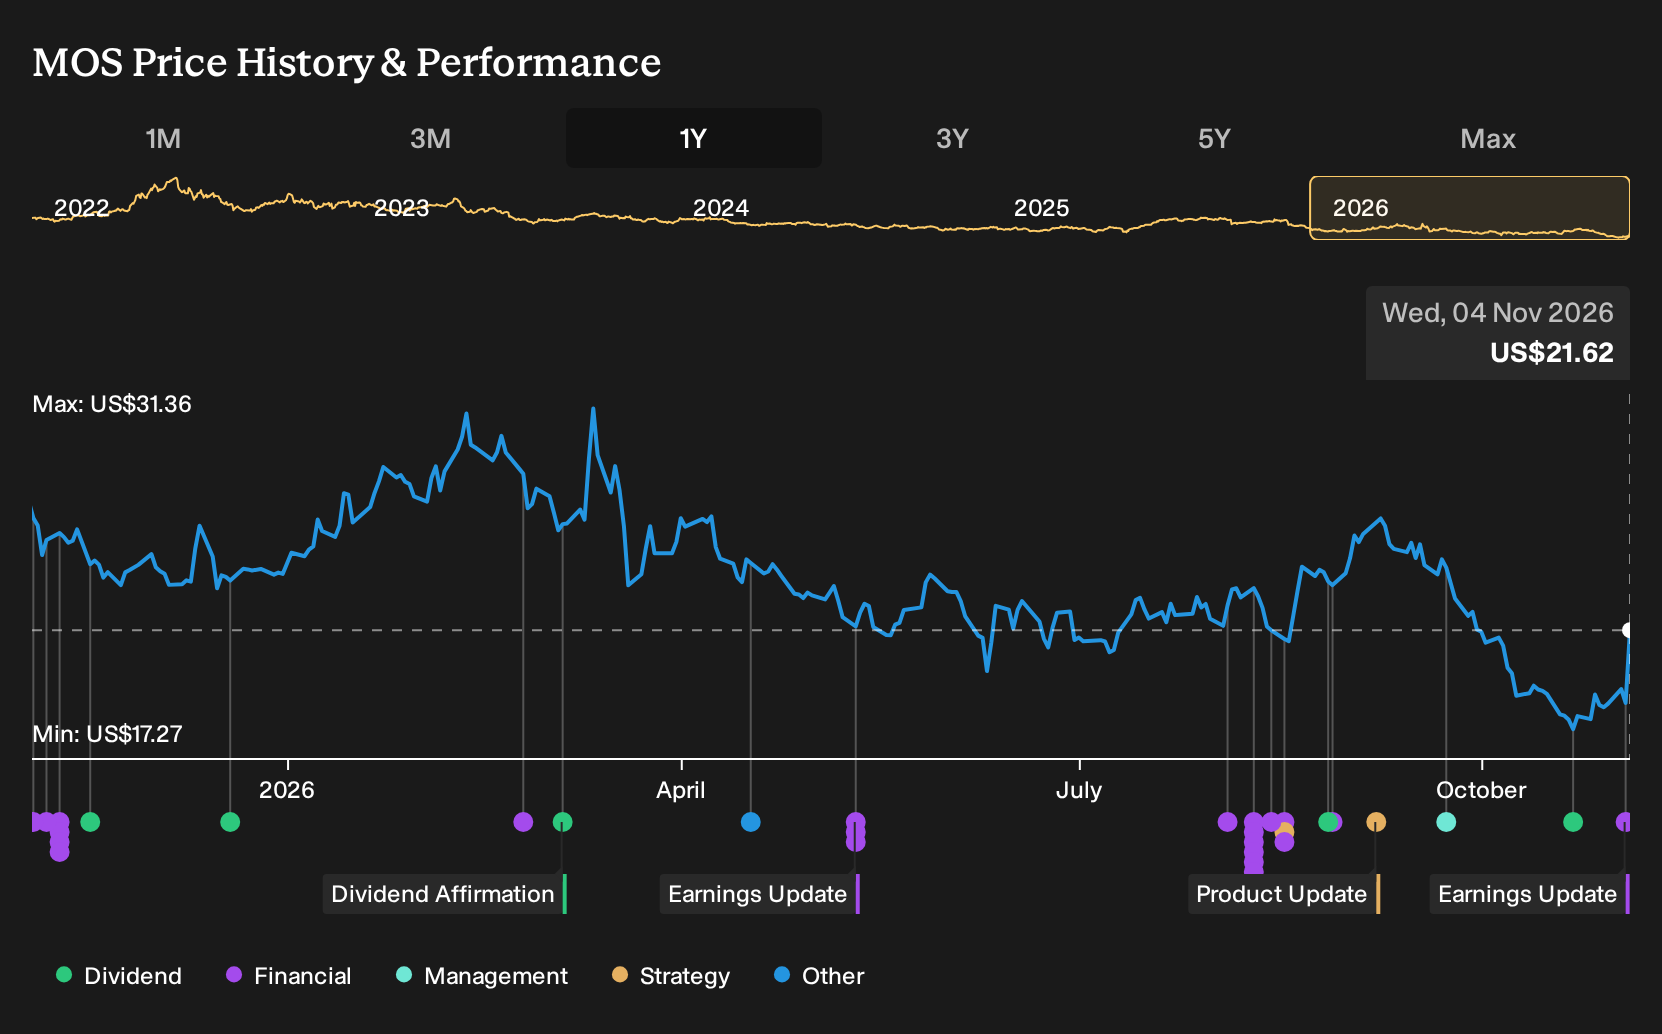
Why Mosaic Stock Is Moving After An Earnings Miss And Cautious Outlook
- Mosaic reported third quarter 2026 sales of US$3,100.6 million and a net loss of US$72.1 million, with diluted loss per share from continuing operations of US$0.23, compared with a profit and higher revenue in the prior year.
- The business remains loss making for the first nine months of 2026 while still affirming a quarterly dividend. This puts the earnings decline, cost pressures and capital allocation priorities into sharp focus for anyone tracking Mosaic’s balance between investment needs and shareholder returns.
- We will now look at how Mosaic’s weak quarterly earnings and cautious outlook reshape the company’s broader investment narrative.
Mosaic Investment Narrative Recap
To own Mosaic through this period, you need to be comfortable with a fertilizer producer that is currently loss making but still investing in its portfolio while managing raw material and regulatory pressures. The latest quarter keeps that tension front and center. Sales held above US$3.1b, yet the net loss of US$72.1 million and year to date loss of US$602.5 million highlight that pricing and cost pressures remain in the foreground.
The key near term swing factor is whether phosphate and potash profitability can stabilise as Mosaic works through sulfur costs and production curtailments. At the same time, the biggest risk is that weak operating cash flow, alongside ongoing capital expenditure and dividends, restricts balance sheet flexibility. If cash generation does not improve, Mosaic’s room to keep reshaping the portfolio and funding shareholder returns could narrow.
The sulfur purchasing update looks most relevant here. Mosaic has secured sulfur at US$615 per ton for Q4, which the company indicates is meaningfully below the broader market. For a phosphate producer, sulfur is a major input cost, so that pricing could support better unit economics at a time when reported net income is under pressure.
That cost position links directly to the near term catalysts and risks. Any improvement in stripping margins and free cash flow would help Mosaic fund portfolio reshaping and its declared US$0.22 quarterly dividend without stretching the balance sheet further. If input cost relief does not translate into stronger segment profitability, the concern around dividend cover, capital spending capacity and the ability to absorb further curtailments stays front of mind.
What The Longer Term Mosaic Story Implies
Mosaic's narrative projects US$13.1b revenue and US$674.0m earnings by 2029. This assumes revenue expanding at 2.4% a year and an earnings improvement of about US$1.3b from earnings today of a US$638.5m loss.
Uncover why Mosaic's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Mosaic’s working capital release as a key catalyst. Before this earnings miss, that group was modeling revenue climbing to about US$16.0b and earnings near US$1.6b by 2029, far above the consensus US$13.1b and US$674.0m. You can treat this quarter’s loss and affirmed dividend as fresh inputs and compare how your own expectations stack up against both narratives.
Explore 4 other Mosaic fair value estimates, including one that suggests as much as 118% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mosaic research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Mosaic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mosaic's overall financial health at a glance.
Looking For More Ideas Beyond Mosaic?
If Mosaic's recent update has you reassessing where to put fresh capital, it can help to line it up against other companies with different balance sheet strength, income profiles and potential re rating stories. The Simply Wall St Screener lets you quickly filter by quality, valuation and risk so you can build a watchlist that fits your own return and volatility comfort zone.
- If you want companies that combine strong fundamentals with room for a re rating, take a look at 19 high quality undiscovered gems that are already showing solid business quality but still fly under most investors' radars.
- If capital preservation sits high on your list, focus on resilience first and returns second by scanning a 31 resilient stocks with low risk scores that filters for sturdier balance sheets and more dependable financial profiles.
- If income is your priority, start building a shortlist of cash generators by reviewing a 5 dividend fortresses that concentrates on higher yielding payers with the potential to support ongoing distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com