
International Bancshares (IBOC) Holds Steady As Valuation Questions Return
International Bancshares (IBOC) is back in focus after its recent trading performance, which includes a roughly flat move over the past month and a decline over the past 3 months. This has prompted fresh questions about valuation.
At a share price of $69.02, International Bancshares has seen short term momentum firm up recently, with a 1 day share price return of 2.15% and a 7 day share price return of 3.06%, even as the 90 day share price return declined 6.16%. Taken together with a 1 year total shareholder return of 4.63% and a 3 year total shareholder return of 66.46%, this pattern highlights a contrast between recent performance and the longer multi year period, which matters for how investors frame today’s valuation conversation.
Compare International Bancshares' recent consolidation with other banks that are showing stronger price action using our curated list of list of solid balance sheet and fundamentals (24 results) for ideas beyond this ticker.
International Bancshares has built a broad regional banking franchise, yet the share price has barely moved recently after a strong multi year run. Is this still a solid bank at a fair entry point or not?
Preferred P/E of 10.4x: Is it justified?
Valuation for International Bancshares currently leans on a preferred P/E multiple, with the stock trading at 10.4x earnings while the last close sits at $69.02. That level screens as cheaper than both the peer group on 13.2x and the wider US Banks industry on 11.3x, which frames the P/E as a potential source of appeal rather than a stretch.
The P/E ratio compares what the market is willing to pay today for each dollar of earnings. For a regional bank like International Bancshares, that matters because earnings quality, balance sheet risk and growth consistency often show up more cleanly in profit than in headline revenue. A 10.4x multiple suggests investors are not assigning a premium price to those earnings, even though the firm has reported 12.2% yearly earnings growth over the past 5 years and carries a net profit margin of 49.3% on revenue of $837.6m.
That gap to peers is clear. International Bancshares trades at a lower P/E than similar banks on 13.2x and also below the US Banks industry average of 11.3x. This indicates the market is valuing the same dollar of earnings more conservatively here. The fair ratio could not be calculated, so there is no regression based target multiple to compare against. However, the discount to both peer and sector averages is still strong enough to be worth attention for investors who focus on earnings based valuation.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 10.4x (UNDERVALUED)
Still, the narrative around International Bancshares can change quickly if credit quality weakens or if funding costs compress the currently high profit margins.
Find out about the key risks to this International Bancshares narrative.
Another View: What the SWS DCF Model Says
A different lens on International Bancshares comes from the SWS DCF model, which puts future cash flow value at $139.71 per share compared with today’s $69.02 price. That suggests the stock screens as heavily undervalued on cash flows. If earnings momentum is slowing, which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
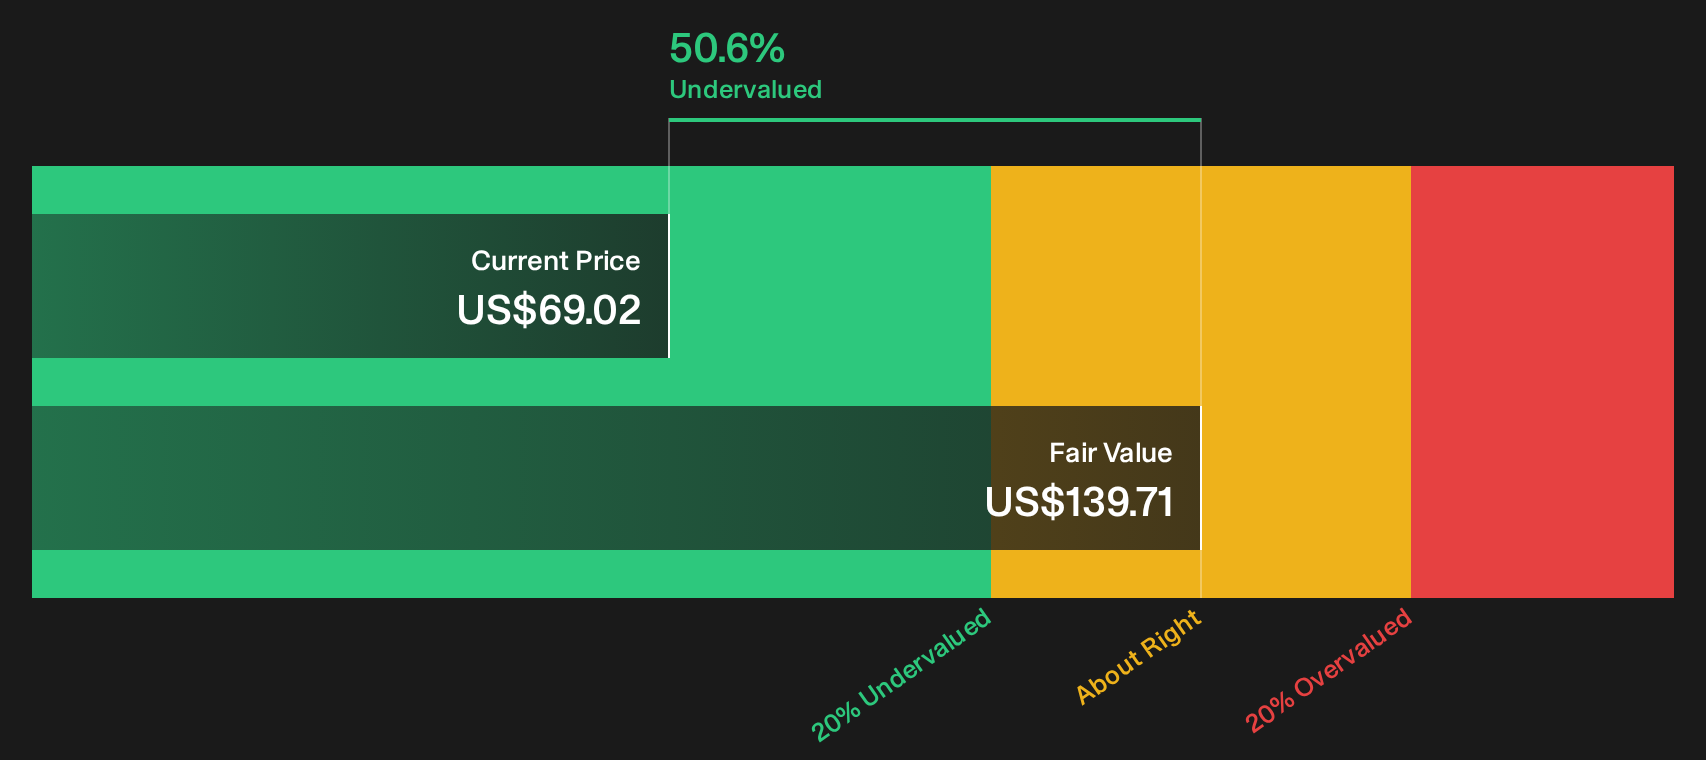
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out International Bancshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around International Bancshares can feel confusing. Move quickly, review the data for yourself, and weigh both sides of the story using the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond International Bancshares?
Do not stop with International Bancshares. Use the Simply Wall St screener to scan broader opportunities, compare quality across sectors, and sharpen your watchlist before the market moves.
- Target potential mispricings by focusing on resilient businesses that still trade at a discount with the 35 high quality undervalued stocks.
- Build a stream of income by reviewing companies that offer strong yields and financial resilience via the 5 dividend fortresses.
- Lean toward capital preservation by filtering for companies with steadier risk profiles using the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com