
Demand for AI servers withstood the question. Hon Hai's October revenue rose 45.7% year on year to a record high, with a cumulative increase of 40.4% in the previous 10 months
The Zhitong Finance App learned that Hon Hai Precision (also known as Foxconn)'s revenue jumped sharply again in October, reflecting the continued strong demand for Nvidia (NVDA.US) servers in the global wave of artificial intelligence (AI) infrastructure.
According to the data, the company's revenue for the month increased to NT$1.305 trillion (US$39.7 billion), up 45.73% year-on-year and 12.66% month-on-month, setting a record high in the company's monthly revenue over the years. In US dollars, October revenue increased 39.7% year over year and 11.4% month over month. Previously, the second-highest monthly revenue in history was NT$1.16 trillion in September and NT$895.7 billion in the same period last year (October 2025).
Cumulatively, revenue for the first 10 months of 2026 reached NT$8.975 trillion, a year-on-year increase of 40.40% (increase of 38.4% in dollar terms), which also set the highest record for the same period in history; it was NT$6.393 trillion in the first 10 months of the same period last year.
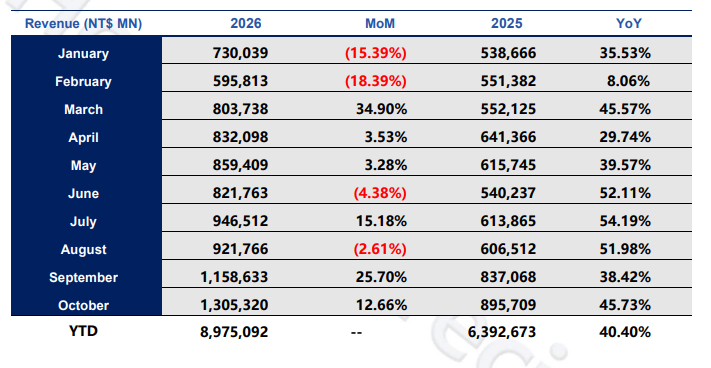
By product category (month-on-month), the consumer intelligence product category showed strong growth, driven by the momentum of pulling goods and rising shipping prices; the computer terminal product category benefited from the momentum of new product pull-up and showed significant growth; components and other product categories showed significant growth, driven by increased core components and other revenue; although AI-related demand remained strong, the cloud network product category showed a slight decline due to OEM model transformation, tight supply, and the initial rise in mass production of new models.
On a year-on-year basis, the cloud network product category showed strong growth driven by AI product pull-up momentum; consumer intelligence product categories, components and other product categories, and computer terminal product categories all showed strong growth. Among them, computer terminals benefited from rising shipping prices and pull-up momentum.
Over the past two years, the global data center construction boom has boosted Hon Hai's financial performance. Investors use the company's sales data to assess the state of the AI industry — but currently, the industry is increasingly being dragged down by overcapacity, rising debt, and regulatory concerns.
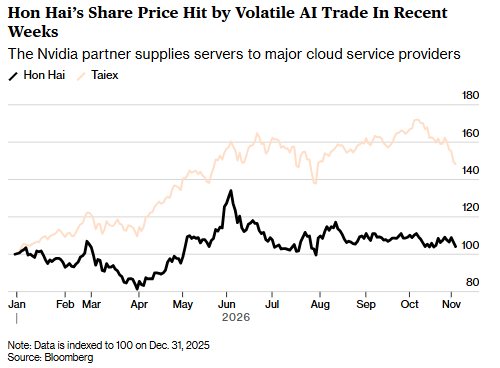
Dragged down by recent fluctuations in technology stocks, Hon Hai's gains during the year have rebounded sharply. Since the beginning of the year, the stock price has risen by only 2%.
As of now, Hon Hai still has a significant portion of its revenue from the Apple (AAPL.US) contract business, and the profit margin of this business is low. Hon Hai is the main iPhone assembly manufacturer and has assembly bases in mainland China and India; at the same time, Apple is actively decentralizing the supply chain, and manufacturers such as Lixun Precision are also accepting related orders.
Looking ahead to the fourth quarter, Hon Hai expects AI-related operations to continue to grow. Combined with the traditional peak season effects of information and communication technology (ICT) products in the second half of the year, it is expected to support overall operating performance in line with current market expectations; however, the company suggests that we still need to continue to pay attention to the impact of fluctuations in the global political and economic environment.
Analysts Steven Tseng and Rebecca Wang said that Hon Hai is expected to maintain a strong momentum in the fourth quarter after September revenue increased 38% year over year to a record NT$1.16 trillion, driving sales growth of 47% in the third quarter to NT$3.03 trillion (exceeding general market expectations of 7%). The cloud computing and networking business once again led the way with the strong performance of AI servers, and the computing and parts business also recorded strong growth. The performance of consumer electronics products remained flat, despite an increase in the average price of iPhones, which further confirmed that AI is a key growth engine. Hon Hai's strong performance will continue into the fourth quarter, thanks in part to rising Vera Rubin product shipments and favorable IT seasonality factors.