
Coupang (CPNG) Stock Looks Reasonable Following Its 44% Slump
Coupang has seen sharp swings in its share price over the past year, and the gap between those moves and its reported cash generation has come into sharper focus. With the stock now trading around US$17.05, the key question is whether that market value lines up with what the business is expected to produce in future cash flows.
- Over the past 12 months the share price has fallen 43.6%, which puts extra weight on whether the current valuation can be explained by the cash the company is expected to generate.
- Recent results included US$10b of revenue alongside a net loss of US$501m linked in part to fire related costs, which keeps the spotlight on how quickly Coupang can translate its scale into more durable cash inflows.
- Prefer to judge Coupang on sales? See what Coupang's 0.8x P/S says about the price.
The issue now is whether Coupang's recent share price level is supported by its intrinsic value estimate based on the Discounted Cash Flow (DCF) view of its cash flows.
If you are weighing whether Coupang's recent share price swings line up with its cash flows, a focused stock screen built around 35 high quality undervalued stocks can give you another useful starting point for comparison.
Does Coupang Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) approach here looks at the cash that Coupang could generate for shareholders over time and then discounts it back to today. Coupang is coming off last twelve month free cash flow of about $350 million outflow, so the model leans heavily on a recovery path that moves from current investment and loss making into sustained positive cash generation.
Analysts feeding into this DCF are assuming free cash flow reaches well above $1b annually within a few years, which is a big swing from the recent outflow and makes the result particularly sensitive to execution. The recent report of $10b in quarterly revenue alongside a $501 million net loss, partly tied to fire related costs, helps explain why the market keeps the share price around $17.05 even though the DCF projections put Coupang's estimated intrinsic value substantially above the current share price. Find out what Coupang could be worth using our Discounted Cash Flow (DCF) estimate.
The Coupang Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Coupang valuation puzzle leaves off by spelling out the growth, margin and earnings paths that would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Each narrative ties a fair value to a clear storyline about Coupang's potential catalysts and key risks so you can later judge which version of events is actually unfolding.
Bullish holders of Coupang see the margin story very differently from those focused on regulatory costs and overseas losses.
Bull case: 27% undervalued
"Ongoing investments in automation, AI, and logistics technology are already driving major improvements in operational efficiency and gross margins..."
Discover why this Narrative puts Coupang at 27% undervalued.
Bear case: 14% overvalued
"Despite ongoing net losses, large regulatory fines and guided Developing Offerings adjusted EBITDA losses of between US$950 million and US$1.0b in 2026, Coupang is committing billions of dollars to share repurchases..."
Explore why this Narrative puts Coupang at 14% overvalued.
One more Coupang signal that could reshape your view
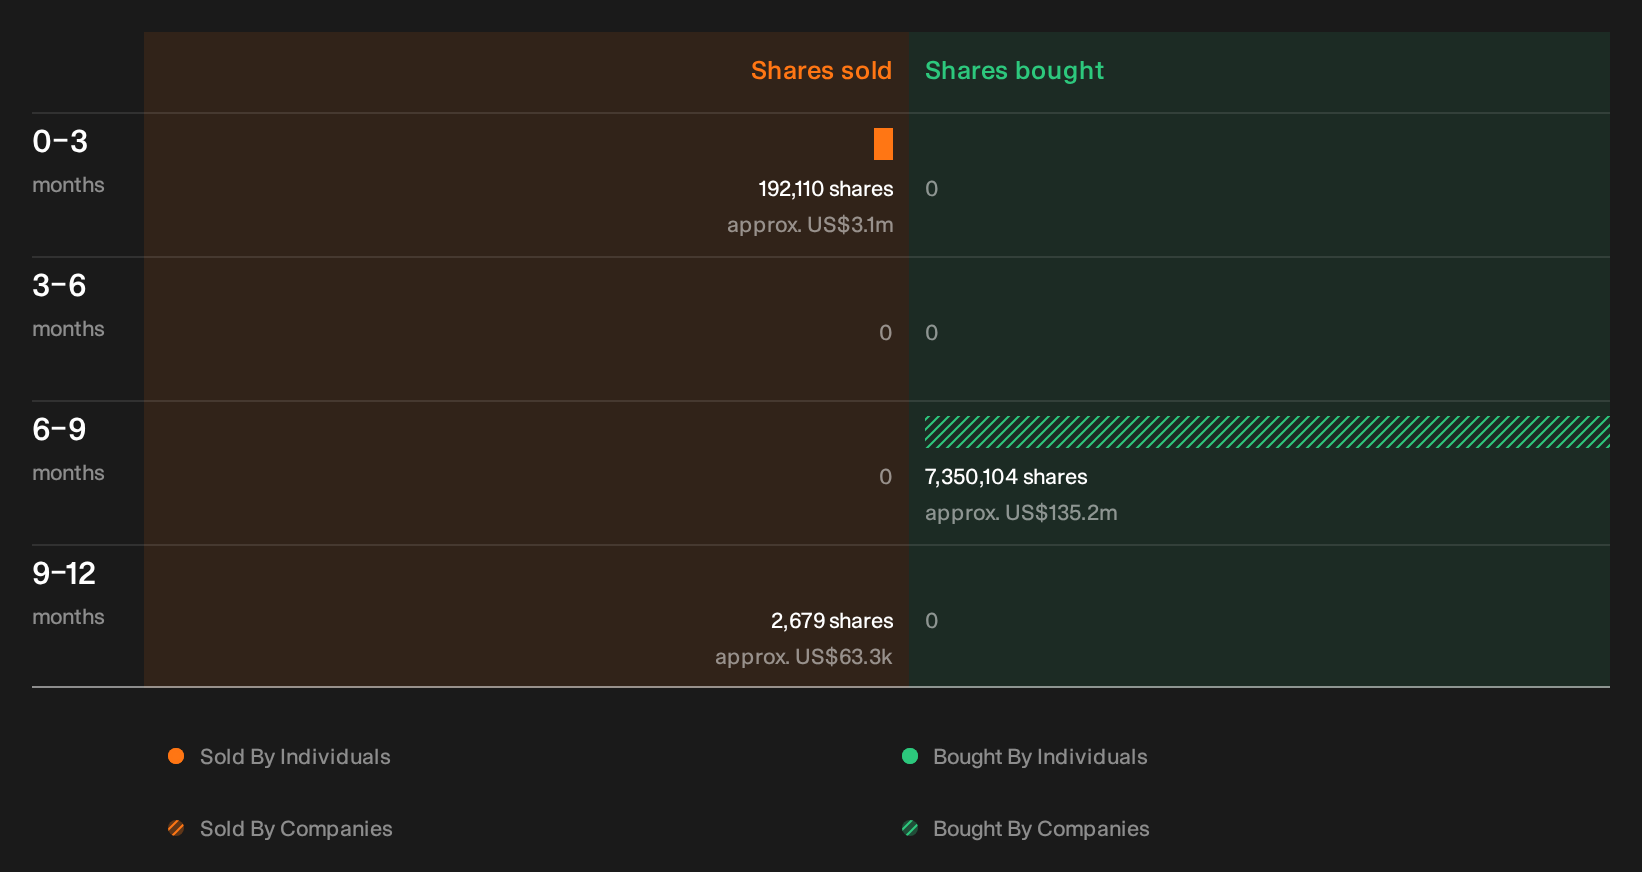
Before you lean too heavily on any valuation work for Coupang, it is worth knowing that recent insider share activity has been flagged by our checks, with the specific sellers, sizes and possible readthroughs still to unpack. See the recent insider selling flagged for Coupang.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com