
Is Barratt Redrow (LSE:BTRW) Undervalued After Citi's Downgrade And Rate Decision Focus?
Citi’s downgrade of Barratt Redrow (LSE:BTRW) on concerns over slower margin recovery has put the stock under closer scrutiny, just as investors watch the Bank of England’s upcoming interest rate decision.
Recent trading shows a mixed picture for Barratt Redrow. The 1 day share price return of 2.82% and 30 day gain of 6.18% suggest short term momentum is rebuilding. However, the year to date share price performance is down 13.46% and the 5 year total shareholder return has fallen 35.20%. This points to a longer running reset in expectations as investors weigh margin risks against interest rate headlines.
Scan how Citi’s downgrade of Barratt Redrow compares with peers facing similar margin and rate pressures by reviewing our hand picked 5 resilient stocks with low risk scores in rate sensitive sectors.
After Citi’s downgrade and a share price still down sharply over longer periods, Barratt Redrow now sits in awkward territory. Do you treat this as an early reset opportunity, or wait for a clearer entry after the next data point and rate call?
Most Popular Narrative: 2% Undervalued
On the most followed view of Barratt Redrow, the fair value of £3.36 sits only slightly above the latest close at £3.28. This view places greater emphasis on synergy delivery and cash returns rather than on a rapid recovery in margins.
The combination of Barratt Redrow and Redrow has moved from identifying to delivering the targeted £100m of annual cost synergies, with about £73m already reflected in FY26 results and around £95m expected to flow through the FY27 income statement, which directly supports net margins and earnings.
See why 71 investors see Barratt Redrow as 2% undervalued.
Result: Fair Value of £3.36 (UNDERVALUED)
Still, the Barratt Redrow story can be knocked off course if build cost inflation squeezes margins further or if building safety cash outflows drag harder on free cash flow.
Find out about the key risks to this Barratt Redrow narrative.
Another View: Barratt Redrow Through A Cash Flow Lens
The earlier fair value narrative paints Barratt Redrow as only 2% undervalued at £3.36. A different tool, the SWS DCF model based on estimated future cash flows of £2.05 per share, points the other way and implies the shares trade above that value.
This gap between earnings based fair value and cash flow based fair value leaves you with a practical question. Do you lean more on headline earnings and buybacks, or treat the cash flow signal as a sign to demand a wider margin of safety before acting on Barratt Redrow?
Look into how the SWS DCF model arrives at its fair value.
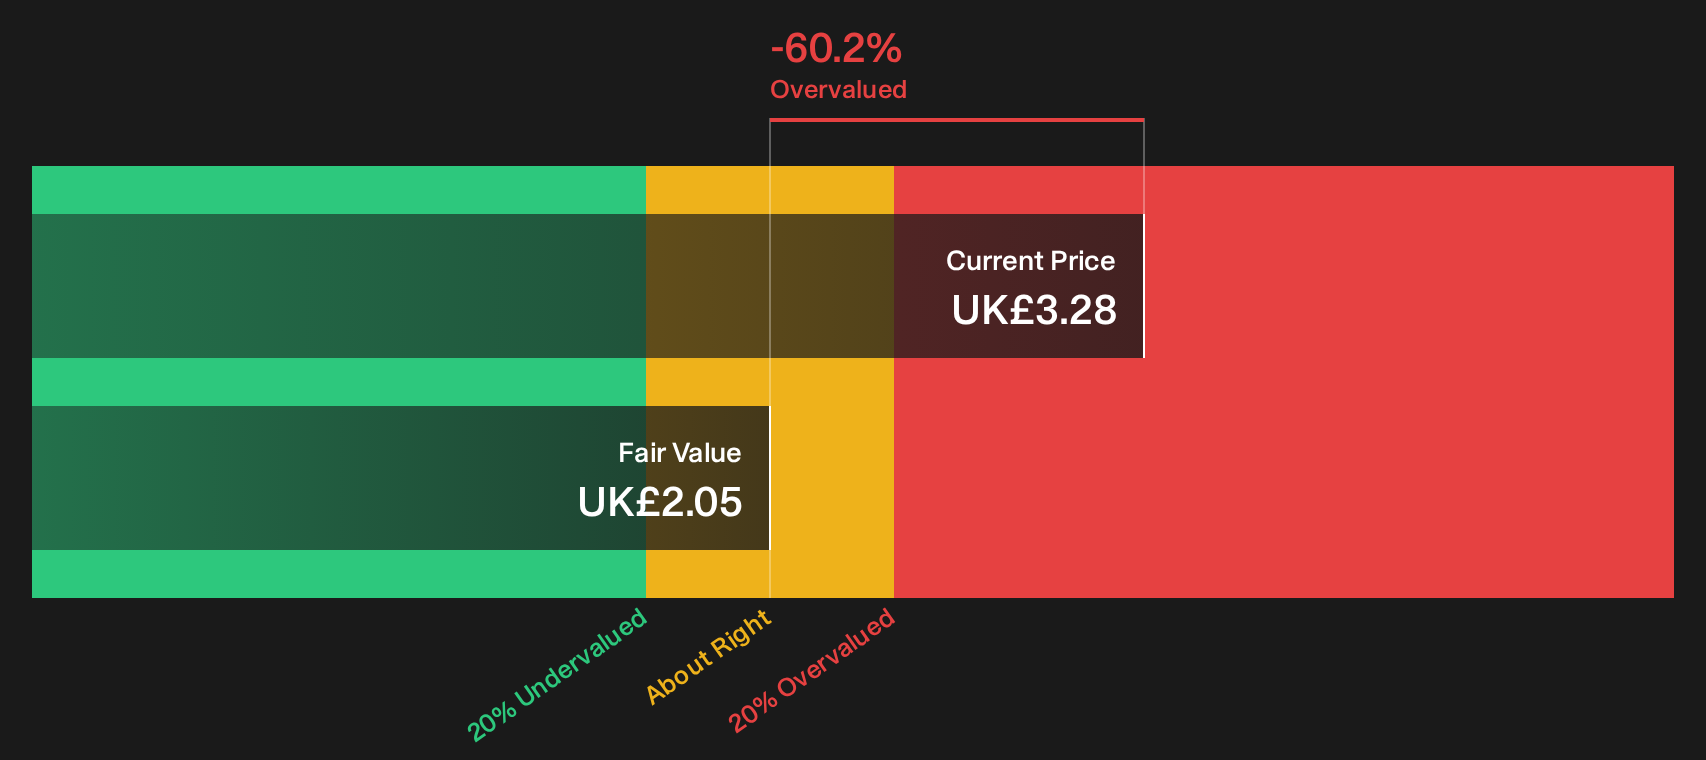
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Barratt Redrow for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Barratt Redrow can feel confusing, so move quickly from headline takes to your own verdict by weighing the 2 key rewards.
Looking for more ideas beyond Barratt Redrow?
You have weighed Barratt Redrow. Now put that same discipline to work by scanning fresh opportunities with the Simply Wall St stock screener before the market moves without you.
- Target resilient potential by reviewing companies with strong finances and lower risk profiles through our 5 resilient stocks with low risk scores.
- Hunt for quality at a discount by checking the 14 high quality undervalued stocks that match solid fundamentals with attractive pricing.
- Build a watchlist of emerging opportunities by scanning the 5 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com