
Excelerate Energy (EE) Earnings Resilience Keeps Fair Value In Focus
Excelerate Energy (EE) just posted third quarter 2026 results that paired lower reported revenue of US$297.21 million with slightly higher net income of US$14.23 million and earnings per share essentially holding steady.
Excelerate Energy’s latest earnings update landed just days after the board affirmed a quarterly dividend of US$0.09 per Class A share, and the share price at US$34.29 now reflects a mixed pattern, with a 1 day decline of 2.39% but a year to date share price return of 21% and a 3 year total shareholder return of 136.29% that signals momentum has been building over a longer horizon.
Explore curated peers that resemble Excelerate Energy’s combination of cash generation, dividend income and infrastructure exposure by using our 5 dividend fortresses to find ideas with similar yield and resilience characteristics.
After a 136.29% three year total return and a 21% gain year to date, the real puzzle around Excelerate Energy now is simple: Is most of the upside already in the price, or not yet reflected in it?
Most Popular Narrative: 21% Undervalued
Excelerate Energy’s most followed valuation narrative pegs fair value at about $43.46, which sits well above the latest close at $34.29 and puts the recent share price gains into a different light for anyone focused on long term cash flows.
The sequenced rollout of the integrated Iraq LNG import terminal in early Q2 2027 and the Methane Patricia Camila FSRU conversion targeted for early 2028, with management citing expected 5x to 7x unlevered build multiples on the conversion, creates a visible project queue that can support higher adjusted EBITDA beyond current guidance.
See why 13 investors see Excelerate Energy as 21% undervalued.
Result: Fair Value of $43.46 (UNDERVALUED)
Still, Excelerate Energy’s thesis leans heavily on LNG remaining attractive despite decarbonization efforts and on large capex projects not ending up as underused assets.
Find out about the key risks to this Excelerate Energy narrative.
Another View: Excelerate Energy On Earnings Multiples
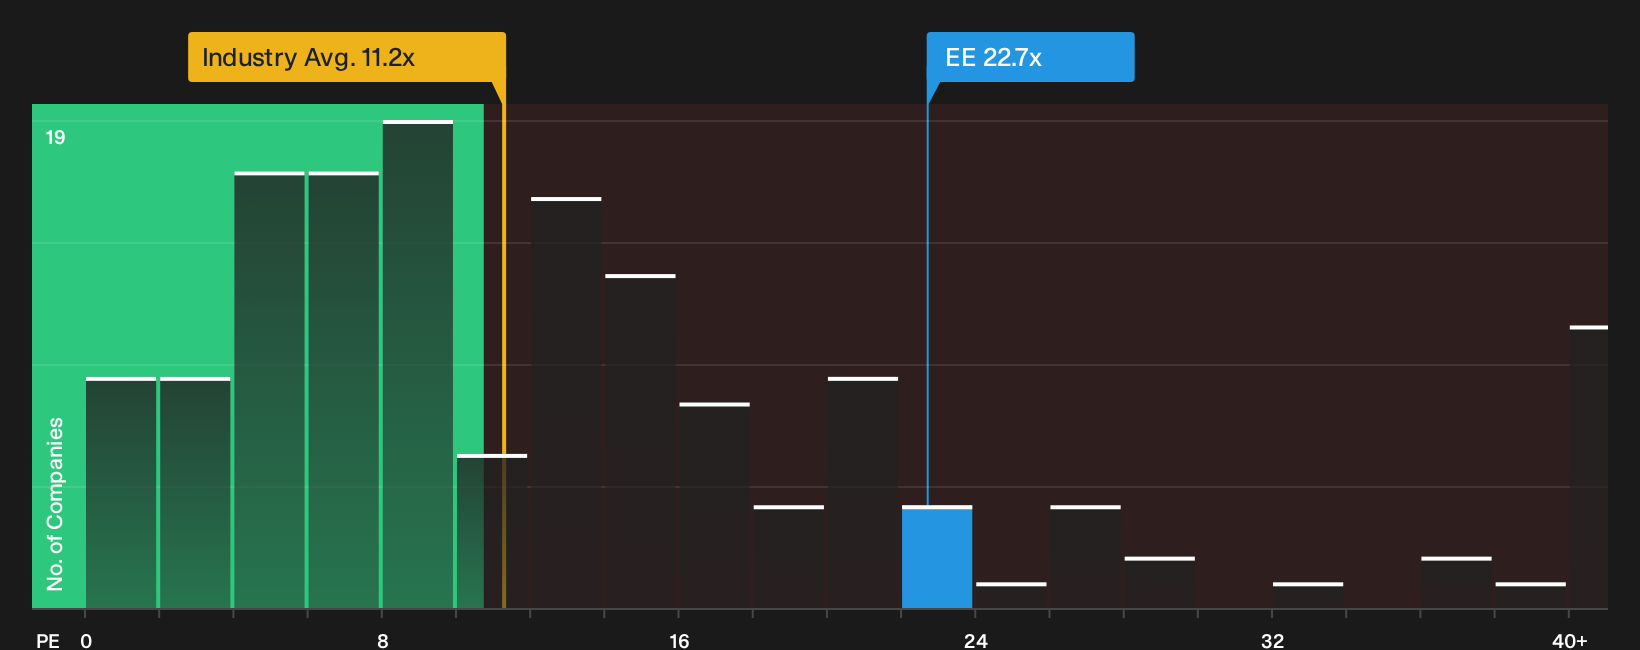
The first narrative on Excelerate Energy leans on future cash flows and a fair value of $43.46. A simple P/E check tells a different story. EE trades at 22.7x earnings, which is well above the US Oil and Gas group on 12.3x and peers on 9.4x, and also above a fair ratio of 18x that the market could move toward. That premium points to less margin for error if growth or LNG projects disappoint, so the key question is whether you think the higher multiple is earned or just hopeful.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and caution around Excelerate Energy leaves you on the fence, move quickly to review the underlying data and pressure test the narratives against your own expectations. To understand what favourable factors others are watching, start with the 4 key rewards.
Looking for more investment ideas beyond Excelerate Energy?
Do not stop your research at Excelerate Energy. Fresh ideas often come from comparing different businesses, sectors and balance sheet profiles side by side.
- Target higher quality potential opportunities first and let the numbers filter for you with the 35 high quality undervalued stocks.
- Lower the chance of nasty surprises by focusing on sturdier finances using the list of solid balance sheet and fundamentals (24 results).
- Spot early stage opportunities with stronger fundamentals before the crowd pays attention by checking the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com