
What Greencore Group Doubters Missed
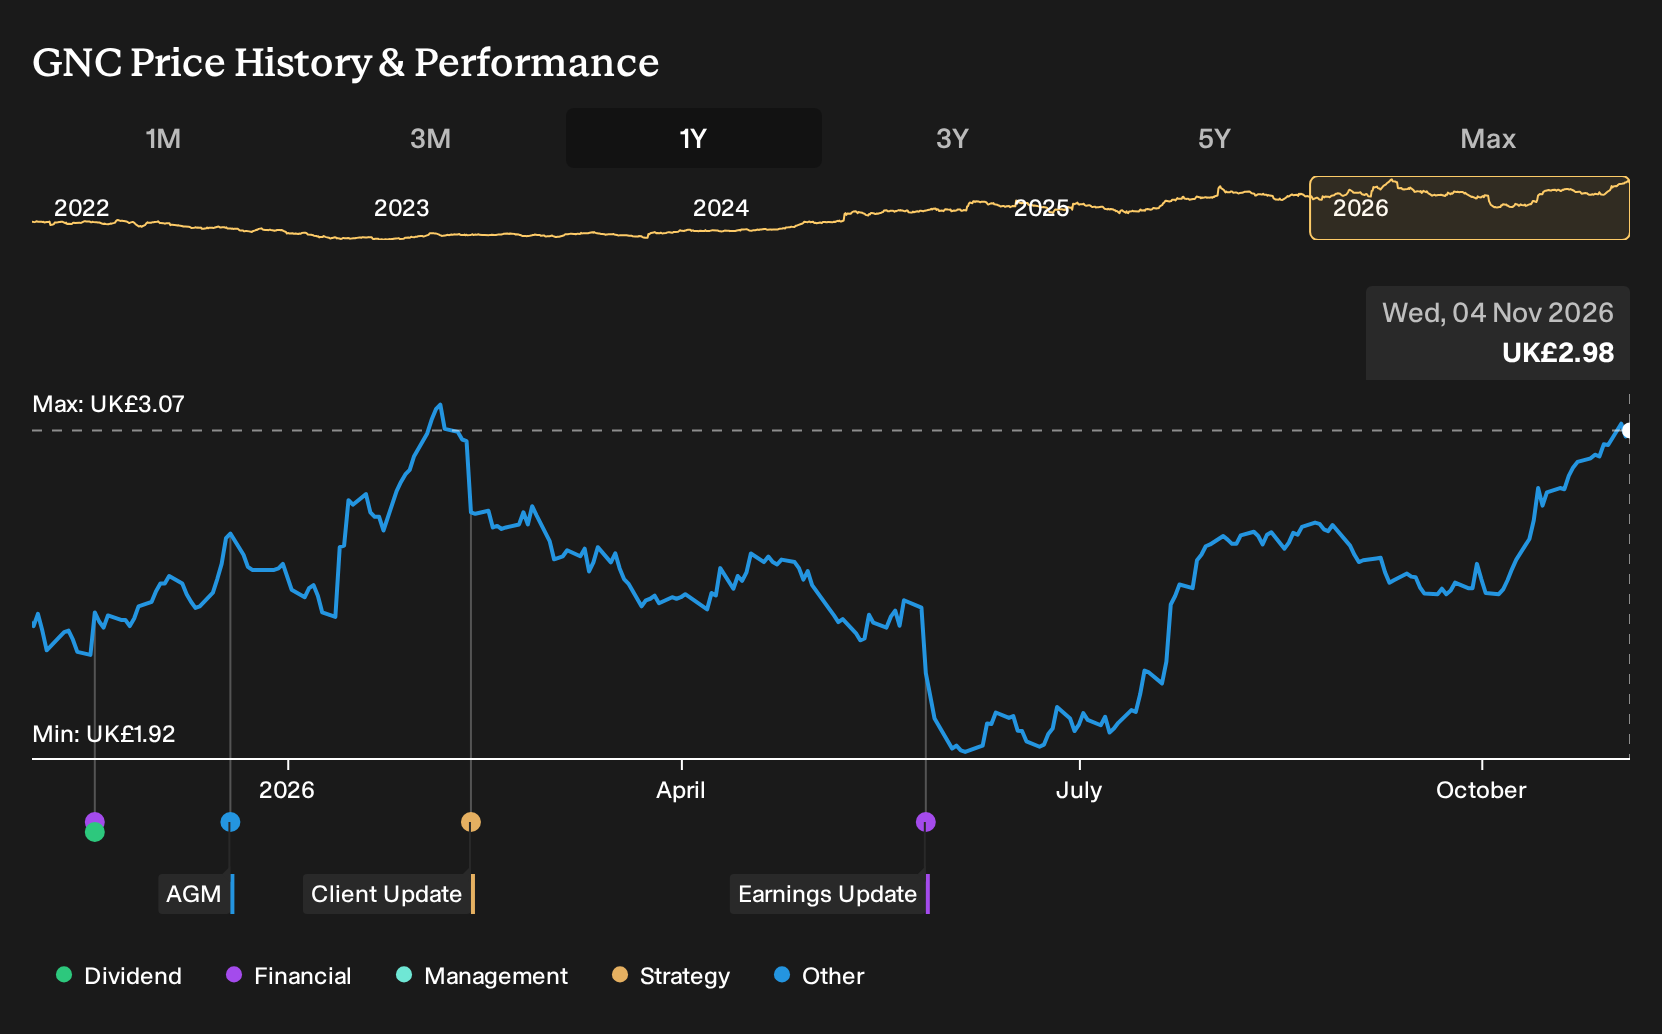
If you had put money into Greencore Group a year ago, the decision now looks very different on paper. For Greencore Group shareholders, the return over the past year was 26.8%, including dividends. That outcome sits between a bullish case that saw efficiency gains and contract renewals, and a bearish view focused on margin strain, regulation, and acquisition risk. If you were weighing those opposing views in November 2025, which parts of the story would have mattered most?
If the move has made Greencore Group harder to judge, start where the gap is still open and scan 14 high quality undervalued stocks.
The Argument Greencore Investors Faced Back Then
The shares cost £2.33 at the start of the period, and anyone looking at Greencore Group then had to choose between two very different but plausible stories.
On the optimistic side, the Making Business Easier program underpinned a Fair Value of £2.56, a price those assumptions implied. Backers of this view focused on technology driven cost reductions and smoother operations improving efficiency.
The cautious camp worked off a Fair Value of £1.85 and worried about rising labor costs and regulatory pressure. That weaker case leaned on the risk that higher National Insurance Contributions and extra compliance demands would squeeze profitability.
What The Results Changed For The Greencore Group Debate
Fresh evidence came when Greencore lifted its profit guidance again, pointing to volume growth ahead of the sector and early progress integrating Bakkavor. That update leaned toward the optimistic efficiency story. The later H1 2026 numbers pulled the other way. Revenue reached £1,318m, yet net income swung from £19.8m profit to a £34.8m loss and net margin moved to -2.6%. Overall, the period cut both ways.
The hinge assumption here was that efficiency and acquisitions would improve profitability. When you assess another food producer, compare any promised cost or volume gains with the reported net margin and profit trend after a big program or deal lands.
What Greencore's Current Price Already Assumes
Greencore Group now trades at £2.98, with this Narrative’s Fair Value sitting below that level. The gap rests on the idea that recent earnings and cash generation may not fully align with the headline revenue story.
For the current price to stack up, you would need to judge whether Greencore can keep turning Bakkavor synergies and Making Business Easier initiatives into sustained margins, despite cash strain and inflation pressure.
"Although Greencore Group reports structural tailwinds in UK convenience and premium eat at home formats, the recent description of a tough and subdued grocery backdrop with flat grocery volume growth and very limited volume gains of 0.3% to 0.8% raises the risk that category growth fails to translate into stronger unit volumes. This could cap revenue and pressure earnings if pricing power weakens."
The price and this Narrative do not agree. → Uncover what this Narrative says Greencore Group is actually worth
Go Straight To The Source
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 18% below our estimate - targets lawyers leaving partnerships for a tech enabled fee sharing platform.
- Company 2 - 25% below our estimate - builds a single tech stack pulling more assets onto one low cost platform.
- Company 3 - 28% below our estimate - channels capital into fee based access to renewable energy and infrastructure assets.
That is three of the list. See the full list of 10 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com