
Synaptics (SYNA) Files Shelf Registration, Is The Stock Still Undervalued?
Synaptics (SYNA) has filed a US$117.41 million shelf registration for 1,000,000 common shares tied to an employee stock ownership plan, putting potential equity issuance on investors’ radar as they assess dilution and liquidity.
Against that filing backdrop, Synaptics’ recent share price return has cooled slightly in the very near term. The 7-day share price return is 0.85% and the 30-day share price return is down 1.87%. However, the 90-day share price return of 15.07% and year-to-date share price return of 55.12% point to momentum that has already been strong for much of 2026. At the same time, the 1-year total shareholder return of 67.44% contrasts with a more modest 3-year total shareholder return of 32.55% and a 5-year total shareholder return that is down 52.52%, suggesting long-term holders have had a bumpier journey than recent entrants.
Compare Synaptics’ recent momentum and dilution risk against a hand picked group of resilient tech stocks screened for strong fundamentals in our list of solid balance sheet and fundamentals (24 results)
Synaptics has surged in 2026 while long term returns are still catching up, and fresh ESOP linked shares are now in the mix. Does that setup favor buying today or waiting for a cleaner entry on valuation?
Most Popular Narrative: 10% Undervalued
Against Synaptics’ last close of $117.49, the most followed narrative puts fair value at about $130.33, so the market is pricing in a clear discount that hinges on how edge AI and Core IoT play out.
The launch and initial customer traction of native Edge AI processors (Astra family, featuring Google Research collaboration and neural transformer support) targets the growing shift toward on-device processing for AI workloads, potentially establishing Synaptics as a key supplier for next-gen IoT applications and improving both revenue growth and product differentiation. The company's strategy to bundle highly integrated solutions combining wireless connectivity, low-power mixed-signal processing, and embedded AI/software content is expected to increase silicon content per device and drive higher gross margins as more revenue is captured per customer design win.
See why 16 investors see Synaptics as 10% undervalued.
Result: Fair Value of $130.33 (UNDERVALUED)
Still, the story around Synaptics can change quickly if the all stock On Semi deal stalls, or if competition pressures the edge AI and Core IoT roadmap harder than expected.
Find out about the key risks to this Synaptics narrative.
Another View On Synaptics: Cash Flows Paint A Tougher Picture
That 10% discount to the $130.33 fair value hinges on analyst targets and profit expectations. A second lens tells a different story. The SWS DCF model estimates Synaptics shares are worth about $81.45, which implies the current $117.49 price screens as expensive rather than cheap.
This gap between a target based fair value and a cash flow based estimate raises a practical question for investors. Is the market fairly paying up for Synaptics exposure to edge AI and Core IoT narratives, or is it leaning too far ahead of the cash that the business is currently expected to generate?
To see how the cash flow view is built and what assumptions sit underneath it, take a closer look at the SWS DCF model output for Synaptics via Look into how the SWS DCF model arrives at its fair value.
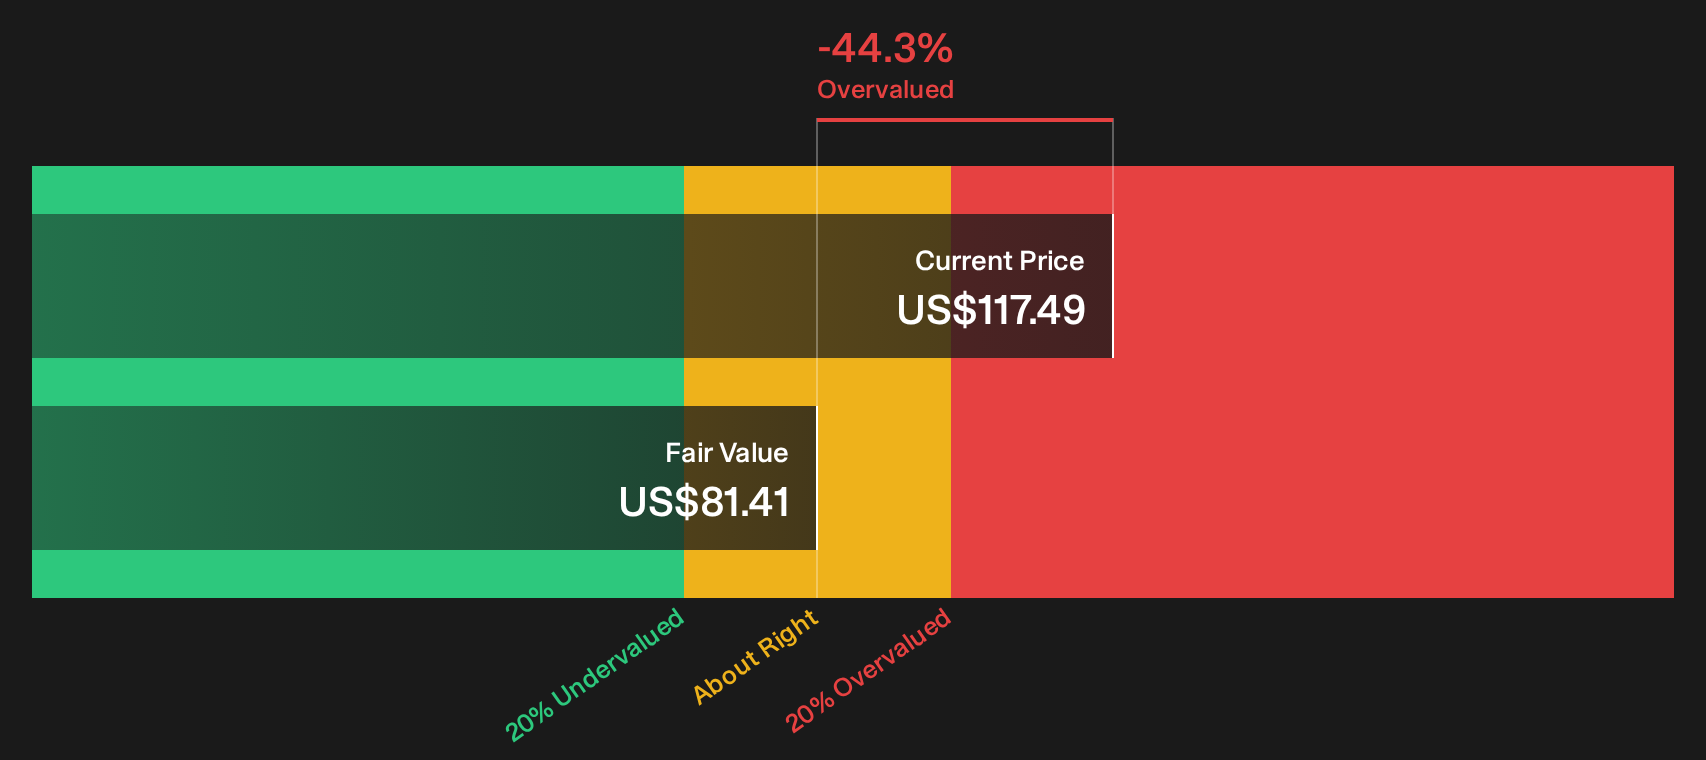
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Synaptics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Synaptics can either feel exciting or uncomfortable, and both reactions are valid. Act quickly on your curiosity and review the company’s key strengths and pressure points with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Synaptics?
If Synaptics has your attention, do not stop here. Broaden your watchlist and pressure test your thesis against other opportunities before the next move catches you off guard.
- Target resilient balance sheets and solid fundamentals by scanning a curated list of solid balance sheet and fundamentals (24 results) that can help anchor your portfolio when conditions change.
- Hunt for strong businesses that trade at a discount using the focused 35 high quality undervalued stocks so you are not relying on a single potential bargain.
- Build a watchlist of potential future leaders early by tracking the 19 high quality undiscovered gems before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com