
Porch Group (PRCH) Earnings Swing Puts Fair Value Back In Focus
Porch Group (PRCH) is back in focus after its latest quarterly update showed higher sales and a swing to profit, with net income of US$12.19 million for the third quarter of 2026.
Investors have responded quickly to Porch Group's profit swing, with the stock posting a 32.3% 7 day share price return and a 39.6% 90 day move, while the 1 year total shareholder return of 35.1% compares with a very large 3 year total shareholder return that signals strong, extended momentum.
Scan for other Porch Group style momentum stories by checking stocks in the 19 high quality undiscovered gems that have recently turned profitable and attracted the market's attention.
The rally and fresh profit have pushed Porch Group closer to analyst targets, yet the shares still trade at a reported discount to fair value. Is that a genuine opportunity, or the market pricing in real risk?
Most Popular Narrative: 9.9% Undervalued
Porch Group's most followed valuation story pegs fair value at about $23.93, compared with a last close of $21.56. This puts the current rally in the context of an equity that screens as below this narrative fair value while still priced near analyst targets.
The company is investing in expanding its Vertical Software and data businesses, with initiatives such as new product launches and increased sales and product investments poised to drive faster revenue growth in 2026 and beyond. The introduction and expected growth of Home Factors, a data product which aids in risk selection and pricing, present new revenue opportunities and could significantly enhance the value of Porch Group's data segment, thereby impacting future revenue growth.
See why 8 investors see Porch Group as 10% undervalued.
Result: Fair Value of $23.93 (UNDERVALUED)
Still, Porch Group's shift to a commission and fee-based insurance model, along with the pending Allied Trust acquisition, introduces execution and integration risks that could unsettle this valuation story.
Find out about the key risks to this Porch Group narrative.
Another View: Porch Group On Sales Based Valuation
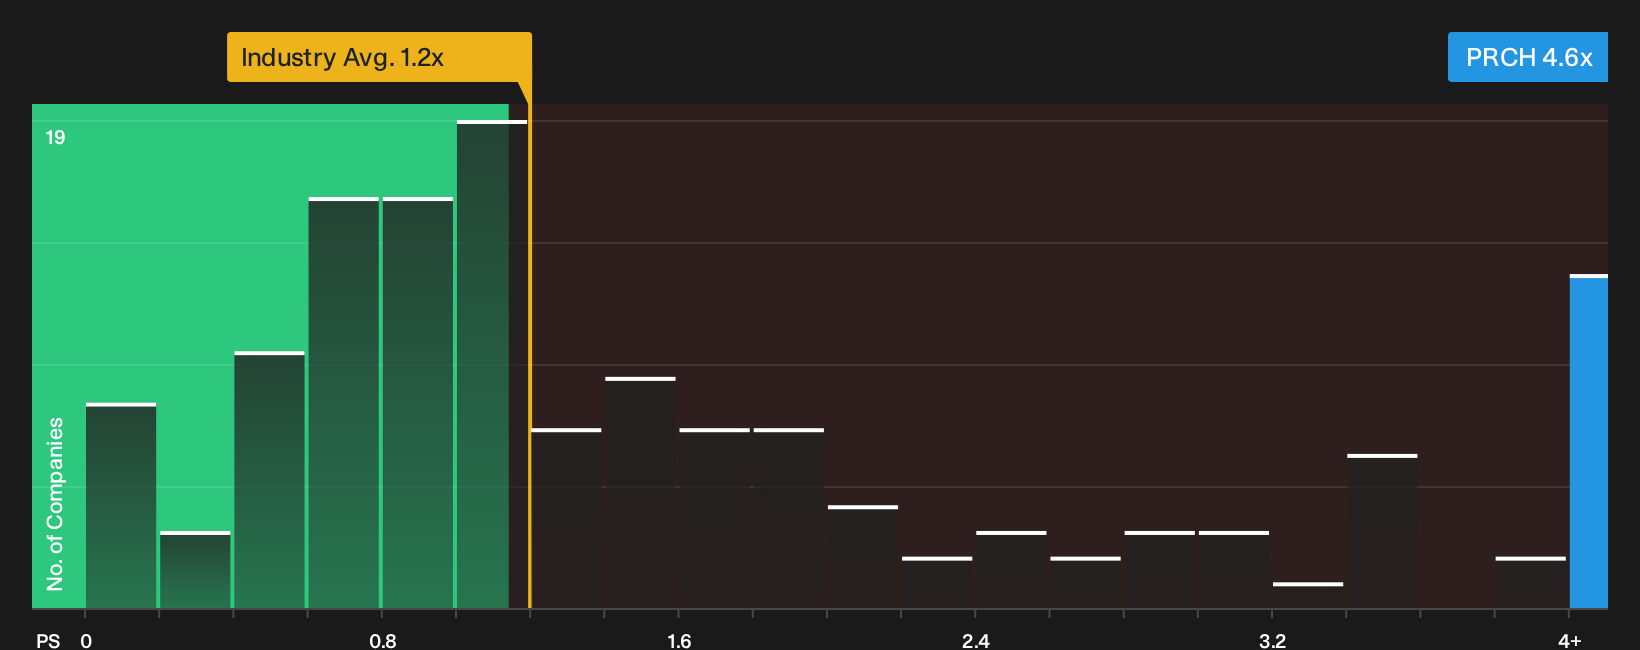
The fair value story based on projected earnings and analyst targets paints Porch Group as 9.9% undervalued, yet the picture looks very different when you just look at what investors are paying for revenue today. On a P/S ratio of 4.6x, the stock trades at more than double its own fair ratio of 2.1x and far above the US Insurance sector at 1.2x and peer average of 1.4x. That rich sales multiple suggests less room for error than the headline discount might imply. This raises an important question: which signal deserves more weight when growth or margins change?
To pressure test whether the current sales multiple leaves any margin of safety, weigh it against our valuation breakdown and how similar insurers are priced through the cycle. Then consider what would need to go right to justify this gap in real cash terms over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Porch Group's value story can pull sentiment in both directions, so consider acting promptly and evaluate the data yourself against your own risk tolerance, using the balance of 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Porch Group?
If Porch Group has sharpened your focus, do not stop here. The best opportunities often sit one layer beyond the obvious story.
- Target stronger value potential by scanning companies that combine quality fundamentals with discounted prices using the 35 high quality undervalued stocks.
- Protect the downside first and hunt for resilience with the 31 resilient stocks with low risk scores that filters for sturdier, lower risk profiles.
- Upgrade portfolio quality by zeroing in on financially robust businesses through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com