
Is Eton Pharmaceuticals (ETON) Stock Too Stretched To Stay Reasonable?
Eton Pharmaceuticals has seen its stock price move a long way in recent years, which naturally raises a simple question for investors who care about fundamentals. Is the current share price still aligned with what the business is earning today and what its earnings may reasonably support over time?
- Over the past 3 years the stock has climbed more than 10x, which puts a lot of weight on whether Eton Pharmaceuticals' earnings profile can support such a step up in market value.
- The new ET-900 program around mecasermin for infantile and epileptic spasms may support expectations for future earnings and cash generation, while also concentrating more of the company's valuation on the eventual clinical and commercial outcomes of this project.
- Your read on Eton Pharmaceuticals is one view; the desks covering it have another. See what analysts think Eton Pharmaceuticals's shares could be worth.
The issue now is whether Eton Pharmaceuticals' current valuation is justified by its earnings power once you look past the recent share price run and pipeline headlines.
If you want more ideas that start with earnings power rather than hype, a focused stock screen built around 35 high quality undervalued stocks can be a useful next step in your research.
Has Eton Pharmaceuticals Run Too Far on Earnings?
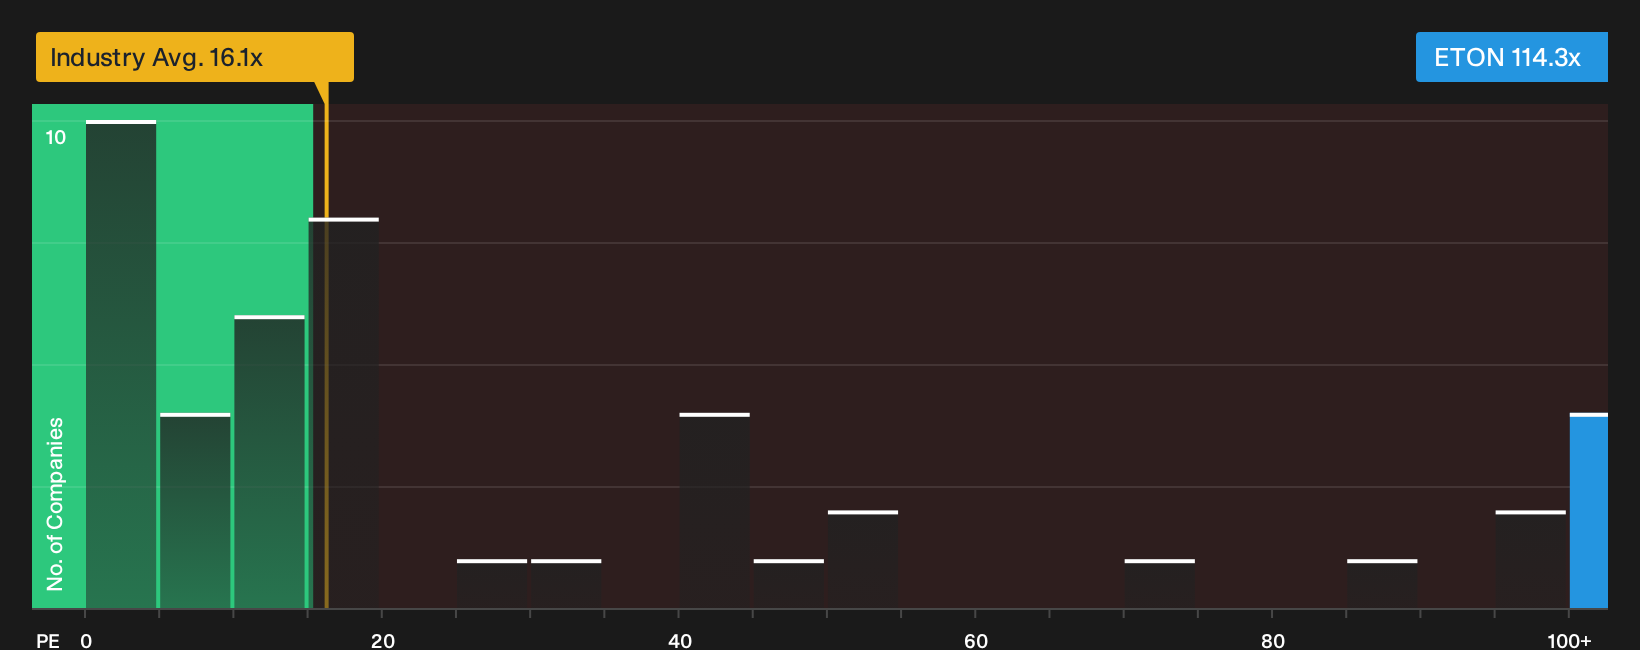
The P/E ratio fits Eton Pharmaceuticals because earnings sit closest to what you, as a shareholder, actually own in the business. On this yardstick, the stock trades on about 114.3x earnings, which is significantly higher than the wider Pharmaceuticals industry at roughly 16.1x and also well above the peer group average near 33.7x. That puts a lot of expectation into every dollar of profit the company currently generates.
The fair multiple implied by a more tailored model, which factors in Eton Pharmaceuticals' growth outlook, margins, size and risk profile, sits well below the present 114.3x. The gap is so wide that the framework effectively flags the shares as screening very expensively rather than pointing to a precise "right" P/E. Because the ET-900 program has sharpened attention on the pipeline since the licensing news, this elevated valuation means you are paying a premium that bakes in a generous outcome from that project. Explore the numbers behind Eton Pharmaceuticals's P/E valuation.
The Eton Pharmaceuticals Narrative: What Would Justify Today's Price?
Narratives for Eton Pharmaceuticals give you a clearer link between that rich P/E multiple and the future that would need to play out on growth, margins and earnings for the stock to be worth a lot more or a lot less than it is today, all housed on Simply Wall St's Community page. Where a single ratio or model offers one output, Narratives unpack the earnings path behind it so you can watch over time whether those assumptions actually hold up in reality.
One of the top community narratives on Eton Pharmaceuticals: 29% undervalued
"Eton's investments in digital patient support platforms, targeted education campaigns, and specialist distribution are removing historical barriers to access and supporting higher therapy adoption..."
Discover why this Narrative puts Eton Pharmaceuticals at 29% undervalued.
Eton Pharmaceuticals’ valuation still leaves one big piece of the story unanswered
Price multiples tell you what investors are willing to pay today, but the projections a few years out show what others expect this business to be earning. Explore where analysts expect Eton Pharmaceuticals to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com