
TriMas (TRS) Could Be 12% Undervalued As Stronger Q3 Earnings Reset The Story
TriMas (TRS) paired a stronger third quarter with fresh full-year guidance, outlining GAAP diluted earnings per share of $1.06 to $1.13 for 2026 and reaffirming its regular dividend.
TriMas shares now trade at $39.40, with the 1-year total shareholder return of 21.38% outpacing the 8.57% year-to-date share price return. This suggests dividends and reinvested payouts have been a meaningful part of the story, while shorter-term price momentum has softened after the recent earnings and dividend announcements.
Scan beyond TriMas and see how it stacks up against a hand picked 35 high quality undervalued stocks that are pairing earnings power with shareholder returns.
TriMas just paired stronger earnings with fresh guidance, yet the share price has cooled over the past quarter. Is this an early entry worth considering now, or does it make more sense to wait for a lower price before stepping in?
Most Popular Narrative: 12% Undervalued
TriMas last closed at $39.40 while the most followed narrative anchors fair value at $45, which implies the valuation case now leans heavily on how management uses its Aerospace sale proceeds and executes on cost savings.
The main thing that has to go right is that TriMas successfully deploys its more than US$1.2b of Aerospace divestiture proceeds into disciplined M&A, share repurchases, and organic investments, while delivering the planned US$15 to 16m of annual cost savings and improved execution at Norris Cylinder.
See why 1 investors see TriMas as 12% undervalued.
Result: Fair Value of $45 (UNDERVALUED)
Still, this thesis becomes fragile if TriMas falls short on its US$15 to 16m cost savings plan, or if Norris Cylinder’s operational issues drag on profitability.
Find out about the key risks to this TriMas narrative.
Another View: TriMas Through A Cash Flow Lens
The first narrative leans on a $45 fair value anchor. A different tool, the Simply Wall St DCF model, points the other way and estimates TriMas’ future cash flows at about $4.52 per share, which implies the stock price of $39.40 screens as expensive rather than cheap.
These are two stories for one ticker. The question for you is which set of assumptions feels closer to how TriMas will actually convert earnings into cash over time, and how much valuation risk you are comfortable holding if that cash flow path falls short of expectations.
Look into how the SWS DCF model arrives at its fair value.
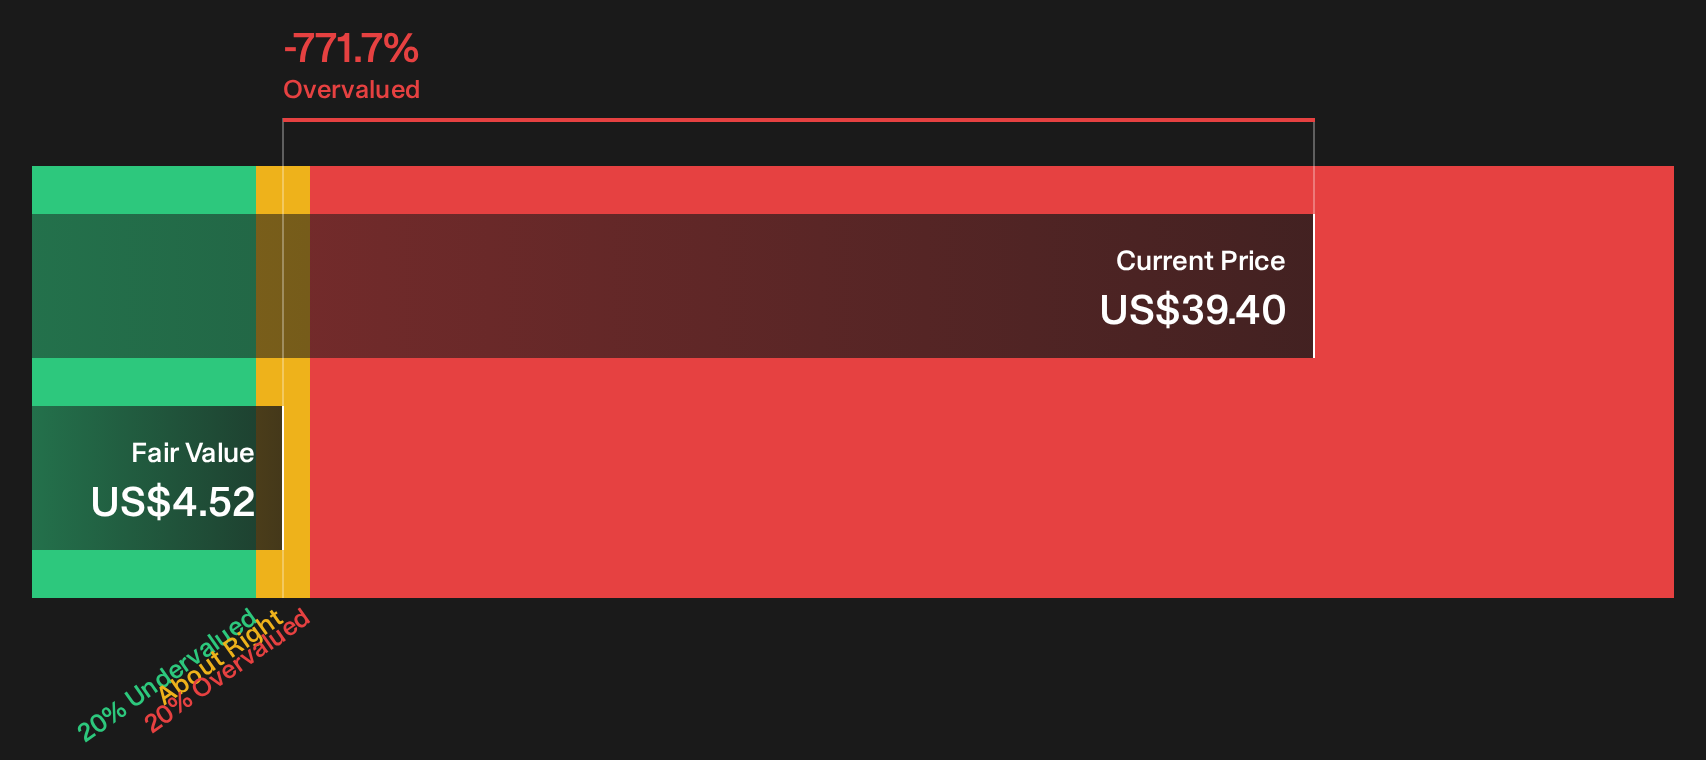
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TriMas for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on valuation and cash flows can make TriMas tough to pin down at a glance, so move quickly and pressure test the data yourself. To see both the upside case and what could go wrong in one place, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond TriMas?
If TriMas has your attention but you want a broader watchlist, use the Simply Wall St screener to quickly surface other opportunities that fit your style.
- Target dependable cash generators by scanning for companies with resilient balance sheets and steady fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispriced opportunities by focusing on businesses that pair quality with attractive pricing through the 35 high quality undervalued stocks.
- Explore potential income opportunities by filtering for companies offering dividend payouts with the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com