
PTC Therapeutics (PTCT) Stock Could Be Near Fair Value Today
PTC Therapeutics has delivered a very strong 3 year share price run, yet recent setbacks this year and fresh corporate moves put the focus squarely on what investors are paying for its sales today. With the stock now trading around US$68.97, the key issue is how comfortably those sales support the current valuation.
- The share price is up about 252% over the past 3 years, which makes the link between PTC Therapeutics' revenue base and its current market value especially important to pin down.
- Management has highlighted strong product revenue trends and higher future revenue expectations, which can influence how much investors are prepared to pay for each dollar of the company's sales.
- Your read on PTC Therapeutics is one view; the desks covering it have another. See what analysts think PTC Therapeutics's shares could be worth.
The issue now is whether the current share price of PTC Therapeutics is adequately supported by its sales when judged against the Fair Ratio benchmark.
If you want to stress test this same sales based valuation question across a broader set of opportunities, take a look at 35 high quality undervalued stocks.
Is PTC Therapeutics Fairly Priced on Sales?
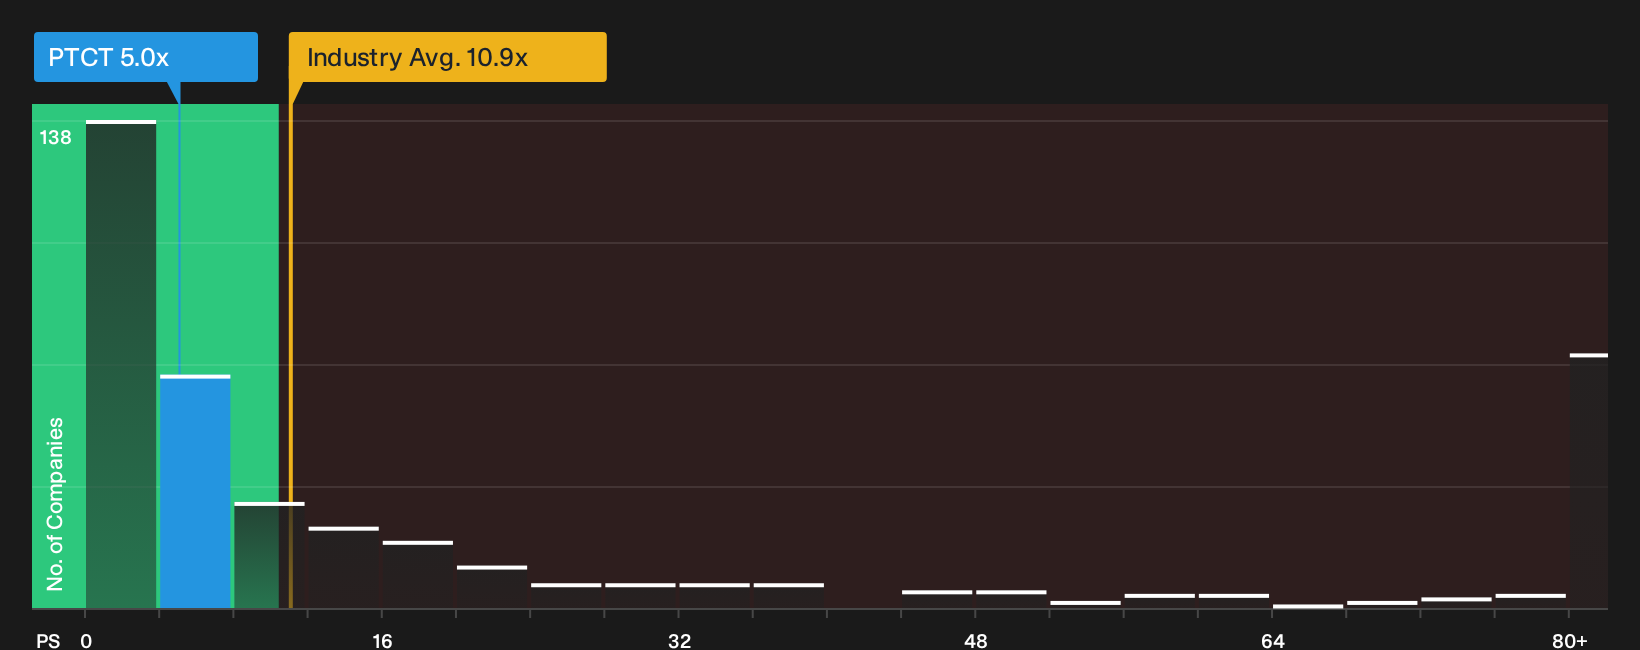
The P/S ratio is a useful yardstick for PTC Therapeutics because the business is still loss making and investors are effectively paying for revenue and pipeline rather than current profits. On this measure, the stock trades on a P/S of about 5.0x, which is below both the wider biotech industry on roughly 10.9x and the peer group average of about 15.8x. Taken together, this indicates the market is assigning a lower revenue multiple to PTC Therapeutics than to many comparable drug developers.
The Fair Ratio, which reflects what investors might typically pay for this level of growth potential, profitability profile, scale and risk, sits very close to the current P/S. As a result, the shares appear roughly fairly valued on this framework rather than clearly cheap or expensive. Because management lifted 2026 product revenue guidance after a strong third quarter, the current multiple suggests recent optimism on the top line has not yet pushed the stock to a premium price against either the sector or peers. Explore the numbers behind PTC Therapeutics's P/S valuation.
The PTC Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for PTC Therapeutics pick up where the valuation puzzle leaves off. They spell out which paths for growth, margins and future earnings would need to play out for the stock to be worth meaningfully more or less than today’s price on the Community page. Each scenario links its number to a clear view of how PTC Therapeutics' prospects and risks might evolve, giving you something concrete to revisit as fresh information comes through.
Community views on PTC Therapeutics split between those who see more upside in the rare disease portfolio and those who think a lot is already priced in.
Bull case: 29% undervalued
"Momentum in Sephience uptake, with worldwide revenue of US$182 million in Q3 2026 and active commercial patients rising to over 2,000 by September 30, 2026, signals that further penetration of the PKU population could remain a key driver of product revenue expansion and improved earnings power..."
Discover why this Narrative puts PTC Therapeutics at 29% undervalued.
Bear case: 11% overvalued
"Although Sephience currently supports higher revenue guidance and strong patient retention for PTC Therapeutics, real-world discontinuation near 20% and full penetration of U.S. PKU centers suggest the easiest volume gains may already be captured..."
Explore why this Narrative puts PTC Therapeutics at 11% overvalued.
One more question for PTC Therapeutics that the valuation alone cannot answer
Price and sales tell you what investors are paying for PTC Therapeutics today, but analyst projections a few years out offer a different lens on where expectations sit and how bold they really are. Explore where analysts expect PTC Therapeutics to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com