
Mercury Systems Stock Gains Attention Ahead Of Expected Earnings Beat
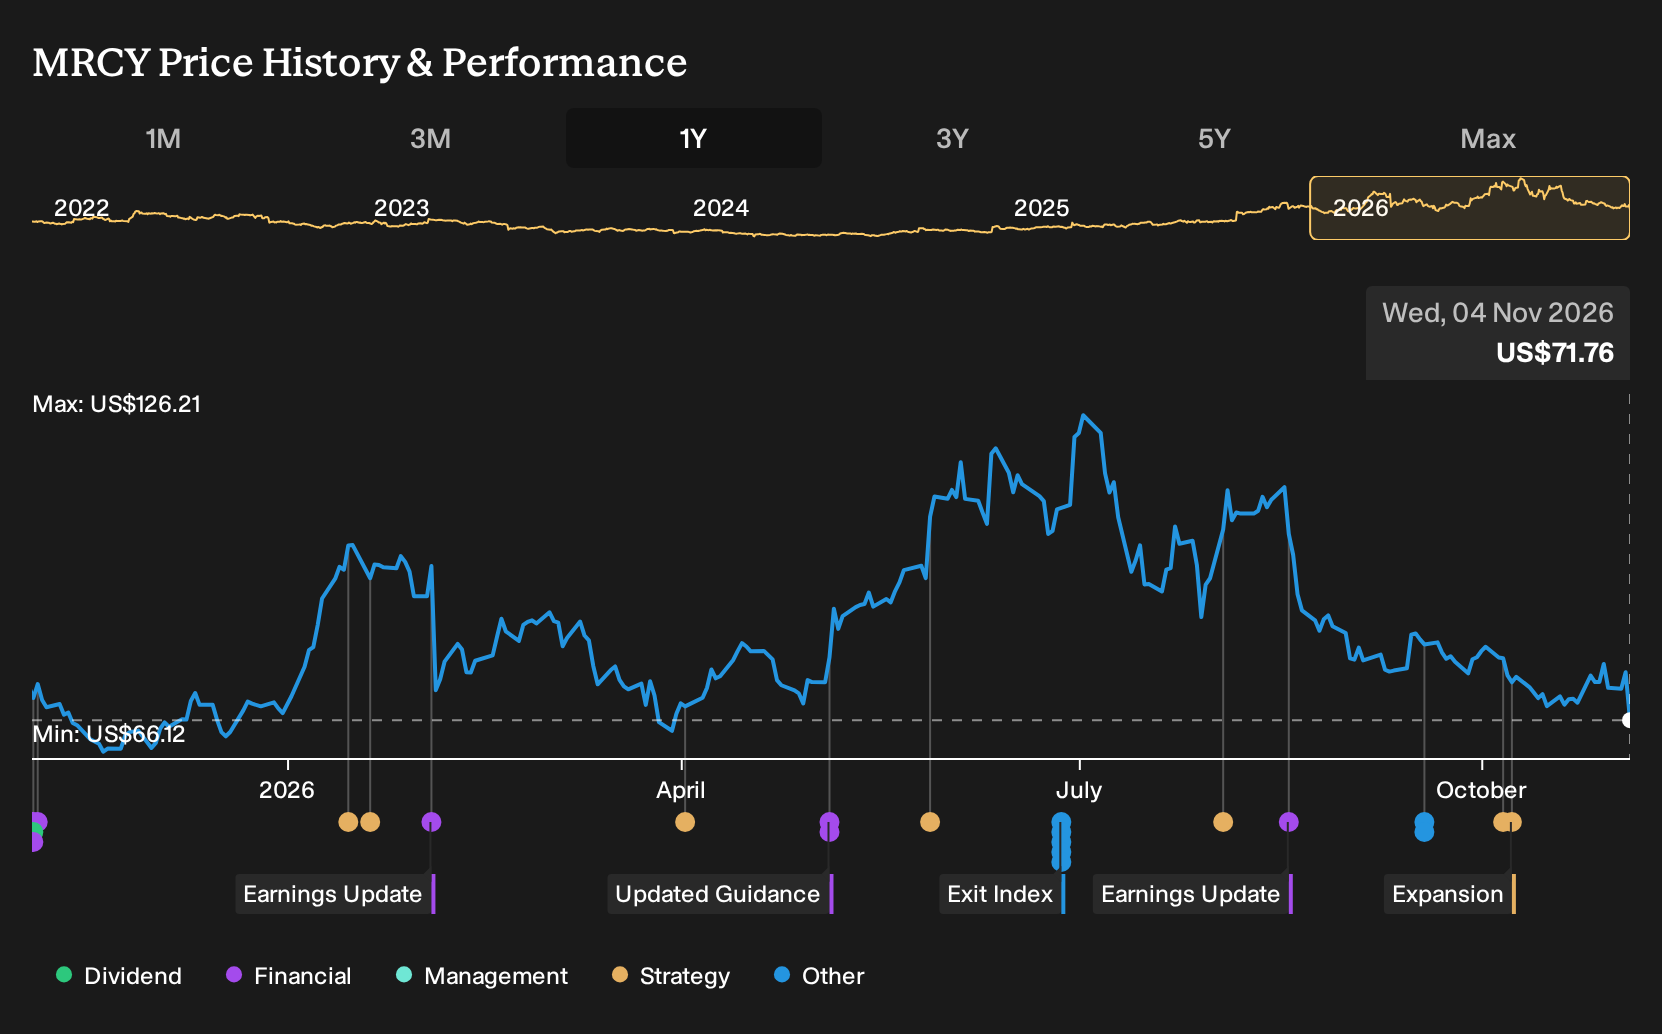
- Mercury Systems recently drew attention after analysts projected higher earnings and revenue for the quarter ended September 2026, with forecasts suggesting the company could outperform consensus expectations when it reports results, previously anticipated around November 10.
- The focus now is on how Mercury Systems is translating defense digitization demand and operational changes into profitability, since confidence in an earnings beat hinges on whether recent process improvements and higher value programs are flowing through to the bottom line.
- The next area of attention is how Mercury Systems' anticipated earnings strength could reshape the existing investment narrative built around defense modernization and margin repair.
Scan how Mercury Systems fits into the broader defense digitization story by comparing it with a curated 31 resilient stocks with low risk scores featuring companies that have resilient balance sheets and measured risk profiles.
Mercury Systems Investment Narrative Recap
To own Mercury Systems, you need to believe the defense digitization theme and higher value embedded processing work will ultimately show up in cleaner margins and more consistent earnings. In the short term, the key swing factor is whether current operational fixes and mix shift can turn forecast earnings strength into visible progress on profitability while the business is still working through older contracts.
The biggest risk remains that legacy, low margin backlog and past delivery pull forwards limit how much of any near term revenue strength converts into durable earnings. The latest optimism around the upcoming quarter could be a useful proof point, but it does not yet change that execution over the next few years matters most.
Recent commentary around the September 2026 quarter points to expectations for higher earnings on stronger sales, which ties directly into the key catalyst for Mercury Systems. Investors are watching to see if defense modernization programs in radar, electronic warfare and sensors are now translating into a healthier mix and better operating leverage on the income statement.
This same update also brushes up against the main risk factors. Mercury Systems is still unprofitable, carries a backlog of older contracts and has leaned on tactics like accelerated deliveries in the past. A cleaner quarter with earnings strength driven by core program execution rather than timing effects would give more confidence that the medium term margin repair story is on track.
Mercury Systems' current results show an earnings loss of $29.7 million. Analysts expect earnings of $115.7 million on about $1.3 billion of revenue by 2029. This outlook is based on forecast revenue growth of 10.1% per year and an earnings change of roughly $145.4 million from today's loss level to the 2029 consensus figure.
Uncover why Mercury Systems' fair value indicates a 54% potential upside to its current price, while that discount to expectations may not last much longer.
Exploring Other Perspectives
One alternate angle on Mercury Systems leans heavily on cash conversion risk. The most cautious analysts already penciled in earnings of about US$85.3 million on roughly US$1.3b of revenue by 2029, well below the consensus profit view. That group sees weaker margin progress, which sets up a much more pessimistic story that could shift as this earnings news lands and fresh data comes through.
Explore 4 other Mercury Systems fair value estimates, including one that suggests as much as 39% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Mercury Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mercury Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mercury Systems' overall financial health at a glance.
Looking for more Mercury Systems investment ideas?
If the Mercury Systems story has sharpened your thinking and you want to broaden your watchlist, the Simply Wall St Screener can help you scan for other opportunities that fit your risk tolerance and style.
- For investors who care most about financial resilience and balance sheet strength, start with a list of solid balance sheet and fundamentals (24 results) to help you focus on companies built to handle tougher conditions.
- If income is a priority and you are weighing yield against durability, use a 5 dividend fortresses to spot potential payers with higher distributions that still show support from their fundamentals.
- Readers hunting for underappreciated stories can review a 19 high quality undiscovered gems that highlights businesses with solid metrics which are not yet widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com