
W. P. Carey (WPC) Stock May Still Look Reasonable Following Raised AFFO Guidance
W. P. Carey has quietly delivered a 41.6% share price gain over the past three years, which puts a spotlight on whether its current valuation is still anchored to what the business is earning. With fresh earnings news on the table, the question for you now is how much of that operating performance is already baked into today's price.
- A 41.6% return over three years means anyone looking at W. P. Carey today is effectively being asked to pay a meaningfully higher price for the same stream of earnings than a few years ago, which sharpens the focus on what those earnings are really worth.
- Recent updates around funds from operations, rent growth and investment activity can shape how investors think about the durability of W. P. Carey's earnings power and the timing of future cash flows that support the share price.
- The analysts covering W. P. Carey have run their own numbers. See what analysts think W. P. Carey's shares could be worth.
The issue now is whether the stock's current price, after that multiyear run and recent earnings news, is justified by the level and quality of W. P. Carey's earnings.
If you want a reference point for how W. P. Carey’s recent earnings story compares with other opportunities, it can help to scan a wider field using the 35 high quality undervalued stocks.
Does W. P. Carey Look Undervalued on Earnings?
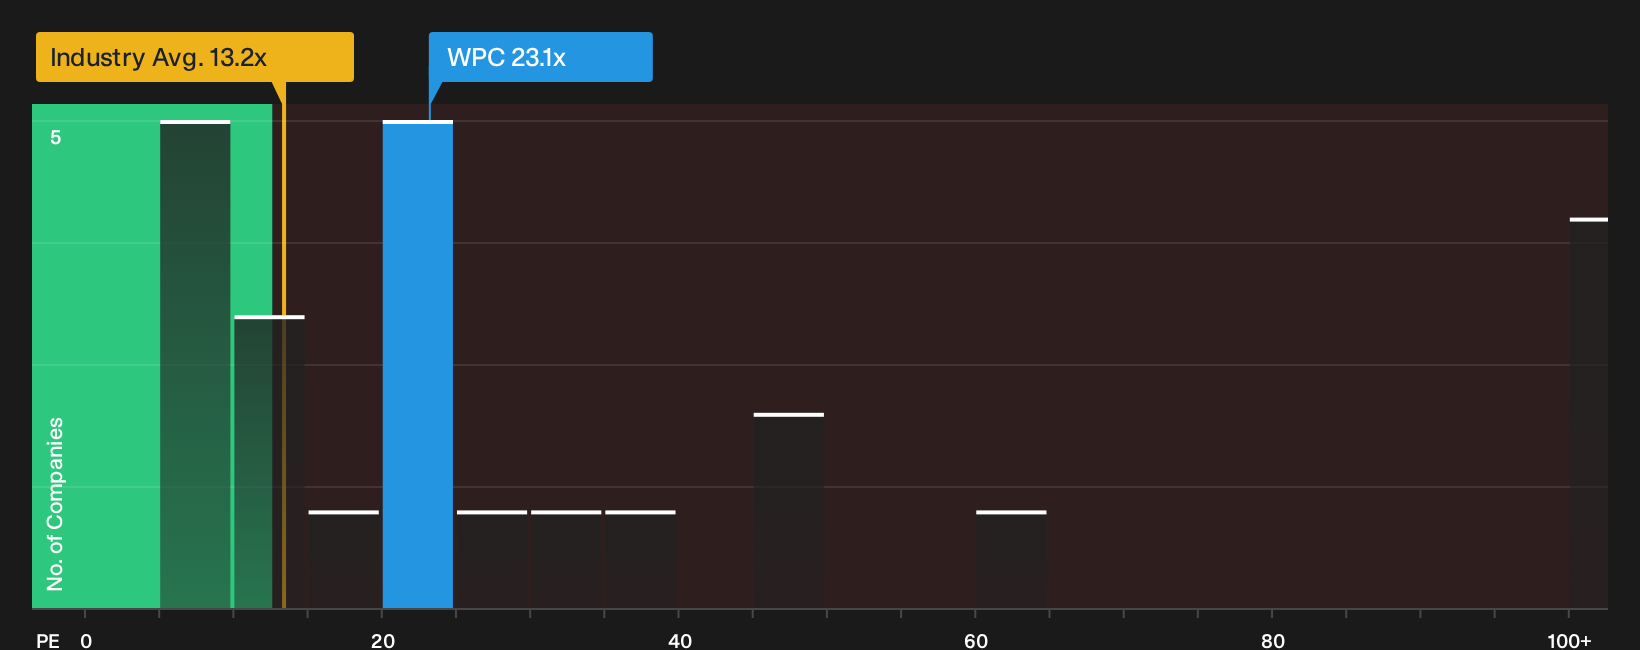
The P/E ratio suits W. P. Carey because investors usually look at earnings power first for income-focused real estate vehicles. On this measure, W. P. Carey currently trades on a P/E of 23.1x, compared with about 13.2x for the wider REITs group and a peer average near 71.6x. Against a tailored fair multiple that reflects its own growth profile, margins, size and risk mix, that current P/E screens on the cheaper side. This points to the earnings stream being priced below what this framework would suggest.
Because W. P. Carey recently raised full-year AFFO guidance and its dividend alongside solid Q3 2026 metrics, the fact that the P/E still sits below this customised benchmark suggests the stronger operating update has not fully closed the gap that model implies. For anyone weighing the stock today, the key question is whether the quality and stability of those earnings justify the market keeping that discount in place or narrowing it over time. Explore the numbers behind W. P. Carey's P/E valuation.
The W. P. Carey Narrative: What Would Justify Today's Price?
Narratives pick up where the valuation puzzle for W. P. Carey leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth much more or much less than it is today on Simply Wall St's Community page. Each scenario links a specific fair value view to a particular mix of potential catalysts and risks, which lets you watch over time which version of W. P. Carey's story is actually unfolding.
The W. P. Carey community is split between investors who see a meaningful valuation gap and others who think the stock already prices in a lot of good news.
Bull case: 12% undervalued
"Current valuation implies the share price does not fully reflect the raised 2026 AFFO guidance, the prefunded investment pipeline of up to $2.1b, and the company’s shift toward long-lease industrial, warehouse and retail properties..."
Discover why this Narrative puts W. P. Carey at 12% undervalued.
Bear case: 27% overvalued
"What holds me back is price: the stock trades above fair value and above my entry filters, so the buy signal stays Risky..."
Explore why this Narrative puts W. P. Carey at 27% overvalued.
One last W. P. Carey check that belongs beside the price tag
Before you lean too hard on earnings multiples and community scenarios, it is worth seeing what underlying issues our broader checks have picked up around W. P. Carey, and how serious they might be for your thesis. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com