
Is Enova International (ENVA) Undervalued Following Its $600 Million Notes Offering And Strong Guidance?
Enova International (ENVA) has been active on the funding side. The company recently launched a new US$600 million senior unsecured notes offering due 2031, following a recent securitization and an expansion of its credit capacity.
The fresh US$600 million notes come after a busy few months for Enova International, with a larger revolving credit facility, a US$500.25 million OnDeck securitization, third quarter results and guidance, and an active buyback all contributing to sentiment around the stock.
At a share price of US$181.18, the 1 day share price return of 3.47% and year to date share price gain of 11.87% sit alongside a 12 month total shareholder return of 41.55%. These moves have come despite a 90 day share price decline of 29.22%.
Compare Enova International's funding and earnings story with a curated group of financials that share strong fundamentals and balance sheet resilience using our list of solid balance sheet and fundamentals (24 results).
Enova International’s sharp one year gain and steep 90 day pullback can look like a story about mood swings or a readout on business fundamentals. The question is which lens makes more sense when you test the valuation next.
Most Popular Narrative: 24% Undervalued
On the most followed view, Enova International’s fair value of $238.50 sits well above the recent $181.18 share price. This puts the recent drawdown and funding activity in a different light for anyone weighing the long term story.
Enova International's use of advanced machine learning and AI for real time, data driven credit risk management is now extending into generative AI and automated final decisioning at OnDeck. This is cutting funding decision times to under a minute and could support lower credit losses and higher net revenue margins.
See why 11 investors see Enova International as 24% undervalued.
Result: Fair Value of $238.50 (UNDERVALUED)
Still, the Enova International story can change quickly if regulators tighten rules on nonprime lending or if capital markets funding becomes more expensive or scarce.
Find out about the key risks to this Enova International narrative.
Another View: Enova International Through The P/E Lens
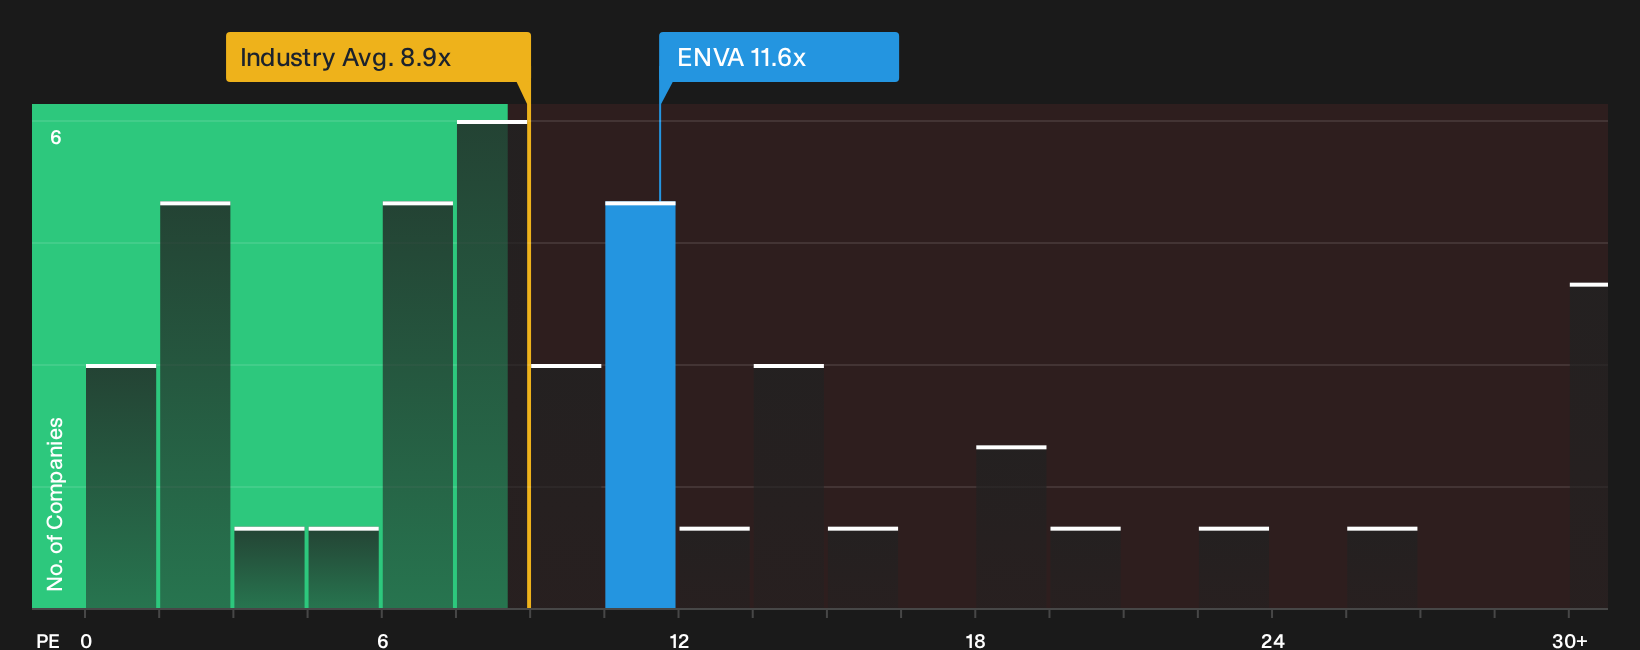
The first story presents Enova International as undervalued at a fair value of $238.50, yet the simple earnings multiple sends a mixed signal. At a P/E of 11.6x, the stock trades below the broader US market on 18x, but above the US Consumer Finance sector on 8.5x.
Our fair ratio for Enova International is 14.5x earnings, which is higher than the current 11.6x. That gap suggests there may be room for re-rating if the market moves toward the fair ratio. However, the premium to industry peers indicates there may be less room for error if earnings or sentiment weaken from here. Which story do you think the market may price in next: the discount to the fair ratio, or the premium to the sector multiple?
See what the numbers indicate about this price in our valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Enova International has clearly split opinions, which makes this an ideal moment to pull up the full dataset and pressure test it yourself. If you want a concise rundown of both the risks that investors are worried about and the potential rewards they are focusing on, start with these 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Enova International?
If you only focus on Enova International, you risk missing other opportunities that fit your style, your risk tolerance, and your return expectations.
- Target potential underpriced opportunities by scanning a curated 35 high quality undervalued stocks that blends solid fundamentals with attractive valuations.
- Strengthen portfolio resilience by reviewing a 31 resilient stocks with low risk scores that emphasizes durable balance sheets and lower historical risk scores.
- Hunt for tomorrow's potential standouts by filtering a 19 high quality undiscovered gems with quality metrics that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com