
HEICO (HEI) Could Be 17% Undervalued Following Rising Earnings Expectations
HEICO (HEI) is back in focus after being flagged among defense stocks that are expected to beat quarterly earnings forecasts, with its aerospace aftermarket, defense and space exposure, backlog, and EthosEnergy acquisition drawing investor attention.
Recent trading has been choppy for HEICO, with the share price rising 8.6% over the past week and 12.0% over the last month, yet still down 7.1% over ninety days, as investors weigh stronger earnings expectations, defense and space demand, and ongoing integration of EthosEnergy.
At the latest share price of US$337.67, that pattern of short term share price momentum sits alongside a 2.5% year to date share price gain and a 6.2% total shareholder return over one year, compared with much larger total shareholder returns over three and five years that reflect a longer history of compounding for investors.
Scan other defense and aerospace aftermarket opportunities showing similar momentum to HEICO by checking the hand picked 41 power grid technology and infrastructure stocks in the same theme of mission critical infrastructure suppliers.
After that sharp rebound in HEICO and a richer earnings story, the real question now is simple: does the current price still leave enough upside to justify the risks you are taking on the valuation?
Most Popular Narrative: 14% Undervalued
HEICO’s most followed narrative pegs fair value at $393.70 against the latest close of $337.67. The story centers on whether investors are willing to back that gap with the company’s current growth, margin profile, and acquisition firepower.
The main thing that has to go right is that HEICO continues to convert its enlarged acquisition pipeline and expanded credit capacity into high margin, cash generative deals that stay accretive within a year. At the same time, it needs to maintain the higher margin framework now outlined for Flight Support Group and Electronic Technologies Group.
The current valuation implies investors are paying a premium for HEICO’s record profitability, cash generation, and long term net income growth ambitions despite share price volatility after recent results. This is consistent with a view that the stock is still undervalued.
See why 26 investors see HEICO as 14% undervalued.
Result: Fair Value of $393.70 (UNDERVALUED)
Still, the HEICO narrative can break if supply chain bottlenecks slow backlog conversion or if future acquisitions dilute margins instead of reinforcing them.
Find out about the key risks to this HEICO narrative.
Another View: HEICO Through The P/E Lens
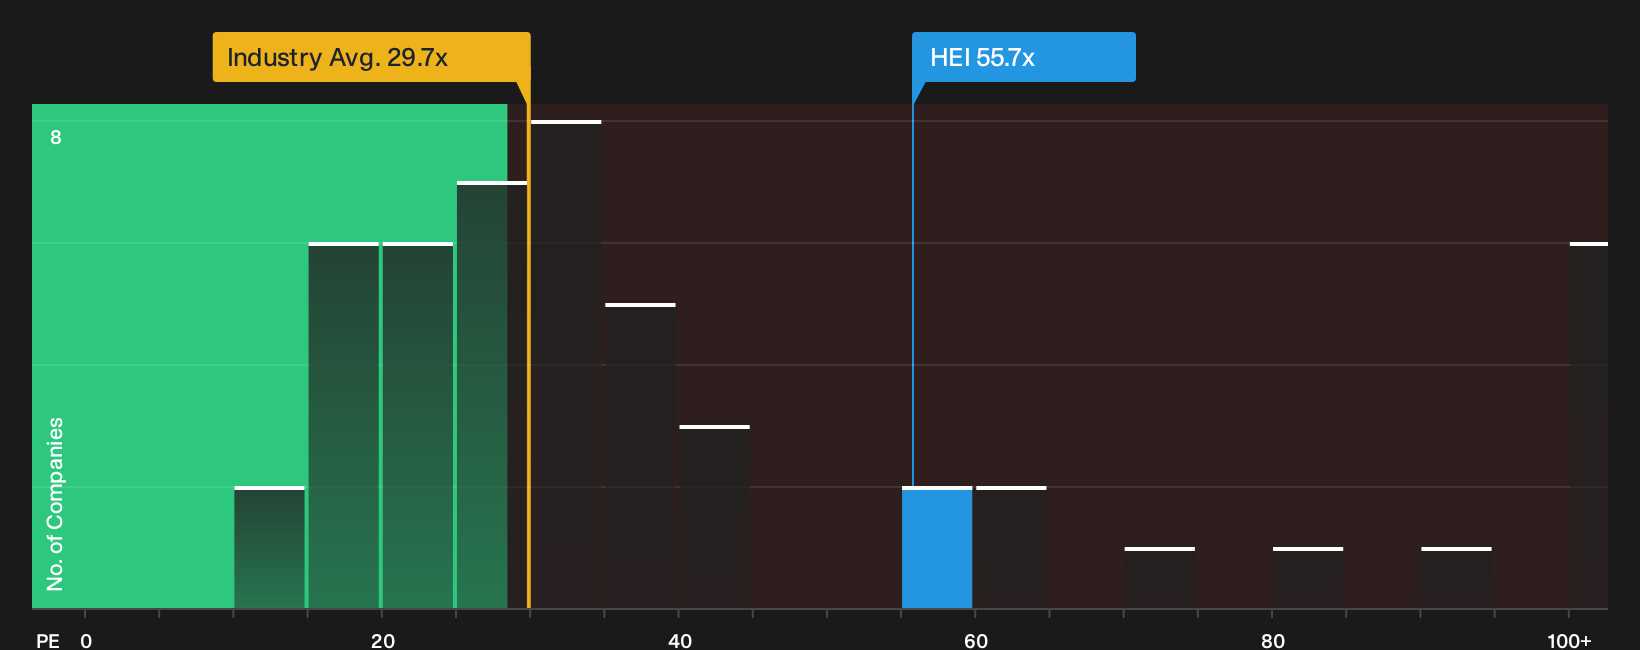
The DCF workup suggests HEICO is undervalued, yet the market’s own P/E yardstick tells a tougher story. At roughly 55.7x earnings, the stock trades far above the US Aerospace & Defense average of 29.7x and well above an estimated fair ratio of 28x. That kind of gap points to meaningful valuation risk if sentiment or growth expectations cool. Investors may therefore want to consider how comfortable they are paying more than double what the fair ratio suggests.
To pressure test that premium and see how the current price compares with the numbers, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Then review how HEICO’s earnings multiple compares with peers and the wider industry using the latest
Next Steps
With HEICO pulling investors in different directions, the fastest way to cut through the noise is to look at the data yourself and stress test both sides of the story. To weigh the upside against the concerns in one place, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond HEICO?
If HEICO has sharpened your focus on quality, use that momentum to widen your opportunity set with a few targeted stock ideas built from hard numbers.
- Explore potential mispricing by scanning a curated 35 high quality undervalued stocks that filters for strong fundamentals and supportive balance sheets.
- Reinforce your income strategy with a focused 5 dividend fortresses that highlights higher yielding payouts supported by underlying financial metrics.
- Refine your risk profile by reviewing a 31 resilient stocks with low risk scores that screens for companies with steadier risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com