
What Estée Lauder Companies Buyers Were Betting On
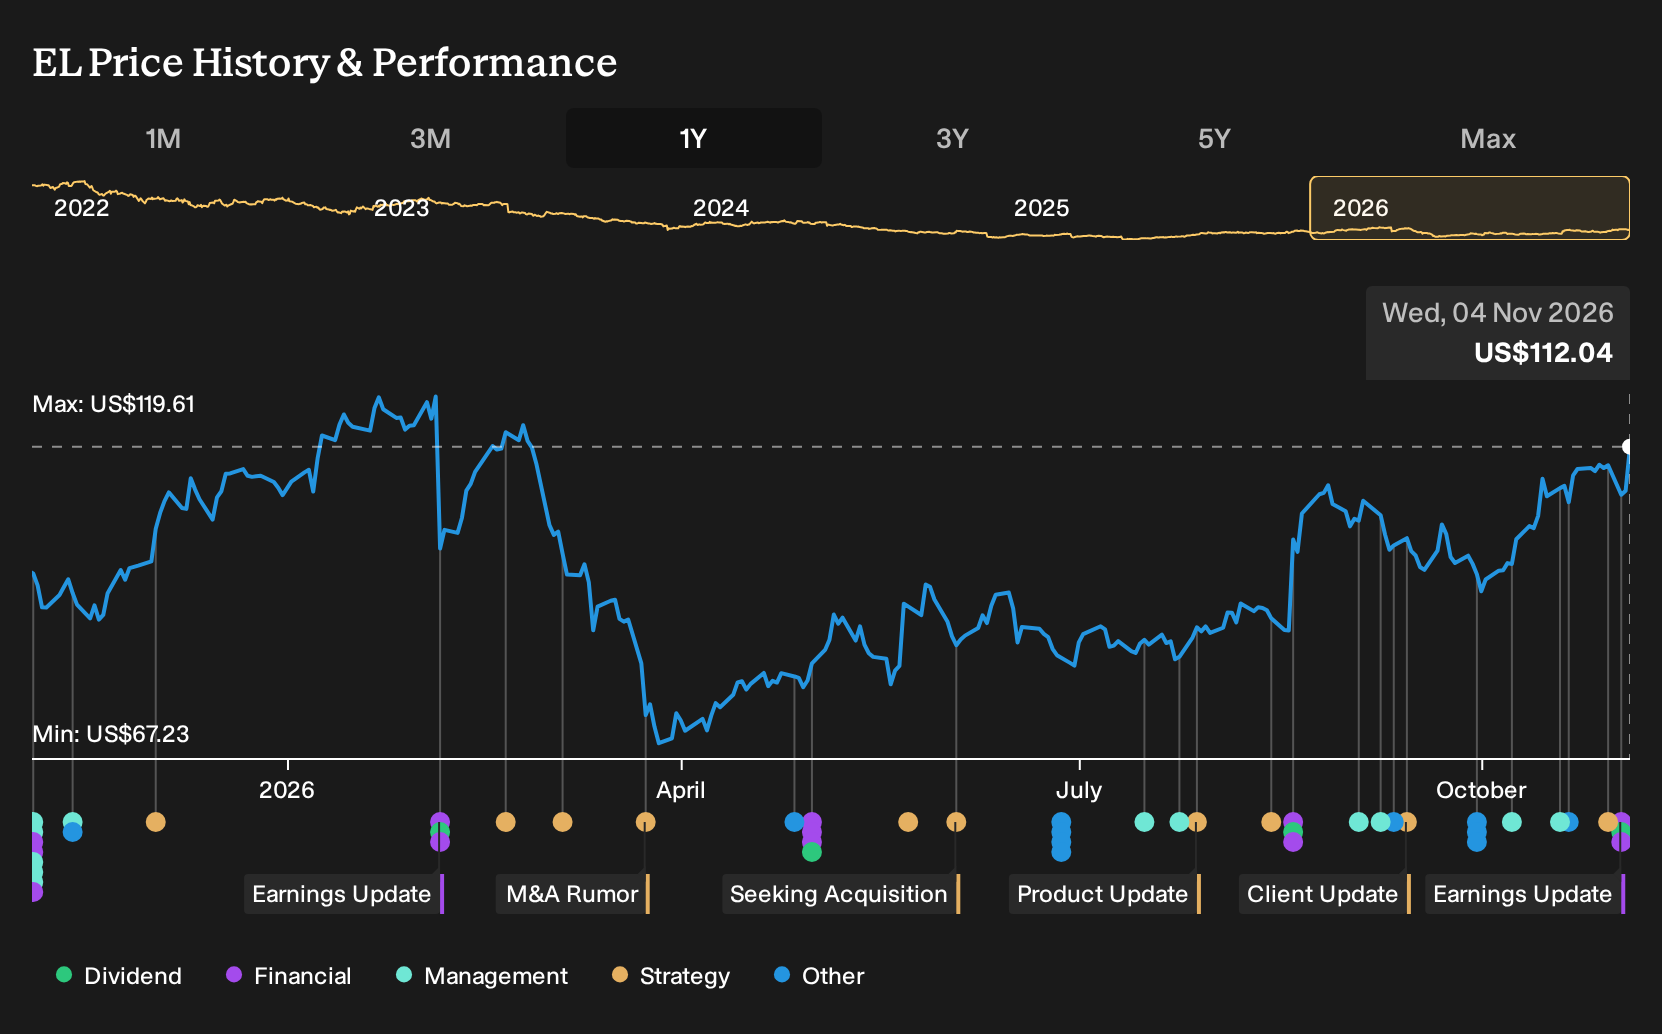
Estée Lauder Companies spent much of the past year in the headlines for a sweeping Profit Recovery and Growth Plan that paired thousands of job cuts with heavier investment in digital channels like Amazon and TikTok. Investors who held Estée Lauder Companies over the past year saw a total return of 24.7%, including dividends. If you were weighing a purchase back on 2025-11-04, what would you have needed to believe about this restructuring and digital pivot to feel comfortable buying in?
If the move has made Estée Lauder Companies harder to judge, start where the gap is still open and scan 35 high quality undervalued stocks.
The Two Stories Investors Had To Choose Between
The shares cost US$92.88 at the start of the period, and anyone looking at Estée Lauder Companies then had to decide which story felt more credible.
The bullish narrative pointed to a Fair Value of US$120, essentially the price implied if rapid digital expansion and emerging market growth lifted margins faster than consensus expected. Supporters leaned on assumptions that cost savings from the Profit Recovery and Growth Plan and higher direct-to-consumer sales would accelerate earnings improvement.
The bearish view anchored on a Fair Value of US$56.2, a level tied to expectations that travel retail volatility and rising digital competition would weigh on profitability. That camp focused on risks that regulatory costs, weaker conversion in duty free, and indie online rivals could cap sales growth and pressure margins.
What The Results Changed For Estée Lauder Companies
Sharp restructuring at Estée Lauder Companies, including plans to cut 9,000 to 10,000 roles and redirect spending to Amazon and TikTok, lined up with the bullish focus on cost savings and digital reach. Reported figures backed that tilt. Revenue moved from US$3,481m in Q1 2026 to US$3,715m in Q1 2027, while net income and net margin also improved. Overall, the evidence supported the optimistic case more than the cautious one.
The key hinge was profitability. Anyone weighing similar situations elsewhere can test the same claim by tracking whether net margin and absolute profit move in the direction management outlines for a restructuring or digital push, not just whether sales or guidance sound upbeat.
What Today's Estée Lauder Companies Price Already Assumes
Estée Lauder Companies now trades at US$112, after a 24.7% gain over the past year from US$92.88. The selected Narrative’s Fair Value sits below the current price, reflecting a more cautious stance on what the business performance might justify.
The Narrative hinges on whether margin gains and cash generation can keep pace with expectations. For today’s price to hold up, a buyer would need to believe restructuring and AI driven spending translate into sustained operating leverage without eroding cash conversion.
"The main thing that has to go right is that the Profit Recovery and Growth Plan and One ELC model keep translating margin gains seen so far into sustained operating leverage while restructuring charges, governance questions and higher working capital needs do not offset those benefits."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Another Beauty Question To Ask
Once you have a view on Estée Lauder, you might look sideways. The same shopper buying prestige skincare can also want cheaper, trend driven products.
One fast moving rival leans hard into that, using attention grabbing marketing and digital campaigns to stay visible with younger consumers.
Instead of relying on one hero label, it spreads bets across several lines. That mix lets it push into skincare, color cosmetics and newer categories.
For you, the puzzle is simple. If that entertainment heavy, multi brand model keeps resonating globally, how might its role in beauty spending change from here?
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 21% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com