
Simpson Manufacturing (SSD) Could Be 6% Below Fair Value After Earnings And $1b Buyback
Simpson Manufacturing (SSD) just paired a fresh earnings update with a major capital return decision, reporting higher third quarter and year to date profit figures while unveiling a US$1b share repurchase plan.
The earnings release and fresh US$1b buyback appear to have reset expectations around Simpson Manufacturing, with a 1-day share price return of 4.22% helping extend a year to date share price gain of 24.55% and a 1-year total shareholder return of 21.73%. The 3 and 5 year total shareholder returns of 46.96% and 77.69% point to momentum that has been building over a longer horizon.
Scan beyond Simpson Manufacturing and line up other construction and capital goods stocks showing resilient earnings and capital return programs using our hand picked 31 resilient stocks with low risk scores today.
Simpson Manufacturing now sits at a higher share price after the earnings beat and US$1b buyback plan. Does it make more sense to step in after this jump, or wait for a cleaner entry on valuation grounds?
Most Popular Narrative: 6% Undervalued
On the most followed view, Simpson Manufacturing’s fair value of $219 sits above the last close of $205.16. As a result, the fresh buyback lands against a narrative that already prices in some upside and measured earnings growth.
Ongoing investments in automation and domestic manufacturing capacity, including the new Gallatin fastener facility that shifts sourcing toward a greater U.S. share and shortens lead times, are expected to help Simpson Manufacturing manage tariff and input cost pressures and support gross margin and free cash flow over time.
See why 5 investors see Simpson Manufacturing as 6% undervalued.
Result: Fair Value of $219 (UNDERVALUED)
Still, muted 2.7% annual revenue growth and contracting earnings per share could challenge the idea that Simpson Manufacturing deserves a higher P/E in the long term.
Find out about the key risks to this Simpson Manufacturing narrative.
Another View: Simpson Manufacturing On Earnings Multiples
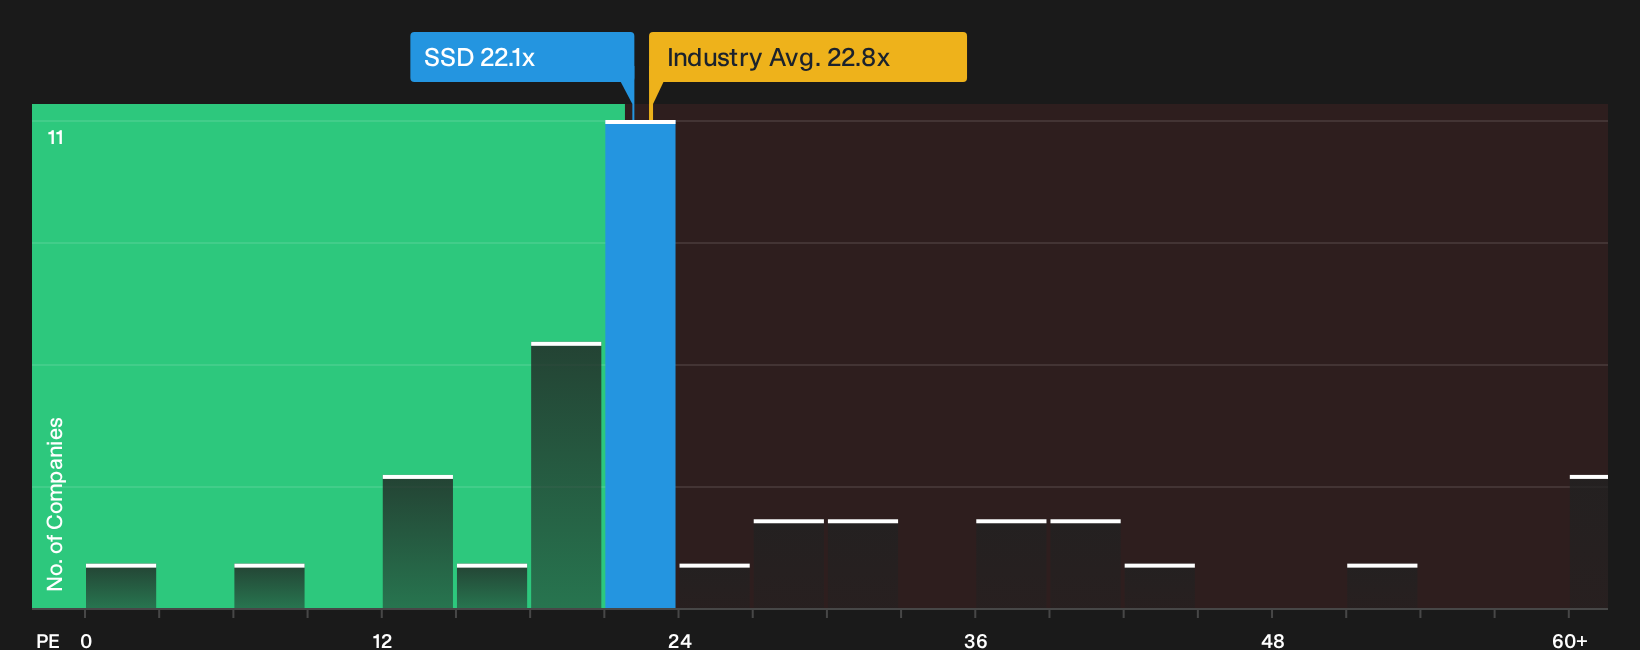
The SWS fair value narrative leans on future earnings and cash flow, yet Simpson Manufacturing trades on a 22.1x P/E while the estimated fair ratio is 18.4x. That is richer than both the US Building industry at 21.8x and the peer average of 22.7x, which suggests limited room for error in the story implied by today’s price.
For anyone weighing these mixed signals, it can help to see how the current P/E gap stacks up against fundamentals and where the ratio might drift if sentiment cools or improves from here. That is exactly what the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Simpson Manufacturing is clearly mixed, with both risks and rewards on the table. Move quickly and stress test the narrative against your own expectations by weighing the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Simpson Manufacturing?
Simpson Manufacturing might fit your thesis right now, but you avoid blind spots by lining it up against other high quality opportunities uncovered by disciplined screeners on Simply Wall St.
- Target resilient wealth builders by scanning for consistent earnings and robust balance sheets through our list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced potential by zeroing in on businesses trading below their estimated value using the focused 35 high quality undervalued stocks.
- Stack your watchlist with income heavyweights by filtering for strong yields and staying power via the curated 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com