
Is VeriSign (VRSN) Fairly Valued Following Its 2026 Outlook Update And Price Rise Plan?
VeriSign (VRSN) is back in focus after management refreshed its 2026 outlook, paired that update with third quarter earnings details, and confirmed another cash dividend for shareholders.
That updated 2026 outlook comes after a steady run in VeriSign’s share price, with a 1 month share price return of 8.82% and a year to date share price return of 32.22%. The 1 year total shareholder return of 31.95% and 3 year total shareholder return of 57.94% point to momentum that has been building rather than fading.
Compare VeriSign’s refreshed 2026 outlook with other infrastructure style plays by scanning a curated list of 31 resilient stocks with low risk scores that pair resilient balance sheets with consistent earnings profiles.
After a sharp move to around $318 and a fresh 2026 guide on the table, the real tension is simple. Do current VeriSign holders already own the upside that consensus models still point to?
Most Popular Narrative: 5.5% Undervalued
Against VeriSign’s last close at $318.03, the most widely followed narrative pegs fair value at $336.40, which puts that story slightly ahead of where the market is today and raises the question of whether domain momentum and buybacks still have room to work in shareholders’ favor.
The announced wholesale price increases for .com in November 2026 and .net in March 2027, together estimated to add more than US$120 million of annual revenue, are expected to feed directly into operating income and earnings given VeriSign's capital light cost structure.
See why 33 investors see VeriSign as 5% undervalued.
Result: Fair Value of $336.40 (UNDERVALUED)
Still, the whole VeriSign narrative can shift quickly if .com and .net contract renewals land on tougher terms, or if AI related domain demand cools faster than analysts expect.
Find out about the key risks to this VeriSign narrative.
Another View: VeriSign Through A Cash Flow Lens
The consensus narrative frames VeriSign as 5.5% undervalued at a fair value of $336.40, yet the SWS DCF model presents a much tougher picture. On that cash flow basis, the stock appears overvalued, with our estimate of future cash flow value at $221.58. That gap raises a simple question for you: Are analyst growth and margin assumptions generous, or is the cash flow model being too conservative about how long VeriSign’s domain economics can hold?
For a closer look at how the SWS DCF model weighs those long term cash flows against today’s $318.03 share price, Look into how the SWS DCF model arrives at its fair value.
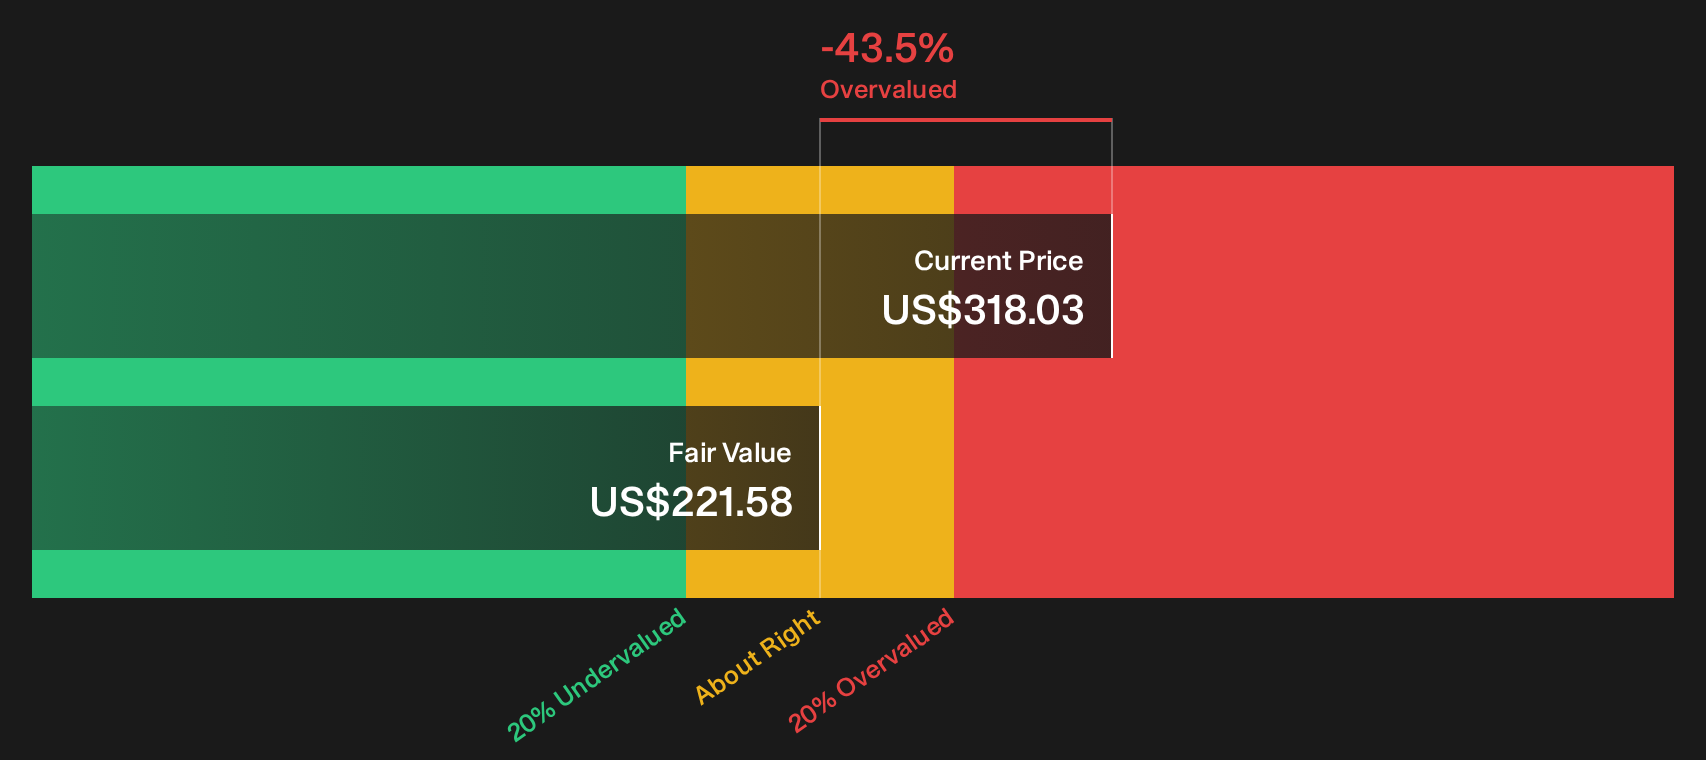
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out VeriSign for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around VeriSign feels familiar, treat it as your cue to move fast, interrogate the data, and weigh both sides for yourself. To see those trade offs laid out in one place, review the 2 key rewards and 3 important warning signs.
Looking for more VeriSign style investment ideas?
If VeriSign has sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist with other ideas that match your approach.
- Hunt for underappreciated compounders by scanning the 19 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Target resilient performers by checking the list of solid balance sheet and fundamentals (24 results) that can better handle earnings shocks and funding pressure.
- Zero in on value driven setups through the 35 high quality undervalued stocks that combine robust cash flows with share prices that trail fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com