
How Strong Earnings And Jamaica Expansion Will Impact PriceSmart Stock
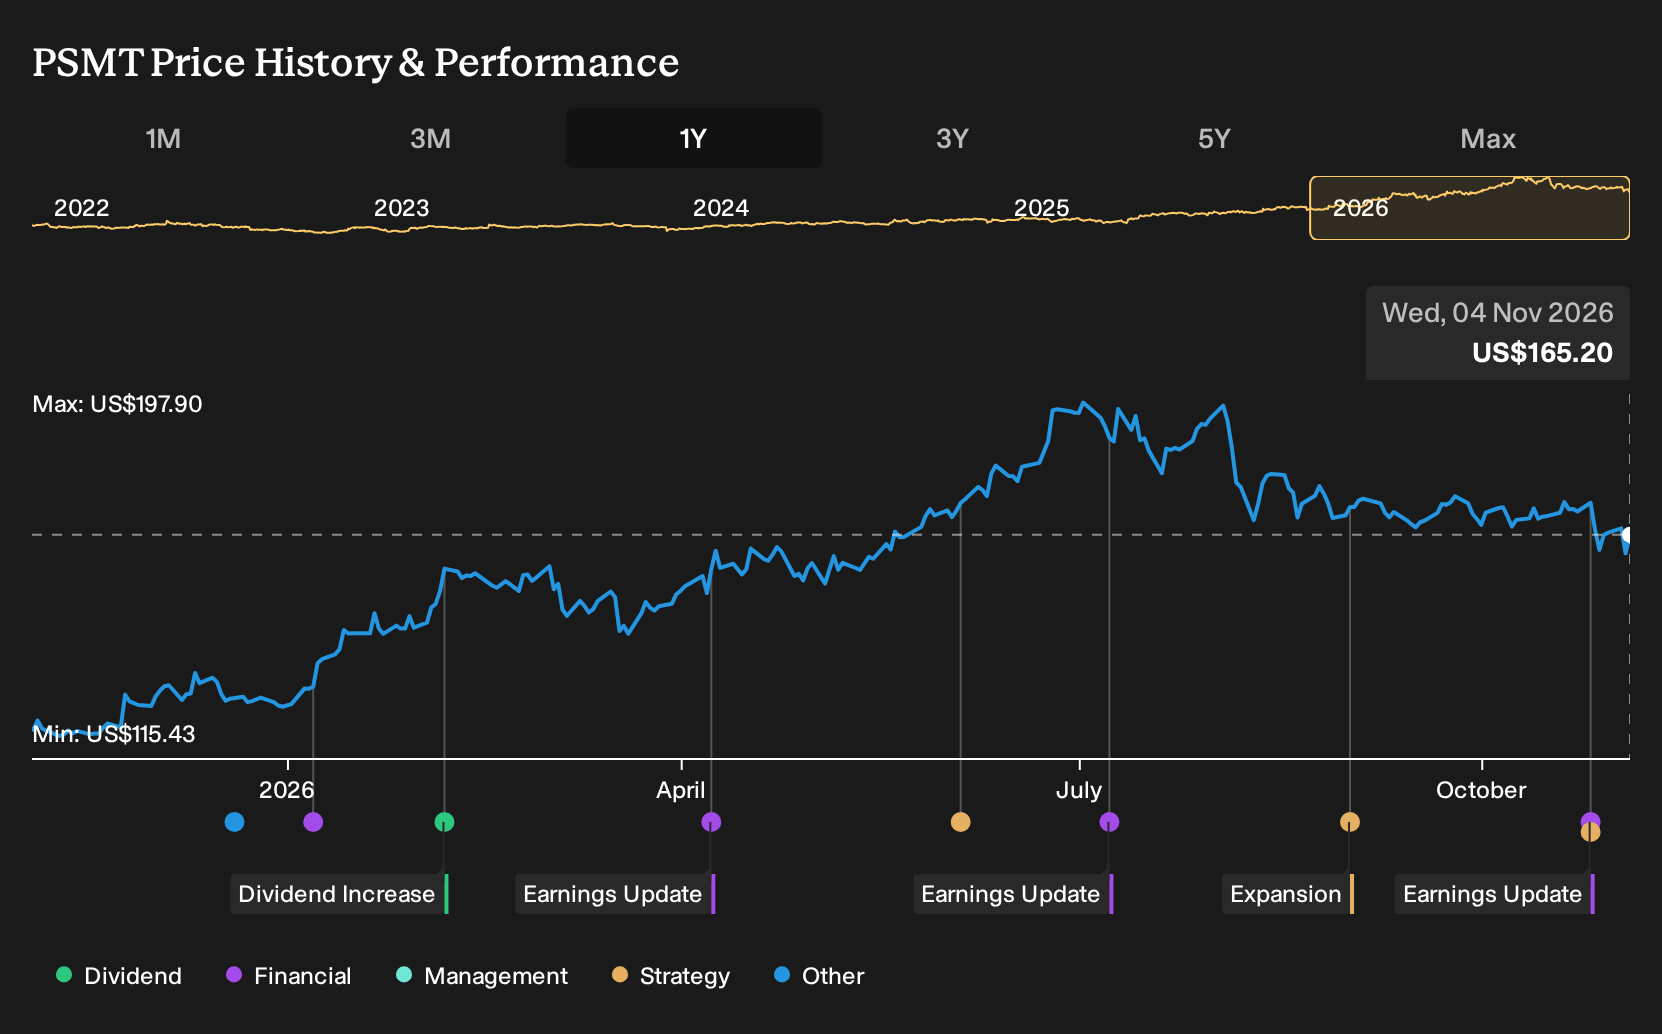
- PriceSmart reported fourth quarter revenue of US$1,516.27 million and net income of US$37.64 million, alongside a new Montego Bay warehouse opening that brought the Jamaica club count to three as of October 2026.
- The Montego Bay club adds a 42,000 square foot sales floor with solar panels, LED lighting and CO2-based cooling, highlighting how PriceSmart is pairing earnings progress with energy efficient expansion in the Caribbean.
- We will now look at how PriceSmart's investment narrative is shaped by these earnings results and the new Montego Bay club.
Scan more retailers pairing fresh earnings data with physical expansion by reviewing the hand picked 19 high quality undiscovered gems that echo elements of PriceSmart's Montego Bay and full year story.
PriceSmart Investment Narrative Recap
To own PriceSmart, you need to believe in a membership warehouse model that can keep drawing shoppers in Central America and the Caribbean while maintaining tight operations. The latest quarter and full year show revenue of US$1,516.27 million and US$5,876.32 million, with net income of US$37.64 million and US$166.59 million. Those figures support the idea of a business already functioning at scale.
The key near term swing factor is how effectively PriceSmart manages FX exposure, import costs and rising SG&A from technology and logistics spending. The main risk remains FX and liquidity stress in markets such as Trinidad and Honduras. This earnings update does not fundamentally change that risk reward balance in the short term.
The most relevant development for this story is the new Montego Bay warehouse in Jamaica. It adds a 42,000 square foot sales floor on a five acre site and brings the local club count to three. This is important if you focus on how PriceSmart deepens its presence in existing territories rather than only opening in new countries.
For catalysts, this opening ties directly into the broader club rollout that analysts already follow, including the plan to reach 63 clubs once four more locations come online. The sustainable design features, such as solar panels, LED lighting and CO2 based cooling, also contribute to the operational side of the thesis by targeting lower energy usage and more predictable running costs over time.
PriceSmart's narrative projects US$7.8b revenue and US$219.7 million earnings by 2029. This rests on analysts assuming 11.2% yearly revenue growth and an earnings increase of about US$62.5 million from US$157.2 million today.
Uncover how PriceSmart's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You also get a very different Chile story in the more pessimistic PriceSmart narrative. Those analysts focus on execution risk and see the planned Chile entry and broader club build out as a potential drag, even while penciling in revenue of about US$8.1b and earnings near US$224.8 million by 2029 before this Montego Bay news. That gap shows how widely opinions can spread. It makes sense to compare several viewpoints yourself as fresh results and expansion updates land.
Explore 3 other PriceSmart fair value estimates, including one that suggests as much as 23% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your PriceSmart research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for PriceSmart. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PriceSmart's overall financial health at a glance.
Looking For More Investment Ideas Beyond PriceSmart?
Once you have a handle on PriceSmart's story, it can help to set it alongside other businesses that share traits you care about, whether that is valuation support, balance sheet strength, or income potential. The Simply Wall St Screener lets you filter for those kinds of companies directly, so you can build a watchlist that matches your own priorities rather than relying on headlines.
- If you want potential value on your side, start with companies filtered for quality and pricing support using the 35 high quality undervalued stocks.
- For investors who care most about staying power, focus on balance sheets and fundamentals with the list of solid balance sheet and fundamentals (24 results).
- Income focused readers can look for reliability and yield in the 5 dividend fortresses that prioritises higher payout opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com