
Dave (DAVE) Shares Just Moved, So What Is Driving Attention Now?
Dave (DAVE) just posted its third quarter 2026 results, reporting higher revenue for both the quarter and year to date but lower quarterly net income. This combination gives investors fresh numbers to reassess the stock.
Dave’s share price moved sharply on the earnings release, with a 1-day share price return of 6.83% taking the stock to $336.22. The 90-day share price return of 5.75% and year-to-date share price gain of 53.19% sit alongside a very large 3-year total shareholder return, suggesting momentum has been strong over a longer window even as the 30-day share price return declined 2.02% ahead of this report.
Compare Dave’s earnings driven move with other fintech operators that have hand picked balance sheets and fundamentals in the list of solid balance sheet and fundamentals (24 results).
After a sharp move on mixed Q3 earnings, the puzzle for Dave holders and would be buyers is simple: Does the current price still leave enough upside to justify the risk now baked in?
Most Popular Narrative: 24% Undervalued
On the most followed view of Dave, the fair value of $444.21 sits well above the latest close at $336.22. This frames the recent earnings move as only part of a larger valuation gap that depends on how its credit engine and funding model hold up.
Ongoing advances in CashAI, with v5.5 associated with record-low loss metrics and v6 built on more than 700 features and already supporting higher credit limits at similar loss ranges, point to a scalable credit engine that can support higher ExtraCash originations and gross profit while helping protect net margins.
See why 47 investors see Dave as 24% undervalued.
Result: Fair Value of $444.21 (UNDERVALUED)
Still, the unresolved DOJ investigation and research pointing to Dave trading at a premium to some intrinsic value estimates could quickly flip this upbeat narrative if sentiment turns.
Find out about the key risks to this Dave narrative.
Another View: Multiples Paint A Pricier Picture For Dave
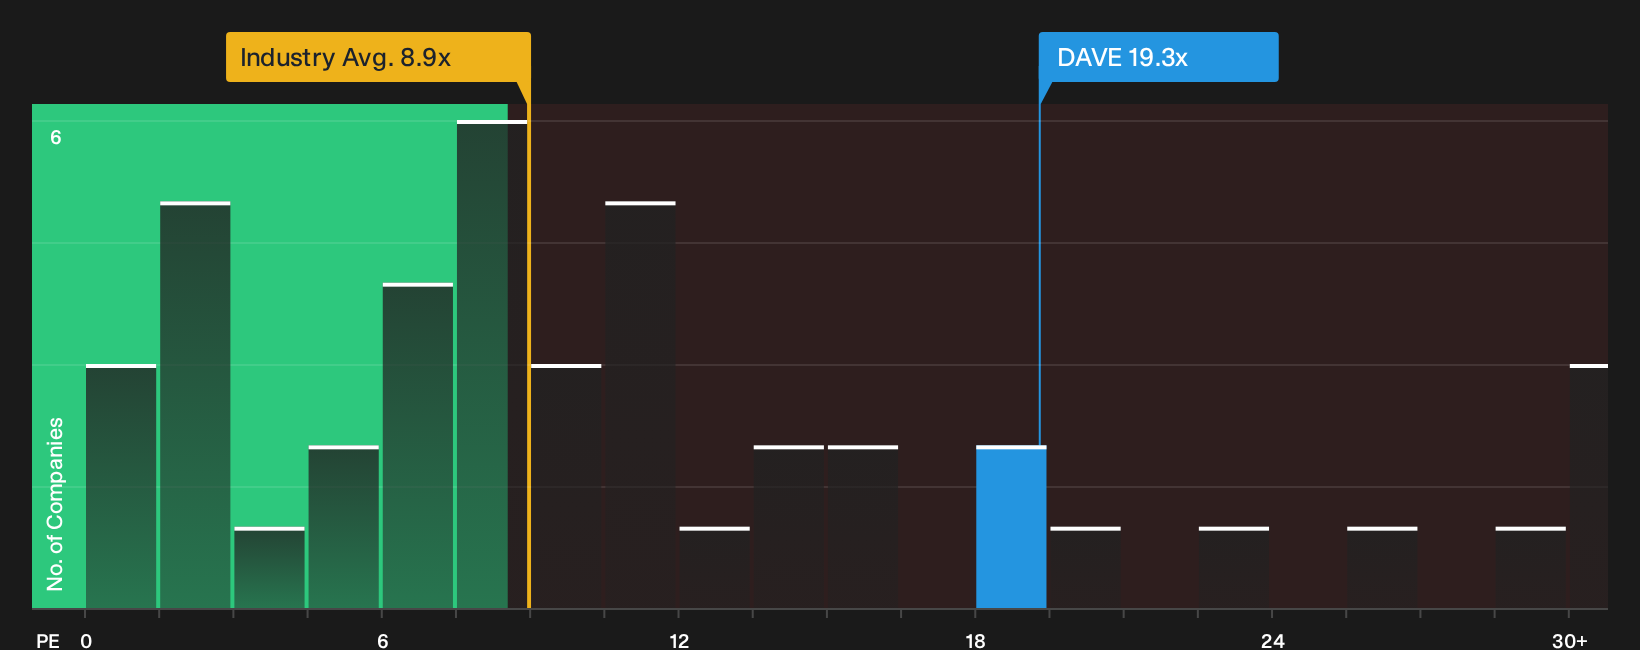
The story looks different when you shift from fair value estimates to simple earnings multiples. Dave trades on a P/E of 19.3x, which is slightly above its own fair ratio of 17x and also ahead of both peer averages at 19.2x and the wider US Consumer Finance group at 8.9x.
That kind of premium suggests the market already prices in a lot of the growth and profitability forecasts, so any wobble in execution or sentiment could matter more for holders than the bullish fair value alone might imply. The real question is whether you view that extra multiple as justified breathing room or as a margin for error that has already been spent.
To see how this P/E premium fits with the rest of the numbers, and where the market could move if it drifts toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Here is how Dave’s valuation stacks up visually against the sector on key earnings multiples.
Next Steps
Sentiment on Dave is clearly split between promise and pressure, so move quickly, inspect the full data set, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Dave?
If Dave has your attention after this report, do not stop here. Broaden your watchlist, compare quality, and pressure test your thesis against other options now.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) to see which businesses currently meet stricter financial health filters.
- Hunt for quality at a discount by reviewing the 35 high quality undervalued stocks that combine solid cash generation with pricing that still looks reasonable.
- Prioritise staying power and calmer drawdowns by checking the 31 resilient stocks with low risk scores that screen well on balance sheet strength and risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com