
How Food Safety Disruption At Marzetti Stock Has Changed Its Investment Story
- Marzetti reported first quarter fiscal 2027 sales of US$481.52 million and net income of US$29.3 million, with earnings per share from continuing operations at US$1.07 to US$1.08.
- The firm is dealing with the earnings impact of a cyclospora outbreak and higher freight costs, while still pushing new branded sauces, licensing deals and leadership changes aimed at its Retail operation.
- We will look at how Marzetti's investment narrative is affected by weaker quarterly earnings tied to the cyclospora outbreak.
Compare how Marzetti's earnings setback stacks up against other consumer brands under pressure by scanning 31 resilient stocks with low risk scores with resilient balance sheets and steadier risk profiles.
Marzetti Investment Narrative Recap
For Marzetti, the core belief is that a branded sauces, dressings and frozen bakery portfolio can still pull in steady demand, even as consumers lean harder into fresh and clean label options. The latest quarter complicates that story in the short run. Sales slipped to US$481.52 million and net income to US$29.3 million, with EPS from continuing operations at US$1.07 to US$1.08, as the cyclospora outbreak and freight costs weighed on results.
The key near term catalyst is simple. Management needs to show that volumes and margins can stabilize once the outbreak effect normalizes and freight pressures are managed through pricing and cost savings. The biggest current risk is that health driven preference shifts and retailer private label pressure intersect with these temporary headwinds, turning a one off earnings setback into a longer stretch of softer demand or compressed profitability.
The Tajín collaboration is the most relevant recent announcement for this earnings story. It keeps the focus on what Marzetti can directly control. The business is pairing Tajín’s flavor profile and brand recognition with its own dressing expertise, aiming to bring a new shelf stable dressing line to market. The plan is to pilot the range as early as Spring 2027.
For you as an investor, this matters because it connects directly to catalysts and execution. A Tajín branded line gives Marzetti another licensed platform alongside restaurant partnerships and Bachan’s Japanese Barbecue Sauce. It supports the push for volume led Retail growth, product diversification and premium offerings, while also introducing operational risk around new product development, marketing spend and getting the pilot to scale in a category where private label and health trends already demand very precise positioning.
Marzetti's current analyst storyline points to revenues of US$2.1b and earnings of US$197.3 million by 2029, based on revenue growth of 2.1% per year and a move from US$191.6 million in earnings today, which is an increase of about US$5.7 million.
Uncover why Marzetti's fair value indicates a 31% potential upside to its current price, which could narrow quickly.
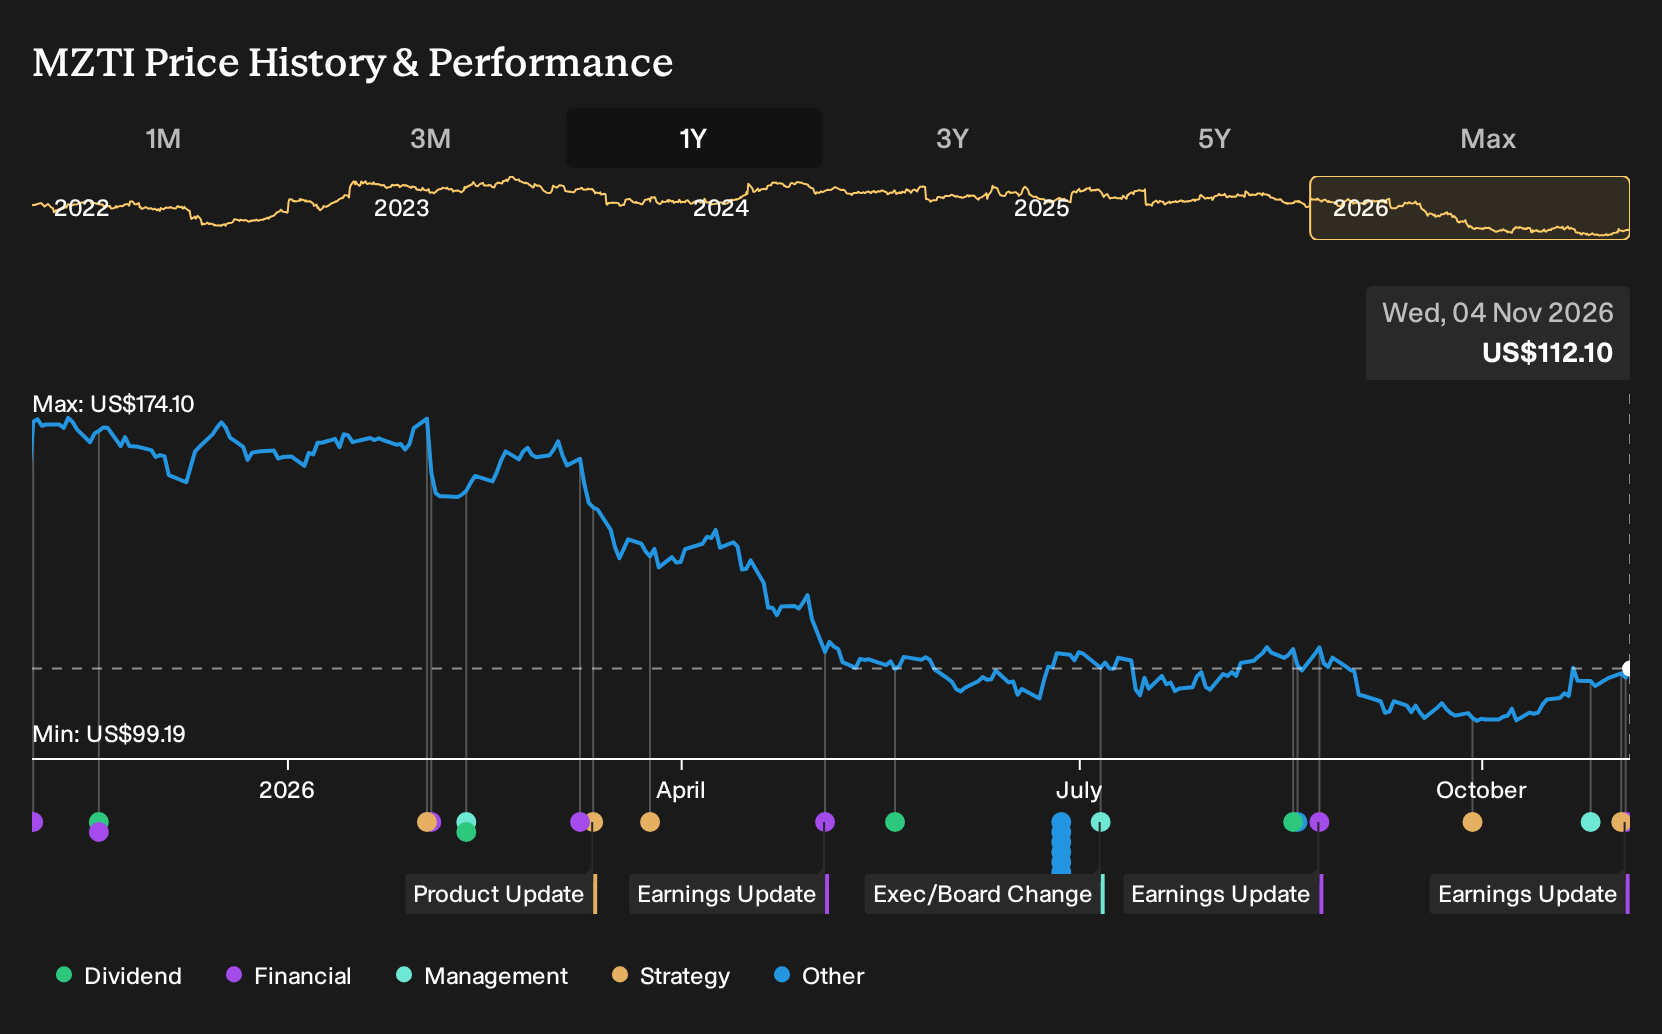
Exploring Other Perspectives
The lowest analysts on Marzetti focus on a different swing factor. They worry that heavy use of licensing and co-manufactured brands like Bachan’s could keep earnings closer to about US$192.4 million on roughly US$2.1b of revenue by 2029. That is a more cautious story than consensus, and this latest earnings setback may push some forecasts closer to that view. You can use these gaps to test which version of the future you find more realistic.
Explore 2 other Marzetti fair value estimates, including one that suggests it could be worth just $119.14.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Marzetti research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Marzetti. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marzetti's overall financial health at a glance.
Looking For More Investment Ideas Beyond Marzetti?
If Marzetti has sharpened your focus on fundamentals, use that same lens to scan a wider opportunity set with the Simply Wall St Screener.
- For investors who care most about strong finances and durable balance sheets, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions.
- If value is your priority and you want quality businesses trading below what their numbers might justify, filter using 35 high quality undervalued stocks that already combine robust fundamentals with more modest pricing.
- Income focused investors who prize consistency over excitement can zero in on 5 dividend fortresses that aim to keep cash flowing even when markets feel uncertain.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com