
Can Gap Stock Benefit From A Better Holiday Outlook After The Election
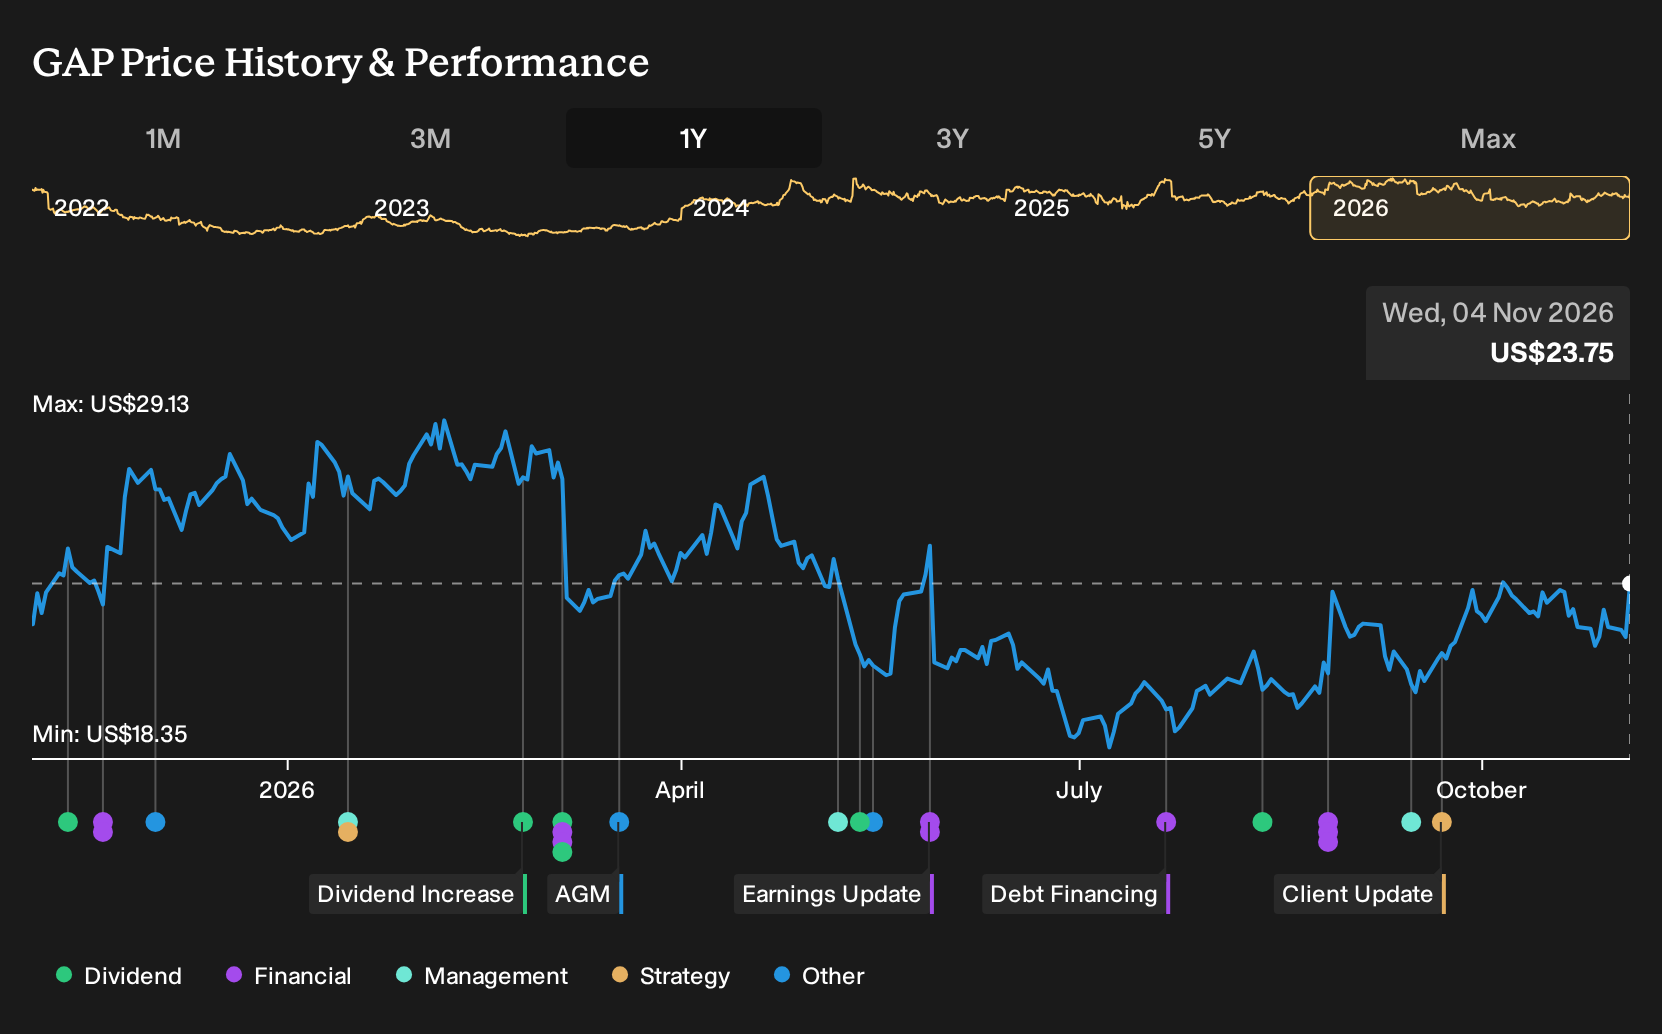
- Gap Inc. shares reacted to a clearer U.S. election outcome that put Democrats in control and improved the retail outlook for the 2026 holiday season. Investors also responded to optimism that easing conflict with Iran could reduce oil prices and support consumer confidence.
- The key angle for Gap is not politics itself but the prospect of steadier fuel costs and stronger shopper sentiment feeding into holiday apparel demand. This directly links macro headlines to the retailer’s store traffic, online volumes and promotional decisions.
- We will examine how Gap's investment narrative intersects with the improved retail outlook that followed the decisive U.S. election result.
See how Gap fits into a wider retail rebound thesis by comparing it with our hand-picked 35 high quality undervalued stocks that could also benefit from stronger consumer confidence and steadier fuel costs.
Gap Investment Narrative Recap
Owning Gap ultimately means believing management can keep improving profitability while fixing Old Navy and Athleta execution issues. The recent election outcome and the prospect of steadier fuel costs may help discretionary demand, but the key near term catalyst is still whether Old Navy’s assortments and promotions land cleanly for the holiday season and beyond.
The biggest operational risk remains persistent underperformance at Athleta and ongoing discounting at Old Navy. If heavier promotions are required to move inventory, any benefit from higher traffic could be offset by weaker merchandise margins. This matters more for Gap than incremental macro relief on fuel or consumer confidence.
With no fresh corporate announcements tied directly to the election, the most relevant recent data point is still Gap’s Q2 2026 margin picture. Adjusted gross margin at 41.4%, tariff relief, cost discipline and cash of US$2.5b give the business more room to absorb demand swings than in past cycles, including potential volatility around holiday spending.
For catalysts, that balance sheet and margin buffer underpin efforts like Fashiontainment, Old Navy Sport and beauty expansion, which are aimed at driving traffic and higher basket sizes. On the risk side, analysts still forecast earnings to decline 9.7% per year over the next 3 years, so execution on assortments and promotions needs to do the heavy lifting if the macro tailwind from lower fuel and stronger sentiment proves modest.
Gap's current analyst narrative points to revenues of US$16.5b and earnings of US$970.5m by 2029, based on 2.4% yearly revenue growth and an earnings decline of about US$229.5m from US$1.2b today.
Uncover why Gap's fair value indicates Gap has a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The lowest analysts put far more weight on Old Navy and Athleta weakness than on any help Gap might get from the election driven boost to holiday sentiment and fuel cost expectations. Before this news, they were modelling roughly US$16.4b of revenue and about US$850.6m of earnings by 2029. That is a much harsher read than consensus, which is why it can be useful for you to compare several viewpoints and decide how this latest political and geopolitical shift might reshape those stories.
Explore 5 other Gap fair value estimates, including one that suggests up to 12% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Gap research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Gap. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gap's overall financial health at a glance.
Looking For More Investment Ideas Beyond Gap?
Once you have a view on Gap, it can help to widen the lens and compare it with other opportunities that have different risk profiles, balance sheets and income potential.
- If you want to focus on value and quality together, take a look at our 35 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them.
- For investors who care most about resilience and capital preservation, start with companies in the 31 resilient stocks with low risk scores that screen well on financial stability and business risk.
- Income focused readers can scan a curated 5 dividend fortresses that aim to pair higher yields with sturdier underlying businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com