
Cousins Properties (CUZ) On Its Dallas Venture And The Case For More Upside
Cousins Properties (CUZ) is back in focus after forming a joint venture with Trammell Crow Co. to acquire a 2.3 acre Uptown Dallas site tied to Morgan Stanley’s planned regional hub.
The joint venture news has landed on top of an already strong run for Cousins Properties, with a 1-day share price return of 3.73% lifting the stock to US$30.33 and adding to a 10.98% 30-day share price gain and 17.01% year to date. That move comes after quarterly earnings in late October and a string of announcements that investors appear to read as expanding the development pipeline rather than adding disproportionate risk. This is reflected in a 23.03% 1-year total shareholder return and a very large 3-year total shareholder return of about 8x, even though the 5-year total shareholder return is slightly down at 3.21%.
Scan other Sun Belt REITs showing similar momentum and development pipelines by reviewing the hand-picked list of solid balance sheet and fundamentals (24 results) that may echo parts of the Cousins Properties story.
Bulls see Cousins Properties turning a high profile Dallas move and recent earnings into proof the valuation gap is too wide. Bears point to office risk and mixed longer term returns. Which story does the current pricing fit?
Most Popular Narrative: 10% Undervalued
Against the last close of $30.33, the most followed narrative for Cousins Properties pegs fair value at $33.55, which points to a modest valuation gap built on Sun Belt leasing strength rather than a quick trade.
Consistent flight to high quality, amenitized office space, reflected in 49 consecutive quarters of positive second generation cash rent roll ups and net effective rents in 2026 that are 8.5% to 16.8% above 2025 levels, is giving Cousins Properties pricing power that can support higher rental revenue and cash NOI.
See why 3 investors see Cousins Properties as 10% undervalued.
Result: Fair Value of $33.55 (UNDERVALUED)
Still, the Cousins Properties story can break if Sun Belt office demand cools, or if large lease expirations create longer vacancy gaps than expected.
Find out about the key risks to this Cousins Properties narrative.
Another View: Cousins Properties Through The P/S Lens
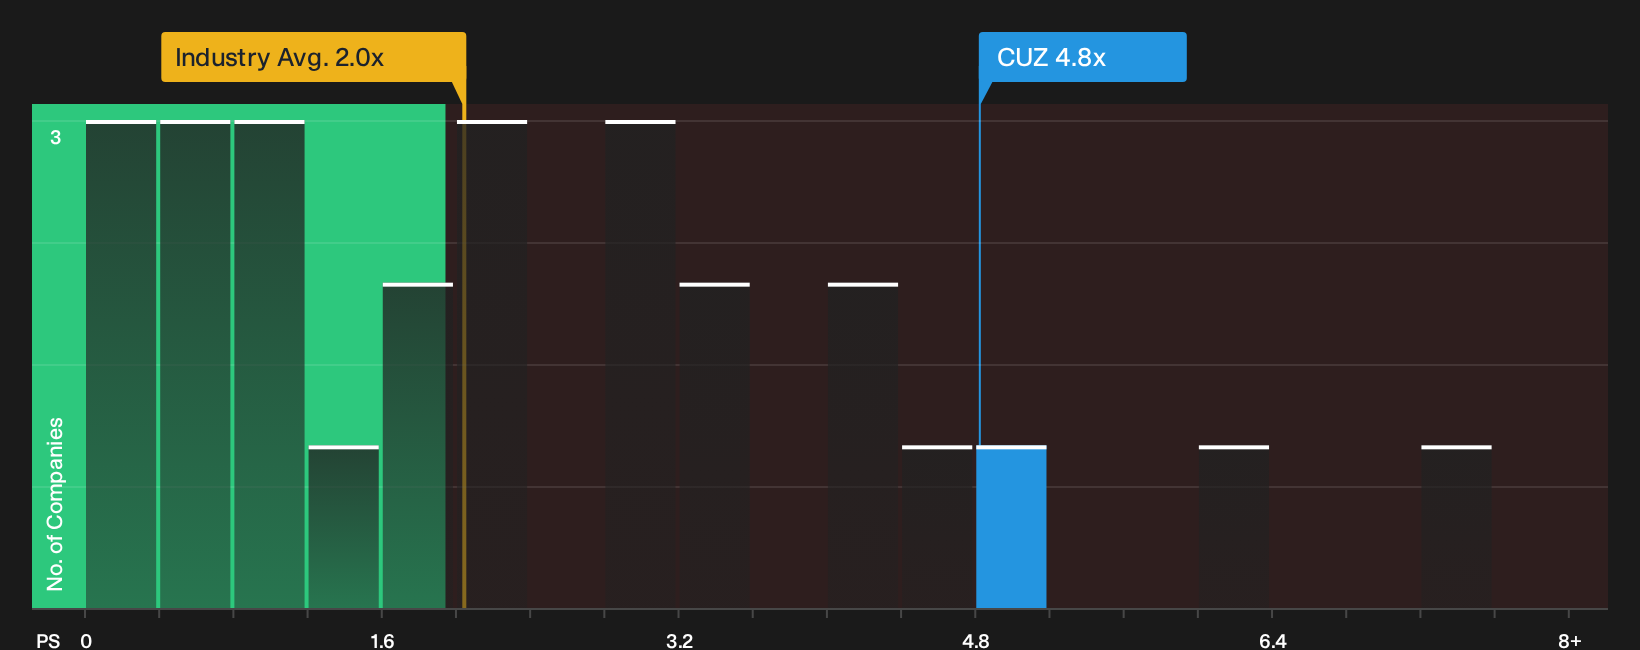
The DCF narrative presents Cousins Properties as potentially undervalued, yet the simple revenue multiple sends a different signal. CUZ trades on a P/S of 4.8x compared with 4.1x for peers and 2.0x for the wider US Office REITs group, while the fair ratio is estimated at around 4.9x. Is that a mispricing you lean into, or a premium you treat with caution?
See what the numbers show before you decide where you stand on Cousins Properties with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Clear bull and bear cases now sit side by side for Cousins Properties, so move quickly, review the data in detail, and weigh both the 2 key rewards and 4 important warning signs
Looking for more Cousins Properties style ideas?
If Cousins Properties has sharpened your focus on quality and pricing, do not stop here. Broaden your watchlist and give yourself better options.
- Target potential mispricing opportunities by scanning companies that currently screen as 35 high quality undervalued stocks before attention and liquidity crowd in.
- Strengthen your income playbook by reviewing a curated group of 5 dividend fortresses that aim to combine meaningful yield with resilience.
- Prioritise resilience over drama by focusing on a 31 resilient stocks with low risk scores that filters for businesses with steadier profiles and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com