
Axsome Therapeutics (AXSM) Could Be 42% Undervalued After Its $1b Revenue Run Rate
Axsome Therapeutics (AXSM) drew fresh attention after its latest Q3 update, where management highlighted a revenue run rate above US$1b and a sharply smaller net loss compared with last year.
Despite the stronger Q3 story, Axsome Therapeutics’ recent trading has been choppy, with the share price down 21.4% over the past month and 35.6% over the last 90 days. However, the 3 year total shareholder return of 128.1% and 5 year total shareholder return of 246.66% still point to a very strong longer term journey.
Scan Axsome Therapeutics alongside hand-picked CNS-focused peers and see how it compares to 19 high quality undiscovered gems in today's market.
Axsome Therapeutics just crossed a US$1b annualized revenue run rate, yet the share price has slid hard in recent months. Is that recent drop enough to justify stepping in now, or does waiting for a deeper pullback make more sense once you look at the valuation?
Most Popular Narrative: 42% Undervalued
Axsome Therapeutics closed at $137.00 against a widely followed fair value of $238.00, so the key question is whether the growth, margin and risk assumptions behind that gap feel realistic for you.
While management presents an aggregate peak sales opportunity of at least US$18b across the portfolio and a goal of roughly one NDA filing per year into 2031, the growing list of late stage programs across smoking cessation, ADHD, binge eating disorder, MDD with excessive sleepiness, fibromyalgia and shift work disorder may stretch execution and require higher trial and launch spending than modeled. This could weigh on net margins even if individual approvals occur.
See why 3 investors see Axsome Therapeutics as 42% undervalued.
Result: Fair Value of $238.00 (UNDERVALUED)
Still, Axsome Therapeutics could see this cautious setup challenged if Auvelity prescriptions in Medicare stay strong or if several late stage CNS programs secure approvals.
Find out about the key risks to this Axsome Therapeutics narrative.
Another View: What Axsome Therapeutics’ P/S Ratio Is Telling You
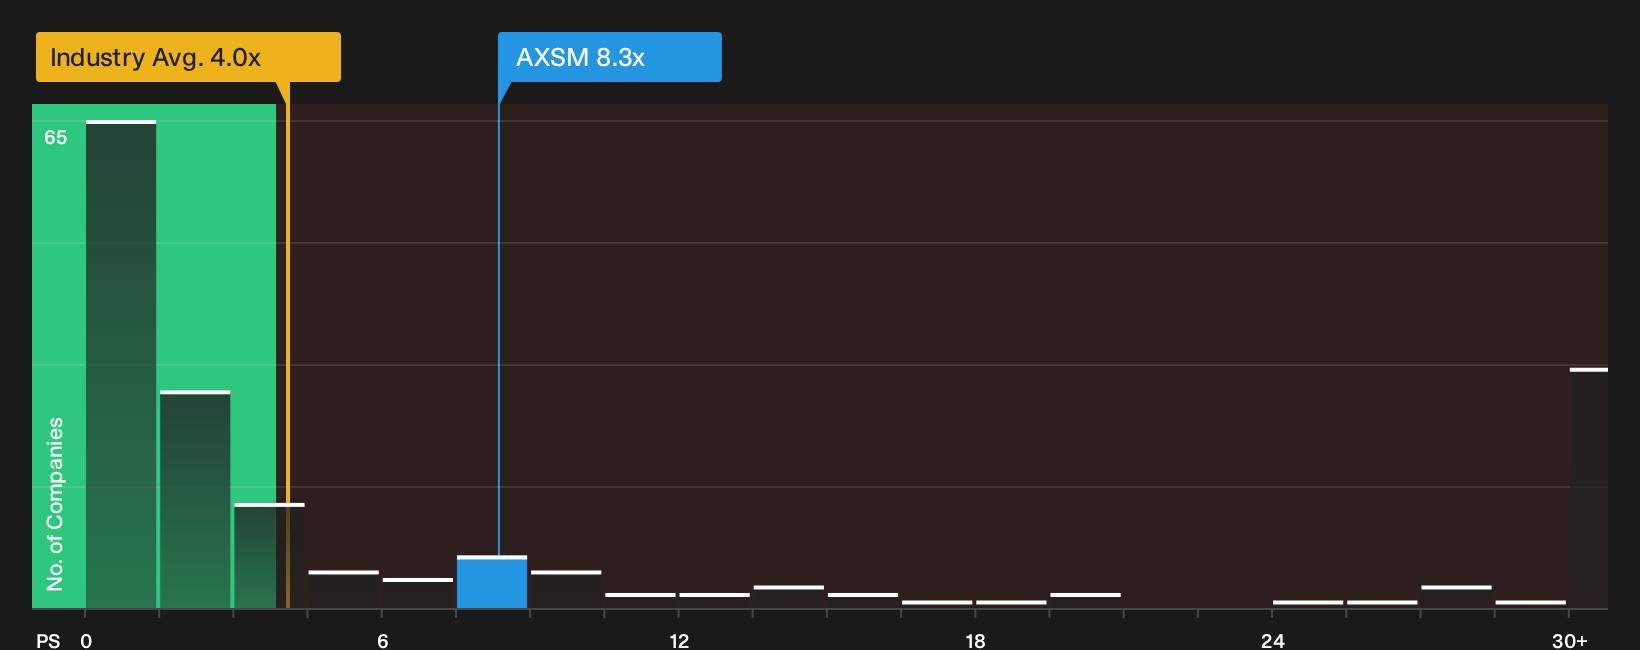
Axsome Therapeutics screens as deeply undervalued against the $238.00 fair value and future cash flow estimate, yet the current P/S of 8.3x sits above the US Pharmaceuticals average of 4x and below its own fair ratio of 14.1x. That mix points to both upside potential and clear valuation risk, so which side matters more for you right now?
See what the numbers say about this price by digging into our valuation breakdown next, including how that P/S gap compares across peers and where the fair ratio suggests the market could eventually gravitate, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Seen enough bullish and cautious takes for one day. Review the numbers in front of you, move quickly while the data is fresh in your mind, and then consider those 3 key rewards next in 3 key rewards
Looking For More Investment Ideas Beyond Axsome Therapeutics?
If you want a fuller picture of opportunities, broaden your watchlist with fresh ideas that match your goals and risk comfort using Simply Wall Street’s screener tools.
- Target robust cash generation and balance sheet strength by scanning companies on the list of solid balance sheet and fundamentals (24 results) built to handle tougher conditions.
- Hunt for quality at a discount by reviewing the 35 high quality undervalued stocks that currently trade below their assessed worth on fundamentals.
- Prioritize sleep-at-night stability by focusing on the 31 resilient stocks with low risk scores that score well on resilience and downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com