
How Investors May Respond To Primerica (PRI) Earnings Beat
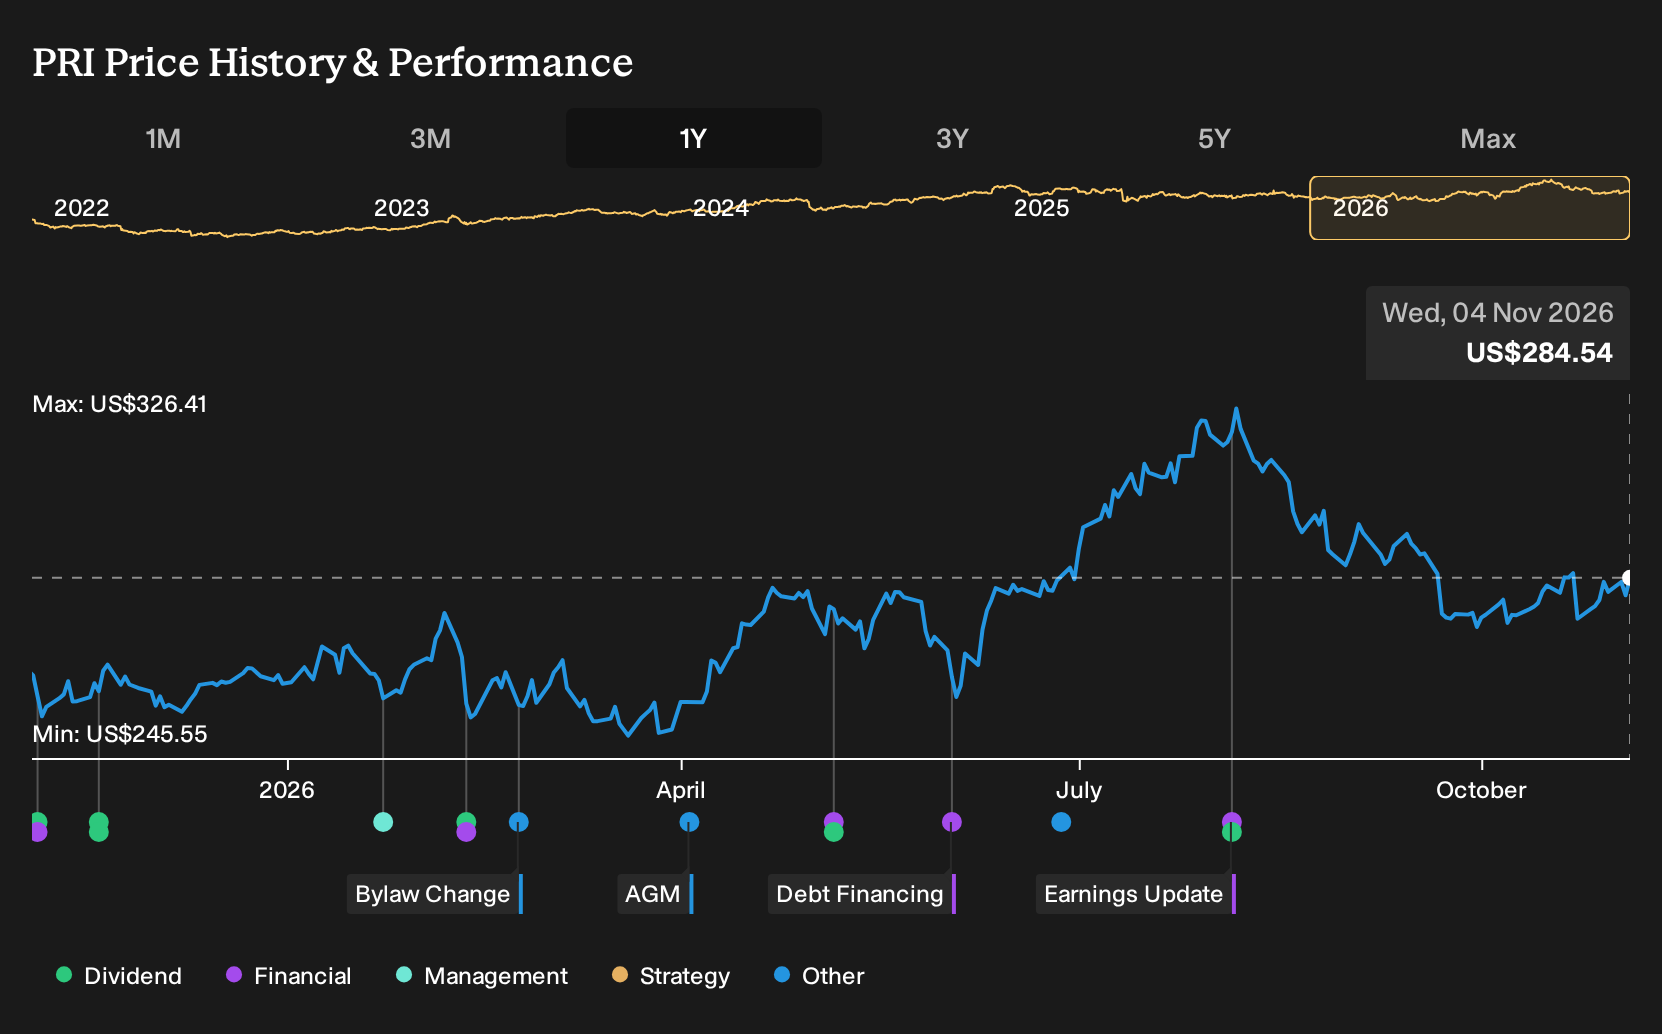
- Primerica reported third quarter 2026 results with revenue of US$901.65 million, net income of US$209.13 million, and diluted EPS of US$6.76, all slightly above analyst expectations.
- The quarter highlighted record investment and savings product sales and US$140b in client assets, while the term life franchise continued to generate steady earnings support.
- We will look at how Primerica's investment narrative is influenced by strong fee based investment sales and earnings beating analyst expectations.
Primerica Investment Narrative Recap
To own Primerica, you need to believe the mix shift toward fee based Investment & Savings Products can keep pulling more weight while the large in force term life block steadies earnings. The latest quarter supports that view, with record investment sales and US$140b of client assets reinforcing the idea that the advice led model still resonates with middle income households.
The key near term swing factor is whether expense growth tied to technology projects eases enough for that higher fee revenue to translate into cleaner operating leverage. The biggest risk is that pressure on new term life policies and a smaller licensed sales force lingers, which could cap future premium growth even as current results look solid.
The most relevant recent announcement is Q3 2026 earnings, where Primerica reported revenue of US$901.65 million and net income of US$209.13 million with diluted EPS of US$6.76, all slightly ahead of expectations. Record investment and savings product sales and stronger commissions and fees show the fee based side is doing the heavy lifting right now.
For catalysts, that same update matters because it links higher client asset values and investment product demand to tangible earnings delivery, while management still leans on a stable term life franchise for consistency. The risk is that rising insurance and operating expenses, including technology spending, stay elevated relative to revenue and limit margin improvement even if top line and EPS keep tracking ahead of forecasts.
Primerica's narrative projects US$4.1b revenue and US$871.5m earnings by 2029. This assumes 5.4% yearly revenue growth and an earnings increase of about US$77.9m from US$793.6m today.
Uncover how Primerica's fair value indicates a 14% potential upside to its current price, which could narrow quickly if sentiment continues to improve.
Exploring Other Perspectives
Simply Wall St Community members offer only two fair value estimates for Primerica so far, ranging from about US$325 to more than US$720 per share. This already shows how far opinions can stretch. Set that against risks around term life policy trends and expense growth, and you can see why exploring multiple viewpoints really matters.
Explore another Primerica fair value estimate, including one that suggests as much as 153% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Primerica research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Primerica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Primerica's overall financial health at a glance.
Looking For More Investment Ideas Beyond Primerica?
If the Primerica story has sharpened your thinking about earnings quality and business mix, use that momentum to widen your watchlist. The Simply Wall St Screener lets you filter for companies that fit your own risk tolerance, income needs, and balance sheet preferences in a few quick steps.
- If resilience matters most to you, start with companies that pair durable fundamentals with relatively lower risk profiles through the 31 resilient stocks with low risk scores.
- Income focused investors can explore higher yielding opportunities that still emphasise stability by scanning the 5 dividend fortresses.
- For those looking for quality businesses that may not be widely followed yet, the 19 high quality undiscovered gems can surface candidates with solid underlying numbers that the market may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com