
MACOM Technology Solutions Holdings (MTSI) Heads Into Earnings, Is It Priced For Perfection?
MACOM Technology Solutions Holdings (MTSI) heads into its Q4 2026 earnings release today, with attention on data center, industrial and defense, and telecom demand, as well as the impact of higher factory utilization.
Recent trading has cooled sentiment around MACOM Technology Solutions Holdings, with the share price falling 33.52% over the past month and 25% over the past 90 days. This comes even though the year-to-date share price return is 33.25% and the 1-year total shareholder return is 39.67%.
Scan beyond MACOM Technology Solutions Holdings and line up other semiconductor and infrastructure plays that fit this earnings-driven theme with the hand picked 53 AI infrastructure stocks.
The share price reset has been sharp, while expectations around MACOM Technology Solutions Holdings remain high. Does that recent slide now offer enough potential upside to justify the risk as valuation comes under the microscope next?
Most Popular Narrative: 39% Undervalued
On the narrative view, MACOM Technology Solutions Holdings screens as undervalued, with a fair value estimate of $384.69 against a last close of $233.13, and that gap is built on aggressive growth and margin assumptions that investors need to weigh carefully.
The main factor that has to go right is that MACOM executes on its compound semiconductor capacity ramp and R&D program so that new products like high speed photodetectors, silicon photonics lasers and next generation GaN processes convert into sustained orders across a broader base of large customers.
The numbers imply that MACOM’s share price already discounts very strong growth and margin expansion. If the current high valuation multiples compress despite the company continuing to perform, equity returns could be weaker than the underlying business progress suggests.
See why 19 investors see MACOM Technology Solutions Holdings as 39% undervalued.
Result: Fair Value of $384.69 (UNDERVALUED)
Still, the bullish narrative around MACOM Technology Solutions Holdings collides with concerns that its high P/E and sharp share price swings could quickly unwind if sentiment or growth assumptions soften.
Find out about the key risks to this MACOM Technology Solutions Holdings narrative.
Another View: multiples paint a tougher picture for MACOM Technology Solutions Holdings
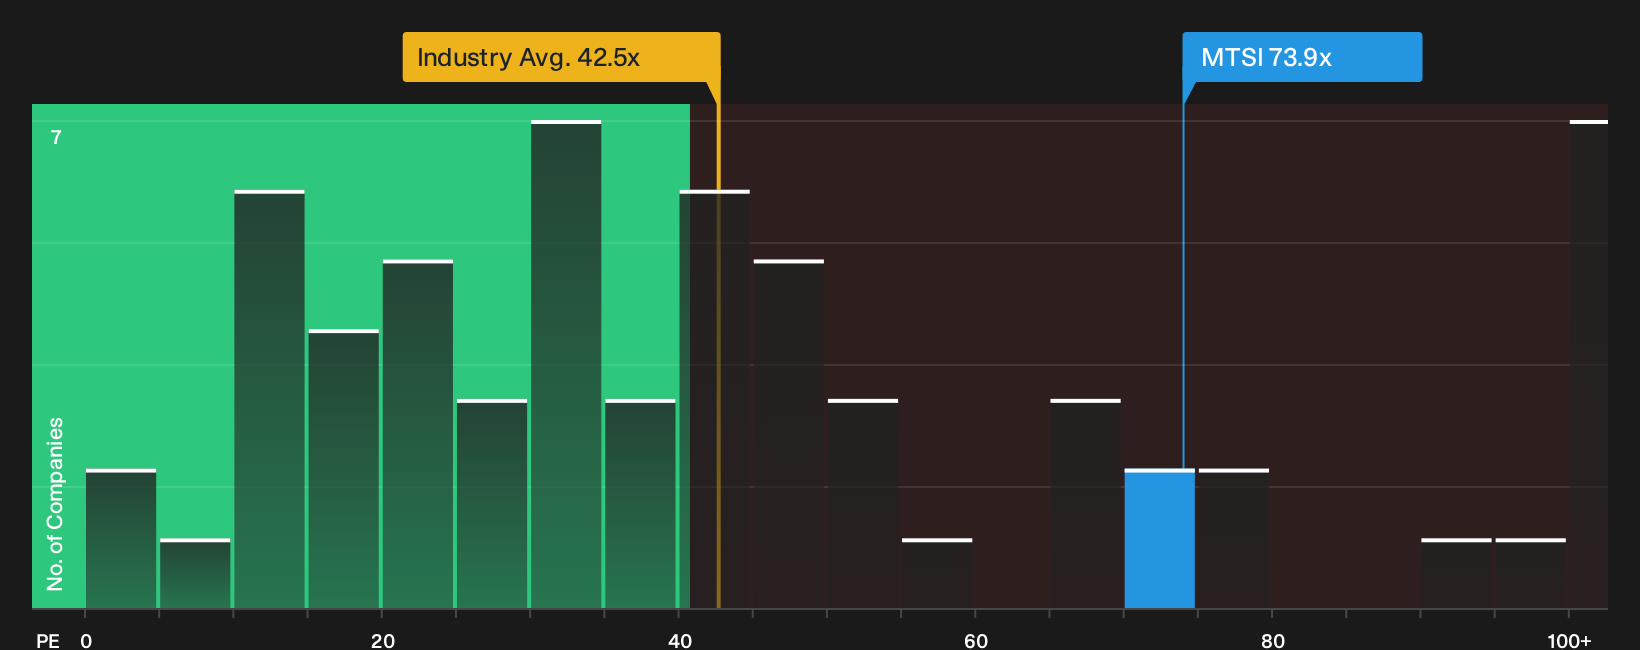
Analyst fair value work points to upside, yet the simple P/E check sends a different signal. MACOM Technology Solutions Holdings trades on 73.9x earnings versus 39.8x for peers, while the fair ratio sits at 38.3x. That kind of gap can shrink fast if sentiment cools.
For a closer look at what the numbers imply, including how that rich valuation compares with peers in detail, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around MACOM Technology Solutions Holdings can pull you in both directions, so move quickly, weigh the upside and the red flags, then decide where you stand after reviewing the 3 key rewards and 2 important warning signs.
Want more ideas beyond MACOM Technology Solutions Holdings?
If MACOM Technology Solutions Holdings has your attention today, do not stop there. Use this earnings moment to refresh your watchlist with fresh ideas that match your risk profile.
- Target higher quality potential by reviewing companies that combine dependable cash generation with attractive pricing through the 35 high quality undervalued stocks.
- Prioritise resilience and capital protection by scanning a focused 31 resilient stocks with low risk scores that keeps volatility in check without abandoning opportunity.
- Strengthen your core holdings by tracking businesses with cleaner finances and robust fundamentals using the curated list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com